Friday, October 9, 2026
Home Blog Page 121

Empowering Mobile Transactions: Strategic Insights into the M-commerce Payment Market

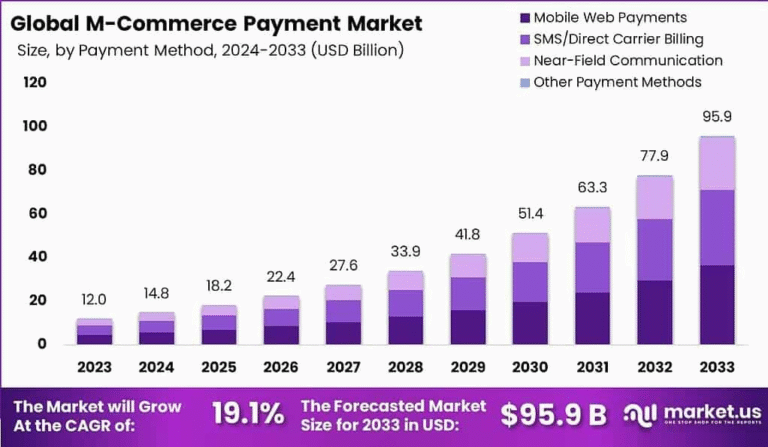
The M-commerce Payment Market is valued at approximately USD 7.3 trillion in 2024 and is projected to reach USD 14.2 trillion by 2030, growing at a CAGR of 11.5%. This rapid growth is fueled by the global surge in smartphone penetration, digital wallets, and mobile banking adoption. As mobile-first consumer behavior reshapes commerce, secure and frictionless payment solutions are in high demand. Retail, travel, and food delivery sectors are especially impacted, while innovations in biometric security, QR-based payments, and contactless technologies are driving adoption across both developed and emerging economies.

Key Takeaways

  • Market projected to reach USD 14.2 trillion by 2030

  • CAGR of 11.5% during 2024–2030

  • Driven by mobile wallet usage, 5G rollout, and app-based shopping

  • Contactless and in-app payments dominate in urban regions

  • QR code-based payments surge in APAC and LATAM

  • Security and authentication solutions critical for growth

  • E-commerce platforms heavily integrated with m-payment gateways

  • Buy Now, Pay Later (BNPL) options boosting conversion rates

  • P2P payments rising via messaging and social media apps

  • Fintech innovation and government support drive expansion

Emerging Trends
Emerging trends include the rise of biometric authentication (face and fingerprint recognition) for secure transactions. Super apps offering integrated shopping, payments, and banking are dominating in Asia. Blockchain-based mobile payments are being explored for real-time settlements. Voice-activated and wearable-enabled payments are gaining traction. Integration of AI for fraud detection and personalized recommendations enhances user experience. The adoption of cross-border m-commerce solutions is expanding due to globalized trade. Digital ID systems are being linked to mobile payment infrastructure. Offline-to-online (O2O) commerce is merging in-store experiences with mobile payment ecosystems, particularly through NFC and QR-based systems.

Use Cases

  • Retail checkout via mobile wallets and NFC for in-store purchases

  • Online shopping through app-integrated payment gateways

  • Food delivery and ride-hailing apps using one-click mobile payments

  • Event ticketing and travel bookings with mobile checkout features

  • Peer-to-peer (P2P) transfers through apps like mobile banking and e-wallets

  • Utility and bill payments via smartphone apps and SMS links

  • Subscription services for media, fitness, and software billed through m-payments

  • Parking and toll collection using QR/NFC-based solutions

  • Microtransactions in gaming and digital streaming

  • Cross-border payments for freelancers, SMEs, and e-commerce platforms

Major Challenges
Challenges include cybersecurity risks, such as data breaches and phishing attacks targeting mobile transactions. Fragmentation in payment systems across regions limits interoperability. Regulatory complexities, especially in cross-border transactions, hinder smooth adoption. Digital literacy gaps in rural and aging populations reduce accessibility. Device and OS compatibility issues affect user experience. Slow internet connectivity and technical infrastructure limitations in emerging markets pose barriers. Trust and privacy concerns surrounding data sharing deter user adoption. Additionally, high transaction fees and vendor lock-in models affect small merchants. Ensuring fraud prevention, seamless UX, and regulatory compliance remains critical for long-term viability.

Opportunities
Opportunities lie in the integration of AI-powered fraud detection, enhancing transaction security and customer trust. Expansion into rural and underserved markets using USSD and offline payment modes opens untapped segments. SMEs and micro-entrepreneurs benefit from low-cost m-payment gateways. Governments promoting cashless initiatives and financial inclusion create supportive environments. Partnerships between fintechs and telecom providers can improve service delivery. Growing demand for cryptocurrency wallets and blockchain-based payments offers innovation potential. Wearable tech and voice-assisted commerce represent future growth paths. Enhanced data analytics capabilities also enable personalized financial services and offers, improving consumer engagement and retention.

Key Players Analysis
Key participants in the m-commerce payment market are focused on providing secure, scalable, and user-centric solutions across digital wallets, mobile banking, and in-app payment systems. These vendors invest in cloud-native infrastructure, AI-based fraud management, and multi-factor authentication. Strategic focus includes enabling cross-border payments, real-time transaction processing, and omnichannel integration with e-commerce platforms. Many offer open APIs and SDKs to accelerate third-party app integration. Collaboration with telecom operators, banks, and retailers expands reach. Emphasis is also placed on regulatory compliance, including KYC, PSD2, and AML requirements. Players compete on speed, UX design, global coverage, and technological innovation.

Conclusion
The M-commerce Payment Market is a cornerstone of the digital economy, accelerating global shifts in consumer behavior and financial accessibility. As mobile devices become primary transaction tools, the ecosystem continues to evolve through innovations in biometrics, real-time processing, and intelligent fraud prevention. While challenges around infrastructure, regulation, and data security persist, the convergence of fintech, e-commerce, and mobile technologies is creating an inclusive and efficient payment landscape. With vast opportunities in emerging markets and rapid fintech advancement, the sector is poised for transformative growth—reshaping how people buy, pay, and engage across digital platforms worldwide.
 

Precision Power: Strategic Outlook on the Global Artillery Systems Market

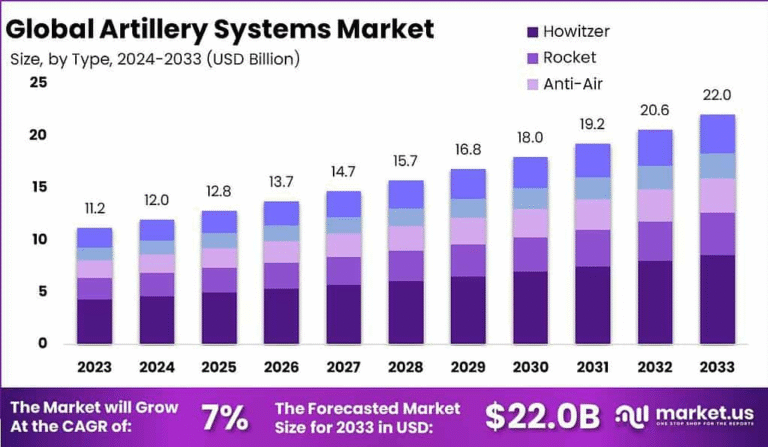
The Artillery Systems Market is estimated at USD 12.8 billion in 2024 and is projected to reach USD 19.4 billion by 2030, growing at a CAGR of 7.1%. Heightened geopolitical tensions, modernization of military arsenals, and increasing emphasis on border security and long-range precision strikes are key growth drivers. Nations are investing in advanced howitzers, self-propelled guns, rocket artillery, and mobile systems. Artillery remains a backbone of ground force capabilities, and integration with surveillance, targeting, and command systems is amplifying their strategic relevance in both conventional and hybrid warfare environments globally.

Key Takeaways

  • Global market to reach USD 19.4 billion by 2030

  • CAGR of 7.1% from 2024 to 2030

  • Demand driven by defense modernization and cross-border tensions

  • Self-propelled artillery witnessing strong procurement growth

  • Integration with UAVs and battlefield sensors on the rise

  • NATO and Asia-Pacific countries investing in 155mm systems

  • Mobile and modular artillery improving strategic deployment

  • Rocket artillery gaining relevance for area-denial strategies

  • Long-range precision and digital fire control systems are key focuses

  • Military alliances boosting interoperability standards and joint artillery programs

Emerging Trends
Emerging trends include the development of network-centric artillery systems with enhanced command and control integration. There is a shift toward autonomous targeting and AI-enabled fire control systems to reduce human error and speed up response. Mobile and modular artillery platforms are preferred for rapid deployment in diverse terrains. Extended-range guided munitions (ERGM) and smart artillery shells are improving precision and minimizing collateral damage. There is increased investment in rocket artillery, unmanned artillery platforms, and electromagnetic gun prototypes. Cross-platform interoperability is becoming crucial as joint-force coordination becomes a key component of future artillery engagements.

Use Cases

  • Long-range fire support in offensive and defensive battlefield operations

  • Area denial and suppression during combined arms maneuvers

  • Counter-battery fire using radar-guided targeting systems

  • Mountain and desert warfare with lightweight towed artillery systems

  • Urban combat support via precision-guided artillery shells

  • Peacekeeping operations requiring mobile, non-invasive fire solutions

  • Rapid deployment units utilizing self-propelled artillery for mobility

  • Training and simulation programs for artillery crews

  • Joint military exercises using interoperable NATO-standard systems

  • Amphibious and naval support with deployable coastal artillery batteries

Major Challenges
Challenges include the high cost of procurement and modernization, especially for developing nations. Logistics and maintenance of large-caliber systems in remote locations present operational issues. The need for real-time intelligence integration to maximize artillery effectiveness requires advanced infrastructure. Vulnerability to counter-battery fire and drone reconnaissance is increasing. Regulatory issues surrounding arms exports and international compliance can delay deals. Environmental and collateral risks from unguided munitions remain concerns in populated regions. Cybersecurity threats to digitally controlled fire systems add new layers of risk. Training gaps and lack of experienced personnel also hinder the full utilization of modern artillery platforms.

Opportunities
Opportunities lie in digitizing legacy artillery systems through smart retrofitting, enabling older platforms to perform at modern standards. Nations expanding their strategic deterrence are investing in long-range rocket artillery and precision systems. Joint development programs between allied nations offer cost-sharing advantages. AI-based trajectory and target optimization will further enhance precision capabilities. As military strategies shift toward network-centric warfare, the demand for C4ISR-integrated artillery rises. Export opportunities in emerging markets across Africa and Southeast Asia are strong. There is also scope for localized production and customized configurations catering to regional combat conditions. Defense R&D funding supports innovation in eco-friendly munitions.

Key Players Analysis
Key players in the artillery systems market focus on providing versatile, high-performance platforms across towed, self-propelled, and rocket artillery categories. These companies invest in precision guidance, automation, and survivability enhancements. Strong emphasis is placed on integration with C4ISR systems, GPS-guided munitions, and modular combat vehicles. Partnerships with government defense agencies support long-term procurement programs. Some vendors specialize in lightweight, rapid-deployment models suited for tactical flexibility. Others concentrate on large-caliber, long-range systems optimized for strategic bombardment. Additionally, firms offer lifecycle support, modernization packages, and interoperability solutions aligned with NATO and allied defense standards, ensuring battlefield readiness and adaptability.

Conclusion
The Artillery Systems Market is undergoing a technological transformation, driven by evolving warfare dynamics and increased demand for mobility, precision, and interoperability. While procurement costs and operational complexity present challenges, innovation in AI integration, digital fire control, and extended-range munitions is expanding capabilities. With rising global tensions and border conflicts, artillery systems remain essential to national defense strategies. Strategic investments, modernization programs, and international collaborations will continue shaping the market’s trajectory, solidifying artillery’s role as a decisive force multiplier in both conventional and asymmetric combat scenarios worldwide.


Calibrating Growth: Strategic Insights into the Global Firearms Market

The Global Firearms Market is valued at USD 19.6 billion in 2024 and projected to reach USD 26.8 billion by 2030, growing at a CAGR of 5.3%. Rising geopolitical tensions, increased defense budgets, personal security concerns, and the expansion of shooting sports are key demand drivers. Civilian demand, particularly in North America and parts of Europe, continues to shape retail trends, while military and law enforcement sectors are fueling procurement of advanced small arms and tactical weapon systems. Technological advancements and regulatory shifts are also influencing supply chains, manufacturing innovation, and global trade dynamics.

Key Takeaways

  • Market to reach USD 26.8 billion by 2030

  • CAGR of 5.3% from 2024 to 2030

  • Civilian market driven by personal protection and recreational use

  • Defense procurement rising due to border security and modernization

  • North America leads with strong retail and defense sales

  • Semi-automatic handguns dominate civilian segment

  • Tactical rifles and modular weapon systems preferred by military

  • Smart gun technology gaining interest but facing adoption hurdles

  • Asia-Pacific and Middle East showing rapid defense acquisition growth

  • Regulatory scrutiny continues to shape international trade policies

Emerging Trends
Emerging trends include the development of smart guns with biometric access controls, aiming to improve firearm safety. Modular weapon platforms are gaining popularity among militaries for customization and mission adaptability. Lightweight composite materials and enhanced ergonomics are being integrated into new firearm designs. Suppressor-ready barrels, improved recoil systems, and red-dot optics are becoming standard in premium civilian models. Advancements in 3D-printed firearm components raise both innovation and regulatory concerns. The incorporation of IoT and digital targeting systems in military applications is transforming operational accuracy. Sustainability in manufacturing is also gaining traction through eco-friendly materials and processes.

Use Cases

  • Military operations utilize assault rifles, sniper systems, and handguns for combat readiness

  • Law enforcement deploys pistols and less-lethal firearms for tactical and riot control

  • Personal protection with handguns and home-defense shotguns in civilian markets

  • Sport shooting and hunting contribute to demand for precision rifles and shotguns

  • Private security services employ firearms for asset and personnel protection

  • Training academies use dummy firearms and real weapons for safety and skill development

  • Firearms collectors and enthusiasts sustain demand for historical and limited-edition models

  • Border control and paramilitary units rely on high-caliber rifles and carbines

  • Peacekeeping operations require modular weapons for multi-scenario deployment

  • Emergency responders use tactical firearms for rapid, high-risk interventions

Major Challenges
Key challenges include regulatory restrictions and tightening gun laws in various countries, especially affecting civilian markets. The illegal firearms trade remains a global security issue, requiring stricter controls and enforcement. Product liability and safety concerns continue to challenge manufacturers. The rise of ghost guns and untraceable 3D-printed weapons adds a layer of legal and ethical complexity. Supply chain disruptions—especially for critical components—affect timely production and delivery. Public perception and social activism against gun violence pressure brands and retailers. Import/export restrictions and compliance with ITAR and national policies complicate global operations, especially for dual-use firearm technologies.

Opportunities
There is growing opportunity in smart gun development, offering safer firearms for civilians and law enforcement. The modernization of military arsenals across emerging economies presents long-term contracts for defense firearm suppliers. Demand for less-lethal alternatives like rubber-bullet guns and tasers opens up adjacent markets. Women and first-time buyers represent an expanding segment in the civilian market. Tactical accessories and customization kits create recurring revenue streams. Virtual firearm simulators and training systems are in demand for law enforcement and military use. Sustainable firearm manufacturing using eco-conscious materials is gaining traction. Expanding e-commerce distribution also enables wider product reach and brand engagement.

Key Players Analysis
Major players in the firearms market focus on innovation, durability, and regulatory compliance. These companies offer a wide range of products, including handguns, rifles, shotguns, sniper systems, and accessories, designed for both civilian and military users. They invest heavily in R&D to improve safety, ergonomics, and modularity. Global expansion is achieved through strategic defense contracts, dealership networks, and licensed exports. Many firms are also involved in ammunition and training simulators, enhancing their integrated offering. Partnerships with governments and law enforcement agencies are crucial to securing large-scale contracts. Key vendors emphasize quality certifications, testing standards, and adapting to regional policy frameworks.

Conclusion
The global Firearms Market is evolving with a delicate balance between security needs and regulatory pressures. While defense modernization and civilian protection continue to fuel steady growth, public safety concerns, technological disruption, and compliance mandates shape its future. Innovation in smart guns, material sciences, and training systems presents strong potential, while manufacturers must navigate the tightening grip of legal frameworks and societal expectations. With geopolitical uncertainty and increasing defense investments, the market remains resilient and dynamic—requiring strategic agility, ethical manufacturing, and innovation to thrive in a rapidly transforming security environment.


Driving ESG Compliance: Strategic Insights into the Sustainability Reporting Software Market

The Sustainability Reporting Software Market is valued at approximately USD 1.9 billion in 2024 and is projected to reach USD 5.4 billion by 2030, growing at a CAGR of 18.9%. Increasing regulatory requirements, stakeholder pressure, and corporate ESG commitments are driving demand for advanced sustainability reporting tools. These platforms enable companies to collect, analyze, and disclose non-financial metrics aligned with global standards such as GRI, SASB, and TCFD. Enterprises are leveraging these solutions to streamline ESG data management, track carbon footprints, and enhance transparency, making sustainability reporting software a strategic imperative for modern corporate governance.

Key Takeaways

  • Market projected to reach USD 5.4 billion by 2030

  • CAGR of 18.9% from 2024 to 2030

  • Adoption fueled by mandatory ESG disclosures and global compliance frameworks

  • Growing role in corporate climate strategy and net-zero goals

  • High uptake in manufacturing, energy, and financial services

  • Cloud-based, modular platforms becoming industry standard

  • AI-driven data analysis improves reporting efficiency

  • Integrated dashboards support real-time ESG performance tracking

  • Scope 1, 2, and 3 emissions reporting tools in demand

  • Europe leads, while APAC shows rising adoption due to policy mandates

Emerging Trends
Trends shaping the market include the integration of AI and machine learning to automate ESG data aggregation and validation. Platforms are incorporating blockchain for transparent and immutable audit trails. Real-time carbon accounting and predictive analytics are gaining popularity for sustainability forecasting. The rise of industry-specific ESG templates enables faster onboarding and compliance. Mobile-first reporting tools and cloud-native platforms are becoming essential for global teams. Integration with IoT and energy management systems supports live environmental monitoring. Vendors are also embedding climate risk modeling and supply chain visibility tools, reflecting the move from retrospective reporting to proactive sustainability management.

Use Cases

  • Carbon footprint tracking and emission disclosures in manufacturing

  • Energy usage analysis and optimization in buildings and infrastructure

  • ESG performance dashboards for board reporting and investor transparency

  • Supply chain impact assessments using upstream and downstream data

  • Compliance reporting with standards like GRI, CDP, TCFD, SASB

  • Water usage, waste, and biodiversity impact tracking in mining and agriculture

  • Employee health, safety, and diversity metrics in HR reporting

  • Scenario analysis for climate risk exposure in finance and insurance

  • Stakeholder engagement tools including ESG survey and materiality assessment

  • Automated audit trail generation for third-party sustainability assurance

Major Challenges
Challenges include data fragmentation, with ESG metrics scattered across departments and systems. Lack of standardization in global ESG frameworks complicates unified reporting. Smaller organizations face resource constraints in adopting full-featured platforms. Accuracy and reliability of non-financial data remain concerns, especially for Scope 3 emissions. Manual data collection processes in legacy systems hinder real-time tracking. There’s also a shortage of qualified ESG professionals to interpret and validate sustainability metrics. Integration with financial and operational systems can be complex and time-consuming. Additionally, navigating evolving regulatory landscapes and avoiding greenwashing allegations require continuous software and policy updates.

Opportunities
Opportunities abound in building AI-enhanced, industry-specific ESG platforms. Governments mandating non-financial disclosures are boosting adoption globally. Integration with carbon accounting tools, IoT sensors, and energy management systems creates real-time reporting potential. Expansion in SME-focused solutions offers a growth frontier. The rising importance of supply chain sustainability opens opportunities for value-chain analytics. Investors increasingly demand impact transparency, driving demand in the financial sector. SaaS-based platforms with rapid deployment models are appealing for multi-national corporations. Additionally, opportunities exist in creating regional language interfaces, improving audit readiness, and offering customizable dashboards aligned with different ESG frameworks and jurisdictional needs.

Key Players Analysis
Leading companies in the sustainability reporting software market focus on offering modular, scalable solutions that cover environmental, social, and governance metrics. These platforms prioritize compliance with international standards and offer automated data collection, AI-based analytics, and customizable reporting dashboards. Vendors invest in cloud-native infrastructure and API integrations to streamline ESG data workflows across business systems. Strategic emphasis lies on visualization tools, audit readiness, and supply chain analysis. Partnerships with consultancies, ESG rating agencies, and financial platforms enhance market reach. Firms also focus on sector-specific modules, enabling tailored reporting for industries like energy, finance, and manufacturing.

Conclusion
The Sustainability Reporting Software Market is evolving into a cornerstone of enterprise ESG strategy, driven by rising regulatory expectations, investor scrutiny, and climate accountability. While data quality, standardization, and system integration present persistent challenges, technological advances in AI, IoT, and cloud computing are unlocking scalable, intelligent solutions. As organizations strive for transparency and measurable impact, these platforms will be crucial in guiding decision-making and risk management. With expanding global mandates and growing stakeholder expectations, sustainability reporting software is not just a compliance tool—it’s a strategic asset shaping the future of responsible business operations.


Decoding Digital Efficiency: Strategic Outlook on the OCR Technology Market

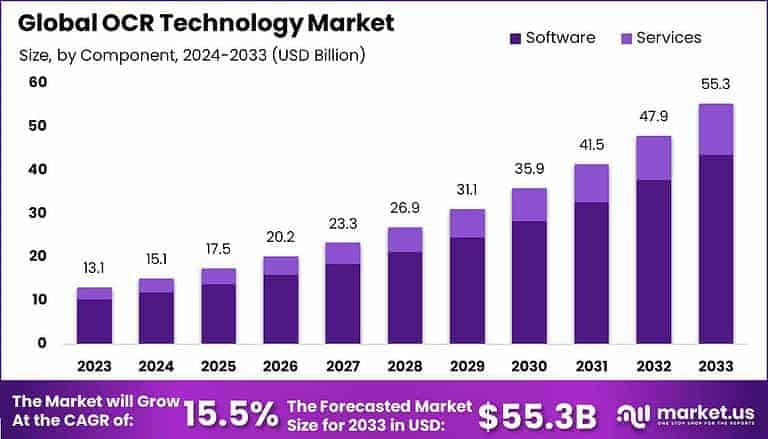
The Optical Character Recognition (OCR) Technology Market is valued at approximately USD 13.2 billion in 2024 and is projected to reach USD 29.7 billion by 2030, growing at a CAGR of 14.5%. Increasing demand for digitized documentation, automated data entry, and real-time text recognition in sectors such as banking, healthcare, logistics, and government is driving the market. As organizations seek to enhance efficiency and reduce manual errors, OCR solutions integrated with AI and machine learning are enabling seamless text extraction, searchability, and document workflow automation across printed, handwritten and scanned content.

Key Takeaways

  • Market to reach USD 29.7 billion by 2030

  • CAGR of 14.5% during 2024–2030

  • Adoption driven by digital transformation and regulatory compliance

  • AI-enhanced OCR boosting accuracy for complex layouts and languages

  • Widespread use in BFSI, healthcare, legal, logistics, and education

  • Mobile OCR expanding with document scanning apps and ID verification

  • Rising demand in automation, RPA, and intelligent document processing

  • Cloud-based OCR solutions gaining momentum for scalability

  • Government initiatives supporting paperless infrastructure drive demand

  • Growing need for searchable, structured, and indexed digital records

Emerging Trends
Key trends include the integration of AI and machine learning into OCR engines to improve recognition of diverse fonts, scripts, and low-resolution images. Handwriting recognition (ICR) is evolving to support multilingual documents and cursive writing. Cloud-based OCR platforms offer scalable, API-driven services for enterprises. OCR for mobile devices is growing, enabling on-the-go scanning and real-time translations. Enhanced data validation and classification features are being added for compliance and automation. Edge OCR for offline processing is emerging in logistics and field services. Additionally, combining OCR with natural language processing (NLP) helps extract contextual meaning and actionable insights from text.

Use Cases

  • Invoice and receipt digitization in finance and accounting systems

  • Passport and ID verification in banking and border control

  • Medical record transcription in hospitals and clinics

  • Legal document archiving and contract analysis in law firms

  • Handwritten form processing in government and educational institutions

  • Real-time translation of signage and documents via mobile OCR apps

  • Automated data entry in logistics and supply chain documentation

  • Digitizing printed books and archives for libraries and publishers

  • OCR-enabled document search in corporate knowledge management systems

  • Cheque and handwriting recognition in banking operations

Major Challenges
The market faces challenges such as low accuracy in noisy or poorly scanned documents, especially those with mixed content formats or handwritten text. Complex document layouts, such as tables or forms, require advanced OCR models and layout analysis. Language diversity and font variability hinder global scalability. Data privacy concerns arise when processing sensitive information, particularly in cloud-based OCR solutions. Integration with legacy IT systems remains a bottleneck for many organizations. Licensing and pricing models can be prohibitive for SMEs. OCR output may lack semantic context, limiting utility for analytics unless combined with NLP or RPA tools.

Opportunities
Opportunities lie in expanding AI-powered OCR in verticals like insurance, retail, and healthcare. The growing demand for remote onboarding and eKYC supports real-time OCR verification. Digital transformation initiatives in emerging economies present large-scale document digitization prospects. Integrating OCR with RPA and workflow automation platforms creates value in business process optimization. Multilingual OCR engines cater to global enterprises and multilingual government records. The demand for cloud-native OCR APIs in app development is also rising. With increasing attention to accessibility, OCR can aid screen readers and digital content adaptation for visually impaired users. Data analytics integration offers deeper, contextual insights from scanned content.

Key Players Analysis
Key participants in the OCR technology market are focused on delivering high-accuracy, AI-integrated OCR engines capable of processing printed, cursive, and structured documents. These vendors offer on-premises, cloud-based, and hybrid OCR solutions tailored for enterprise, government, and consumer needs. Emphasis is placed on natural language processing, handwriting interpretation, and intelligent layout detection. Many players provide API-based OCR services for app and web developers. Integration with RPA, document management systems, and ERP platforms enhances their ecosystem reach. Firms are also investing in mobile OCR, multilingual support, and real-time recognition for field operations. Continuous innovation focuses on scalability, data security, and accuracy.

Conclusion
The OCR Technology Market is a cornerstone of digital transformation, enabling faster, error-free document handling and improved data accessibility. As industries shift toward automation and paperless operations, OCR solutions play a crucial role in unlocking unstructured information from physical and digital sources. Although accuracy, language handling, and integration pose challenges, advances in AI and NLP are rapidly addressing these limitations. With strong momentum in mobile, cloud, and vertical-specific applications, OCR is poised to remain a vital enabler of business intelligence, compliance, and operational agility across sectors—bridging the physical and digital information gap with precision and scale.


Manufacturing Crisis Management Market Tackles Emergencies in Aerospace and Automotive Sectors

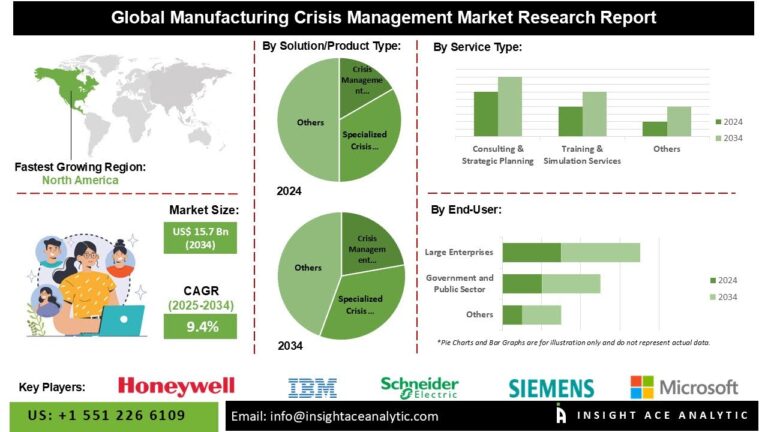
According to the latest research by InsightAce Analytic, the Global Manufacturing Crisis Management Market is valued at USD 15.7 Billion in 2024 , and it is expected to reach USD 37.5 Billion by 2034, with a CAGR of 9.4 % during the forecast period of 2025-2034.

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/2980 

Manufacturing crisis management refers to a set of strategic processes aimed at enabling organizations to effectively identify, respond to, and mitigate unexpected events that pose risks to operations, stakeholders, or brand reputation. The primary objective is to minimize operational disruptions and support rapid recovery to maintain business continuity.

The increasing frequency of supply chain disruptions has become a significant driver of growth within the manufacturing crisis management market, emphasizing the need for advanced solutions that strengthen organizational resilience and promote long-term sustainability. In parallel, evolving policy frameworks and heightened regulatory requirements aimed at improving disaster preparedness and response capabilities are further propelling market development.

Governments across the globe are recognizing the essential role of robust crisis management systems in protecting national economies and public welfare. As a result, regulatory bodies are mandating that organizations implement comprehensive crisis response and continuity plans. This regulatory push, combined with heightened awareness of operational vulnerabilities, is fueling strong demand for specialized crisis management services and technologies within the manufacturing sector. 

List of Prominent Players in the Manufacturing Crisis Management Market:

  • Siemens AG
  • SAP SE
  • IBM Corporation
  • Honeywell International Inc
  • Schneider Electric
  • Cisco Systems, Inc
  • Microsoft Corporation
  • Rockwell Automation
  • Oracle Corporation
  • Deloitte Touche Tohmatsu Limited
  • Others

Market Dynamics

Drivers:

The increasing demand for manufacturing crisis management solutions is largely driven by the growing reliance on digital infrastructure and the rising threat of cyber-attacks. As organizations become more interconnected through electronic systems, the need to protect sensitive data and maintain uninterrupted operations in the face of cyber disruptions has become paramount. In response, companies are investing in advanced crisis management frameworks, including emergency response mechanisms, business continuity tools, and comprehensive cyber resilience strategies. Additionally, the integration of artificial intelligence (AI) and machine learning (ML) is enhancing predictive analytics capabilities, enabling organizations to proactively identify vulnerabilities and mitigate potential risks before they escalate. 

Challenges:

Despite market growth, several challenges hinder widespread adoption of crisis management solutions in the manufacturing sector. High initial implementation costs often deter small and medium-sized enterprises (SMEs) from deploying advanced technologies. Resistance to change—stemming from dependence on outdated systems, limited digital infrastructure, and a shortage of skilled professionals—further constrains adoption. Concerns about data privacy and regulatory compliance, especially in highly regulated industries, add complexity to implementation. 

Moreover, global supply chains remain susceptible to unanticipated disruptions, while evolving regulatory landscapes continue to increase compliance obligations. Larger enterprises may also be hesitant to invest due to uncertainties surrounding return on investment (ROI). Addressing these issues requires vendors to offer secure, scalable, and cost-effective solutions tailored to the specific needs of diverse stakeholders, while also supporting clients through change management and workforce training initiatives. 

Regional Trends:

North America is projected to dominate the manufacturing crisis management market in terms of revenue, supported by a well-established information technology infrastructure, high awareness of disaster preparedness, and the presence of leading technology firms. The region’s robust regulatory framework further encourages the adoption of crisis management solutions. Europe also represents a significant market share, with increased focus on building resilient operational systems in response to natural disasters and supply chain disruptions. European manufacturers are prioritizing the implementation of proactive crisis management strategies to minimize operational risk and ensure business continuity. 

Recent Developments:

  •       In January 2025, Oracle declared that Palantir’s automated intelligence Services (AIS) and Flatiron Architecture are usually accessible throughout Oracle’s dispersed cloud computing choices and approved on its cloud infrastructure (OCI). Companies and governments can expedite their AI ambitions by combining Palantir’s premier Intelligence and judgment accelerator technologies with Oracle’s shared internet, AI facilities, and autonomous artificial Intelligence (AI) services.
  •       In December 2024, Schneider Electric, the world pioneer in Modern automated and energy-efficient digitization, extended its affiliation with the Rajasthan Royals as their Legal Sustainability Collaboration. By forming this alliance, the Rajasthan Royals squad and its administration reaffirmed their dedication to making an ecological IMPACT and inspiring their supporters to adopt eco-friendly practices to help the environment.

Segmentation of Manufacturing Crisis Management Market

Manufacturing Crisis Management Market-By Solution/Product Type

  •   Crisis Management Solutions

o   Risk & Business Continuity Management

o   Supply Chain Resilience & Crisis Response Solutions

o   Predictive Analytics and Crisis Forecasting Tools

o   Cybersecurity Crisis Management

  •   Crisis Management Platforms and Ecosystem Integrators

o   Cloud-based Crisis Management Platforms

o   IoT and Automation Platforms for Crisis Management

  •   Specialized Crisis Management Solutions

o   Workforce and Safety Crisis Management

o   Environmental Crisis Management & Sustainability

  •   Others

Manufacturing Crisis Management Market-By Service Type

  •   Consulting & Strategic Planning
  •   Implementation and Integration Services
  •   Training & Simulation Services

Manufacturing Crisis Management Market-By End user

  •   Large Enterprises
  •   Small and Medium-sized Enterprises (SMEs)
  •   Government and Public Sector
  •   Non-Governmental Organizations (NGOs)

Manufacturing Crisis Management Market-By Industry Vertical

  •   Aerospace and Defense
  •   Automotive
  •   Electronics and Semiconductor
  •   Food and Beverages
  •   Chemical and Pharmaceuticals
  •   Energy and Utilities
  •   Other Industrial Sectors

Manufacturing Crisis Management Market-By Region

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.

CGRP Inhibitor Market Led by North America Due to High Migraine Burden and R&D Investment

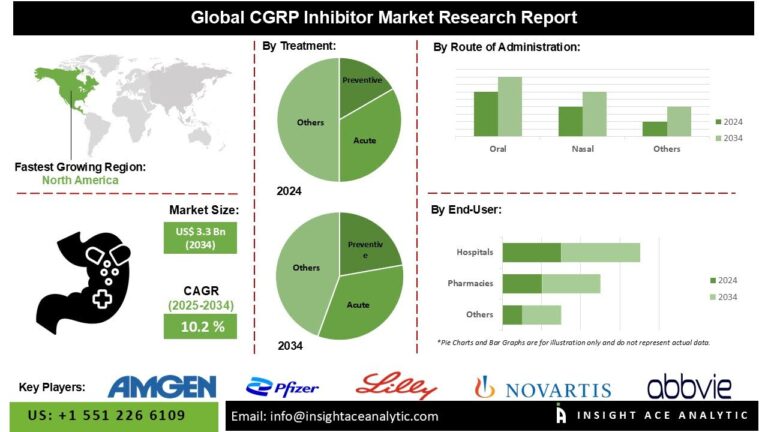
According to the latest research by InsightAce Analytic, the CGRP Inhibitor Market is valued at USD 3.3 Bn in 2024, and it is expected to reach USD 8.5 Bn by the year 2034, with a CAGR of  10.2% during the forecast period of 2025-2034.

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/2984 

Calcitonin Gene-Related Peptide (CGRP) inhibitors represent a novel and advanced class of therapeutics developed for the prevention and treatment of migraine headaches. CGRP, a neuropeptide involved in pain transmission and cerebral vasodilation, plays a pivotal role in the underlying mechanisms of migraine pathophysiology. CGRP inhibitors function by targeting either the peptide itself or its receptor, thereby effectively reducing the frequency, severity, and duration of migraine episodes.

Migraines contribute to substantial physical discomfort and impose a significant economic burden due to reduced productivity and increased absenteeism. The advancement of CGRP inhibitor therapies has been driven by considerable research and development efforts from major pharmaceutical companies. These treatments have demonstrated strong clinical efficacy and represent a significant breakthrough in migraine care, addressing a critical unmet need in the field of neurology.

List of Prominent Players in the CGRP Inhibitor Market:

  •   Eli Lilly and Company
  •   Pfizer Inc.
  •   Teva Pharmaceutical Industries Ltd
  •   AbbVie Inc.
  •   Amgen Inc
  •   Novartis AG
  •   Allergan
  •   Biohaven Pharmaceutical Holding Company Ltd.
  •   Sun Pharmaceutical Industries Ltd
  •   Lundbeck
  •   AstraZeneca plc
  •   F. HoffmannLa Roche Ltd
  •   BristolMyers Squibb Company
  •   Other Market Players

Market Dynamics

Drivers:

The rising global prevalence of complex migraines and severe headache disorders is a key driver fueling the demand for Calcitonin Gene-Related Peptide (CGRP) inhibitors. Migraines—often accompanied by symptoms such as sensory hypersensitivity, nausea, and vomiting—pose a significant public health concern due to their debilitating nature. In light of the substantial unmet medical need and associated market potential, pharmaceutical companies are intensifying research and development efforts to introduce innovative CGRP-targeted therapies. 

Challenges:

Despite their proven clinical efficacy, the high cost of CGRP inhibitors presents a notable challenge, particularly in low- and middle-income countries where financial constraints hinder access to advanced treatments. This economic burden affects both patients and healthcare systems, potentially limiting widespread adoption. Additionally, the potential for resistance to CGRP inhibitors may impact their long-term therapeutic effectiveness, emphasizing the need for continued innovation and the development of complementary treatment approaches. Addressing these challenges is essential to ensuring sustained market growth and improving global patient access. 

Regional Trends:

North America is projected to retain a dominant position in the CGRP inhibitor market in terms of revenue, supported by a strong compound annual growth rate over the forecast period. This leadership is underpinned by a well-established healthcare infrastructure, significant investment in R&D, and the presence of leading pharmaceutical companies and academic research institutions. Furthermore, the high prevalence of migraine-related disorders across the region continues to drive demand for effective and targeted therapeutic interventions, reinforcing North America’s position at the forefront of the CGRP inhibitor market.

Recent Developments:

  •   In March 2023, Pfizer Inc. announced that the U.S. FDA has approved ZAVZPRET (zavegepant), the inaugural and exclusive calcitonin gene-related peptide (CGRP) receptor antagonist nasal spray for the acute management of migraine, with or without aura, in adults.  In its crucial Phase 3 trial, ZAVZPRET demonstrated statistical superiority over placebo regarding the co-primary goals of pain relief and alleviation of the most bothersome symptom at two hours post-administration.  The crucial study also exhibited pain alleviation as soon as 15 minutes in a predetermined secondary goal compared to placebo.

Segmentation of CGRP Inhibitor Market-

By Treatment-

  •   Preventive
  •   Acute

By Route of Administration-

  •   Oral
  •   Nasal
  •   Intravenous

By End-User-

  •   Hospitals
  •   Pharmacies
  •   Specialty Clinics

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.

Dementia Care APP Market Sees Surge in Demand from Alzheimer’s and Vascular Dementia Segments

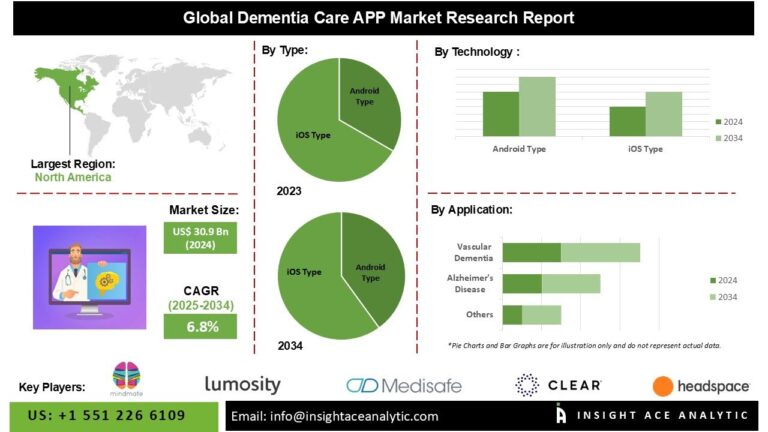
According to the latest research by InsightAce Analytic, the Dementia Care APP Market is valued at USD 30.9 Bn in 2024, and it is expected to reach USD 58.4 Bn by the year 2034, with a CAGR of 6.8% during the forecast period of 2025-2034.

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/2987 

Dementia care applications are playing an increasingly vital role in enhancing the quality of life for individuals living with dementia, as well as supporting their caregivers. These digital solutions offer a range of functionalities, including memory enhancement tools, caregiver support features, and remote patient monitoring capabilities. The rising prevalence of dementia-related conditions, largely attributed to the aging global population, is a key factor driving demand for such technologies.

Recent advancements in artificial intelligence and data analytics have enabled the creation of sophisticated applications that support continuous patient monitoring and the implementation of personalized care plans, thereby contributing to improved clinical outcomes. Furthermore, the integration of telehealth functionalities within these platforms is transforming the delivery and accessibility of dementia care services.

The widespread adoption of smartphones and tablets, coupled with ongoing technological innovation, is significantly contributing to the expansion of the dementia care application market. As mobile health solutions become more prevalent, there is a marked shift toward healthcare delivery models that prioritize accessibility, convenience, and portability.

List of Prominent Players in the Dementia Care APP Market:

  •   MindMate
  •   BrainyApp
  •   MediSafe
  •   Fit Brains Trainer
  •   Lumosity
  •   MyTherapy
  •   Elevate
  •   The Brainy App
  •   CLEAR (Secure Identity LLC)
  •   Lumos Labs Inc
  •   Headspace Inc
  •   Jigsaw Puzzles (Jigsaw Planet)
  •   Other Market Players

Market Dynamics

Drivers:

The increasing prevalence of dementia-related disorders has emerged as a significant global public health concern, driving robust demand for digital care solutions. As the global population continues to age rapidly, the number of individuals affected by dementia is expected to rise substantially, necessitating innovative approaches to care. Dementia care applications offer a broad suite of features—such as medication reminders, cognitive training exercises, appointment scheduling, and GPS-based location tracking—that not only support patient health and safety but also enhance caregiving efficiency. 

Challenges:

One of the primary barriers to the widespread adoption of dementia care applications is the limited digital literacy among elderly users. Many older individuals face challenges in using mobile devices such as smartphones and tablets, which can hinder effective interaction with application interfaces. This can reduce patient autonomy and increase reliance on caregivers, thereby potentially exacerbating caregiver workload. In response, developers are prioritizing the design of intuitive, user-friendly platforms, including features like voice-assisted navigation. Additionally, educational and training programs focused on improving digital literacy among older adults are essential to bridging this gap and promoting greater utilization of dementia care technologies. 

Regional Trends:

North America is expected to hold a substantial share of the dementia care application market and is projected to exhibit strong compound annual growth over the forecast period. This trajectory is supported by the region’s advanced digital healthcare infrastructure, significant investment in artificial intelligence and related technologies, and a favorable regulatory landscape. In particular, the United States is leading market development through strategic collaborations between emerging digital health startups and established technology firms, resulting in the creation of sophisticated dementia care platforms. Regulatory support for telehealth services has also enabled the seamless integration of these applications into traditional care models, enhancing access to remote monitoring and virtual support.

In parallel, the Asia-Pacific region represents a key growth area in the global market. Market expansion in this region is underpinned by robust healthcare infrastructure, evolving regulatory frameworks, and government-led initiatives aimed at promoting the adoption of digital health technologies. The region’s emphasis on AI-powered, data-driven healthcare solutions and patient-centered care models is accelerating the integration of dementia care applications, further contributing to overall market growth.

Recent Developments:

  • In Feb 2025, Medisafe introduced PATHWAYS, a new supplementary product aimed at optimizing patient tracking and improving care coordination, particularly for Alzheimer’s Disease (AD) management. The application assists healthcare providers, clinics, and infusion facilities in effectively managing AD patients in treatment by monitoring necessary dosing and adherence to guidelines. The instrument is intended for FDA-approved monoclonal antibodies suggested for Alzheimer’s disease.

Segmentation of Dementia Care APP Market-

By Type-

  •   Android Type
  •   iOS Type

By Application-

  •   Alzheimer’s Disease
  •   Vascular Dementia
  •   Frontotemporal Dementia
  •   Others

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Cheap Prenatal Care Near Me: Quality Care Savings

0

Have you ever wondered if you could get excellent prenatal (care during pregnancy) support without worrying about high costs? A lot of expectant moms feel stressed about rising healthcare prices. But here’s some good news: you can find quality care right in your neighborhood.

In this piece, we’re sharing a list of clinics you can rely on. These friendly places offer services based on what you can afford, and some even provide free tests and ultrasounds. It’s really all about finding affordable care so you and your baby can feel safe and well-supported during this precious time.

Cheap Prenatal Care Near You: Local Low-Cost Clinic Listings

img-1.jpg

Are you looking for caring prenatal support that won’t break your budget? This list just might be what you need. We’ve gathered five local clinics that offer quality care during pregnancy at low cost. They include community health centers, public health locations, Planned Parenthood centers, and even clinics at medical schools. Many of these options use a sliding fee scale that fits many family budgets and some even provide free services. From free pregnancy tests to low-cost ultrasounds, you'll find many of the essential services you need here.

Clinic Name Location Fee Structure Phone Number
Northridge Family Health Northridge, CA Free pregnancy confirmation and ultrasound; sliding scale 818-626-9400
City Community Clinic Los Angeles, CA Income-based sliding scale 323-555-1234
Downtown Health Department San Diego, CA Reduced-cost services 619-555-9876
Planned Parenthood Care Oakland, CA Income-based exam fees 510-555-2468
University Medical Clinic San Francisco, CA Free or low-cost care (student-run) 415-555-1357

Before you head out, it’s a good idea to give them a call. Confirm their hours and check if you meet their income requirements. Asking about sliding scale options and any extra fees can help you feel more sure and supported as you plan your visits. It’s all about finding the right care that makes you comfortable through your pregnancy journey.

Types of Cheap Prenatal Care Providers to Consider

img-2.jpg

Community health centers offer full prenatal care at a sliding fee and include local support programs that many moms appreciate. They provide routine checkups and health tests while keeping a friendly, neighborhood feel. You might even hear a staff member say, "We adjust our fees based on what you can afford so you can focus on your health." This thoughtful approach really sets them apart.

Planned Parenthood clinics and Hill-Burton facilities go a step further with affordable exams that use income-based pricing, along with early screenings and preventive care. These centers focus on teaching and offer a warm, welcoming space. It’s common to hear a mom say, "The care I got felt customized for me without breaking my budget," which shows their strong commitment to accessible maternity services.

Teaching hospitals, medical school clinics, and local nonprofit drop-in maternal centers also provide innovative care options with free or low-cost checkups. They often combine modern screening techniques with free initial assessments to keep care both high-quality and affordable. One mom shared, "I walked in for a free checkup and left with peace of mind and a clear plan for my prenatal care," highlighting the caring and patient-first approach at these facilities.

Payment and Insurance Options for Cheap Prenatal Care

img-3.jpg

Looking for affordable prenatal care? There are many financial help options that can cover your checkups, tests, and screenings without weighing down your budget. With a range of programs available, finding the right help for you can make a big difference.

Medicaid and CHIP often cover your prenatal visits with little or no co-pay (a small payment required at the time of service), depending on where you live and how much you earn. Many moms have shared how relieved they felt when their state program helped cover most of their care, making it a trusted choice for keeping costs low.

If you have a plan from the Health Insurance Marketplace, you might get premium tax credits that lower your monthly premiums. This support can ease the expenses for essential prenatal services, helping you plan your budget more comfortably during this important time.

Some clinics offer charity-care programs or self-pay discounts if you don’t have insurance. This means that, if you qualify, you can receive the same quality care at a lower cost. It's a great way to keep up with important checkups without stretching your finances too thin.

Government-backed maternity clinics may also provide free prenatal screenings and lab tests as part of their services. These free offerings help you stay on track with your appointments and give you a sense of reassurance as you prepare for your baby.

Services and Screenings Included in Cheap Prenatal Care Plans

img-4.jpg

Many community clinics offer a bunch of services to help moms watch over their health without breaking the bank. They often have quick tests and scans that can bring some much-needed reassurance early on. Fun fact: many moms have shared how a free same-day blood test gave them fast answers and a sense of calm during a busy morning.

  • First-trimester blood test
  • Routine prenatal panels
  • Transabdominal ultrasound
  • Transvaginal ultrasound
  • 3D/4D scans

When you're at your prenatal visit, be sure to ask about all the free or low-cost screenings available. Don’t be shy about confirming if the clinic offers quick pregnancy blood tests and free same-day pregnancy confirmation. Also, check if the routine prenatal panels mentioned during your upcoming prenatal visit (https://womensconference.org?p=prenatal_visit) are part of your checkup. And why not ask about advanced imaging like 3D/4D scans? Knowing which tests are covered and any costs involved can help you plan your care so it meets both your health needs and your budget.

How to Search and Find Cheap Prenatal Care Near Me

img-5.jpg

Start by using your computer or phone to look for affordable prenatal care near you. Try searching on Google Maps with terms like "cheap prenatal care near me." It might sound simple, but many moms have found hidden gems this way. One mom even said she discovered her trusted care with just a few clicks. This method helps you learn about local centers and see ratings and reviews from other families.

Next, give your local health department or a nearby clinic a call. Ask if they offer sliding-scale fees and what services they provide. You could ask, "What are your appointment options for affordable checkups?" This can really clear things up, so you know what to expect. When you feel ready, book your first visit by choosing a time that works for you through the "prenatal care appointment" link (https://womensconference.org?p=prenatal_care_appointment).

Before you head out for your first appointment, make sure you have all your paperwork in order. Grab your proof of income, ID, and a document that shows where you live. Doing this ahead of time helps avoid any last-minute delays and keeps everything running smoothly.

Community Programs Offering Cheap Prenatal Care Near You

img-6.jpg

Federal and state programs offer many services to help pregnant moms. For example, WIC gives advice on healthy eating, helps with breastfeeding tips, and shows you where to get important checkups. And there are community prenatal classes and events by groups like Healthy Start and March of Dimes that bring families together in a warm, welcoming space. One mom shared, "I felt truly supported through every step of my pregnancy."

Local non-profit groups also host free prenatal classes, group visits, and parenting workshops. These programs aim to empower moms with useful tips and shared experiences. One mom said, "The free workshop not only taught me so much but also connected me with other caring families." It really feels comforting to learn and grow with others who understand.

County health offices pitch in too by offering free prenatal screening events and setting up support groups for expectant moms. These government-backed clinics make care more accessible and help families get ongoing advice. By reaching out to your local public health office, you can tap into community-supported services that boost both your health and confidence during pregnancy.

Final Words

In the action, the post showed you options like community health centers, Planned Parenthood clinics, and nonprofit facilities offering low-cost support. It explained payment and insurance plans that make care more accessible and covered the services you can expect with affordable prenatal plans.

We hope you feel empowered to search for cheap prenatal care near me and step forward confidently into nurturing and caring for your little one. Keep smiling and take charge of your health!

FAQ

Where can I find cheap prenatal care in California and Texas?

The affordable prenatal care in California and Texas is available at community health centers, Planned Parenthood clinics, and nonprofit facilities that use sliding-scale fees to fit your income.

Where can I find free prenatal care clinics near me?

The free prenatal care clinics near you include community health centers and nonprofit organizations that offer walk-in pregnancy examinations and sliding-scale services for those without insurance.

How much does prenatal care cost without insurance?

The cost of prenatal care without insurance varies by clinic, but many centers offer services at little to no charge, using sliding-scale fees based on your income and available charity programs.

What should I do if I’m pregnant and cannot afford care?

The advice for those who cannot afford care is to reach out to local health departments, community clinics, or government programs like Medicaid and CHIP, which offer low-cost or free prenatal services.

What payment options or insurance programs help cover pregnancy care?

The most affordable options include Medicaid, CHIP, and Health Insurance Marketplace plans with premium tax credits, all designed to lower the cost of prenatal care services for eligible expectant women.

What if I’m pregnant and have no insurance?

The guidance for having no insurance while pregnant is to explore local community health centers, nonprofit clinics, and charity programs that provide prenatal care on a sliding scale or at no charge.

Extending Reach: Strategic Insights into the Refueling Aircraft Market

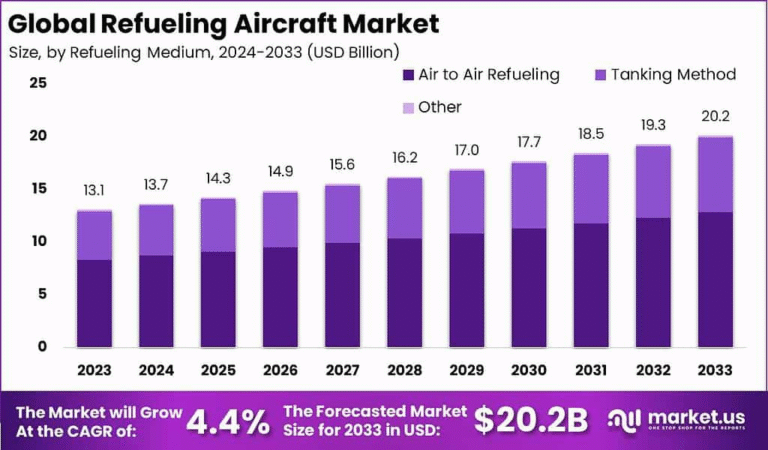
The Refueling Aircraft Market is valued at approximately USD 9.6 billion in 2024 and is projected to reach USD 14.8 billion by 2030, growing at a CAGR of 7.5%. Demand is driven by the growing need for extended mission duration, operational range, and air superiority across both military and commercial aviation. Modernization of air forces, increased international defense budgets, and geopolitical tensions are propelling procurement of advanced aerial refueling systems. Additionally, the integration of unmanned refueling capabilities and increased emphasis on joint-force operational strategies are further shaping demand in this evolving market landscape.

Key Takeaways

  • Market to reach USD 14.8 billion by 2030

  • CAGR of 7.5% between 2024 and 2030

  • Driven by increasing military deployment and extended-range missions

  • Advancements in autonomous and UAV-based refueling platforms

  • North America dominates due to strategic fleet upgrades

  • Surge in multi-role tanker aircraft acquisitions globally

  • Air-to-air refueling becoming crucial for long-haul unmanned flights

  • Dual-role aircrafts enhancing operational flexibility

  • Naval aviation operations driving carrier-based refueling aircraft demand

  • High procurement from Asia-Pacific and Middle East nations

Emerging Trends
Key trends include the development of autonomous aerial refueling drones, enabling force multiplication and persistent surveillance. There is a growing shift toward multi-role tanker aircraft, combining cargo, medevac, and refueling capabilities. Stealth-compatible refueling systems are being integrated for next-gen fighter jets. Advancements in boom and probe-and-drogue systems are enhancing interoperability across allied forces. Increased adoption of modular refueling pods allows retrofitting on cargo planes. Innovations in fuel efficiency and low-observable tech improve survivability and mission success. Data-linked refueling systems are being developed for synchronized, secure operations. Moreover, space refueling concepts are under research for future aerospace operations.

Use Cases

  • Military mid-air refueling to extend combat aircraft mission endurance

  • UAV refueling to support persistent intelligence, surveillance, and reconnaissance (ISR)

  • Strategic mobility for transporting troops and supplies over long distances

  • Carrier-based refueling operations supporting naval air power projection

  • Tactical refueling during multinational joint exercises and combat scenarios

  • Emergency refueling for aircraft returning from extended missions

  • Humanitarian and disaster relief support through long-range logistics flights

  • Testing and training applications for aircrew in extended mission environments

  • Force projection and deterrence missions in geopolitically tense regions

  • Aerial refueling of strategic bombers for global strike capability

Major Challenges
Challenges include the high capital and operational cost of refueling aircraft, limiting access for smaller air forces. Technological complexity in refueling systems, such as boom alignment and weather interference, poses safety concerns. Aging tanker fleets in several countries require costly upgrades or replacements. Limited interoperability between different aircraft platforms affects multinational missions. Environmental concerns over fuel emissions and operational noise are rising. Space constraints on aircraft carriers for larger refuelers affect deployment. Training and simulation for aerial refueling remain resource-intensive. Additionally, vulnerability to enemy radar and missiles limits deployment in contested airspace, raising survivability and mission-planning concerns.

Opportunities
Opportunities exist in developing next-gen, stealth-compatible tankers for advanced fighter jets. The rise of UAV-to-UAV refueling opens a new frontier for autonomous operations. Growing defense budgets in Asia-Pacific and Middle East present high procurement potential. Dual-role aircraft designs appeal to nations needing versatility. Partnerships with aerospace startups can drive innovation in modular refueling pods. Technological advancements in AI-assisted fuel delivery and flight path optimization enhance efficiency. Civilian long-haul aircraft refueling for disaster response and remote cargo missions is a growing niche. Retrofits of existing cargo aircraft with fuel modules offer cost-effective solutions. Space and near-space refueling programs hint at futuristic applications.

Key Players Analysis
Key players in the refueling aircraft market focus on producing multi-mission platforms combining cargo, medical evacuation, and refueling functions. They invest in stealth-compatible refueling technology, modular pod systems, and automation for enhanced safety and precision. Collaborations with defense forces enable co-development tailored to specific mission profiles. These firms are advancing UAV-based and autonomous refueling systems for future warfare needs. Emphasis is placed on aircraft interoperability, endurance, and fuel transfer accuracy. Through joint ventures, global expansions, and MRO services, they sustain operational readiness of large tanker fleets. Their innovations aim to reduce lifecycle costs and improve aerial refueling efficiency across domains.

Conclusion
The Refueling Aircraft Market plays a pivotal role in extending airpower and enhancing global mobility. As mission complexity and operational demands rise, the need for technologically advanced and interoperable refueling solutions becomes vital. While cost, vulnerability, and system integration present ongoing challenges, the market is buoyed by increasing defense spending, autonomous refueling developments, and dual-use platform innovations. With growing interest in UAVs, stealth operations, and space refueling research, the future of the market lies in adaptability, modularity, and global defense collaboration—positioning it as a strategic enabler in modern and next-generation aerial warfare.