Friday, October 9, 2026
Home Blog Page 122

Unmasking Innovation: Strategic Insights into the DeepFake AI Market

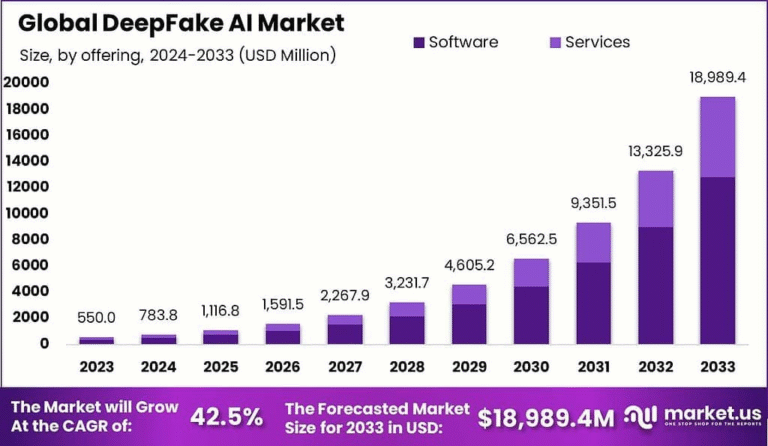
The DeepFake AI Market is estimated at USD 2.1 billion in 2024 and is projected to grow to USD 8.9 billion by 2030, registering a CAGR of 27.1%. The increasing sophistication of AI-generated synthetic media is driving demand across entertainment, marketing, gaming, and security sectors. While the technology presents opportunities for content creation and personalization, concerns over misinformation, fraud, and digital identity manipulation have heightened regulatory and ethical scrutiny. Enterprises and governments alike are investing in DeepFake detection tools, synthetic media regulation, and secure deployment strategies to mitigate risks while leveraging the innovation for immersive experiences.

Key Takeaways

  • Market to exceed USD 8.9 billion by 2030

  • CAGR of 27.1% between 2024–2030

  • Used in media, entertainment, gaming, and advertising

  • Rise in social engineering and political misinformation risks

  • Detection technologies gaining significant investment

  • Personalized AI avatars driving demand in digital marketing

  • Growing regulatory attention across U.S., EU, and Asia

  • Real-time DeepFake generation now accessible via cloud platforms

  • Content authenticity tools becoming standard in media workflows

  • Generative AI models improving realism of voice and video fakes

Emerging Trends
Emerging trends include the rise of real-time DeepFakes for virtual influencers and AI-generated customer service agents. Voice cloning and audio synthesis are expanding into podcasting and dubbing. The combination of DeepFakes with AR/VR is creating hyper-realistic metaverse experiences. AI-based watermarking and content authentication protocols are being developed to ensure transparency. There’s also growth in synthetic training data generation for AI model development. Face-swapping apps and text-to-video platforms are gaining consumer traction. Regulatory momentum is building around labeling synthetic content and penalizing malicious use. The fusion of GANs and diffusion models is pushing the realism boundary even further.

Use Cases

  • Film and entertainment using DeepFakes for de-aging and digital doubles

  • Marketing and advertising campaigns featuring AI-generated brand ambassadors

  • Gaming and avatars with personalized character rendering

  • Virtual influencers powered by DeepFake visuals and speech synthesis

  • Education and training simulations with AI-generated presenters

  • Speech cloning for voice-over, localization, and accessibility tools

  • Synthetic data generation for training facial recognition systems

  • Real-time video conferencing with AI-powered facial animation

  • Security and law enforcement for facial reconstruction and investigation

  • Satirical content and parody creation in media and comedy platforms

Major Challenges
The DeepFake AI market faces significant challenges including misuse for misinformation, identity theft, and fraud. The lack of legal frameworks globally complicates ethical usage boundaries. As DeepFake realism improves, detection becomes more difficult, placing strain on cybersecurity teams. There’s increasing public distrust of visual media, threatening journalistic integrity. DeepFakes can exacerbate political tensions, especially during election cycles. Data privacy issues arise when training on unauthorized images and voices. Tools for mass production are becoming widespread, raising accessibility risks. Balancing innovation with ethical standards is complex, and combating malicious content requires large-scale coordination among tech firms and regulators.

Opportunities
Opportunities lie in developing DeepFake detection software, especially for enterprises and law enforcement. Content creators can leverage DeepFake tools to reduce production costs and increase personalization. Healthcare and therapy benefit from virtual patient simulations and cognitive therapy tools. Language localization and automatic dubbing powered by DeepFake AI offer global content reach. In gaming, AI avatars offer immersive, dynamic character experiences. Synthetic actors and voice-overs can enhance e-learning platforms. The growth of the metaverse creates demand for realistic virtual identities. As transparency tools evolve, platforms offering authenticated synthetic content will find adoption in education, simulation, and creative arts.

Key Players Analysis
Key players in the DeepFake AI market focus on delivering high-fidelity visual and audio synthesis using advanced GANs, transformers, and diffusion models. They target industries like media, advertising, gaming, and education with customizable, scalable platforms. Some prioritize detection and forensics tools, assisting governments and enterprises in combating misuse. Innovation focuses on real-time DeepFake generation, voice cloning accuracy, and cross-platform integration. Partnerships with cloud and social platforms expand deployment capabilities. Leaders invest in ethics-by-design principles, watermarking, and content flagging. Balancing creative innovation with regulation, these firms navigate a complex landscape while enabling synthetic content creation at scale.

Conclusion
The DeepFake AI Market is a double-edged sword—blending creative potential with ethical dilemmas. As the technology matures, its role in media production, digital marketing, and virtual interactions will expand. However, concerns over authenticity, privacy, and security necessitate proactive governance, detection innovation, and public education. The market’s explosive growth underscores the need for responsible development and transparent use cases. With proper safeguards, DeepFake AI can revolutionize content creation, personalization, and simulation across industries—paving the way for a more interactive, AI-enhanced digital future.
 

Automating Accuracy: Strategic Insights into the AI in Enterprise Accounting Market

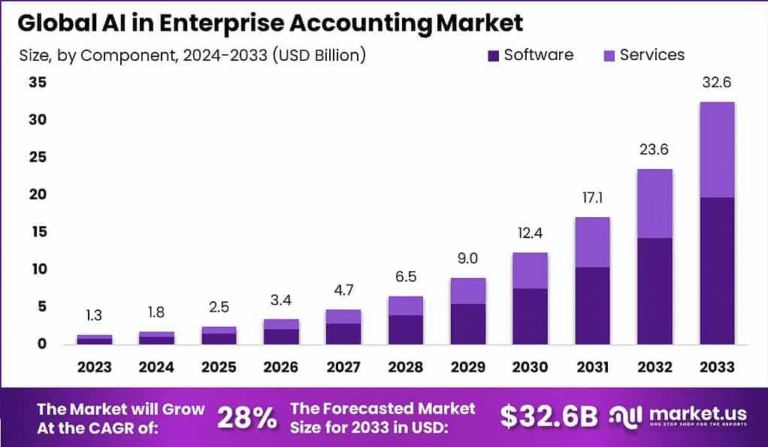
The AI in Enterprise Accounting Market is valued at approximately USD 3.4 billion in 2024 and is projected to reach USD 9.2 billion by 2030, growing at a CAGR of 17.6%. The growth is driven by the demand for real-time financial insights, automation of manual accounting tasks, and improved regulatory compliance. Enterprises are leveraging AI to streamline invoicing, audit processes, expense management, and financial forecasting. The integration of AI with ERP systems enhances accuracy and efficiency, significantly reducing human error. As finance departments evolve into strategic business units, AI is becoming essential in modernizing accounting operations.

Key Takeaways

  • Market to reach USD 9.2 billion by 2030

  • CAGR of 17.6% between 2024 and 2030

  • AI enhances accuracy in bookkeeping and compliance

  • Increased adoption in large enterprises and expanding into SMEs

  • Cloud-based accounting systems gaining strong traction

  • NLP used for automated document interpretation

  • AI improves fraud detection and internal audit efficiency

  • Real-time financial dashboards improving decision-making

  • APAC showing fastest adoption due to digital finance transformation

  • AI reduces operational costs and accelerates closing cycles

Emerging Trends
Emerging trends include AI-powered predictive analytics for real-time cash flow and revenue forecasting. Robotic Process Automation (RPA) is widely integrated with AI to automate repetitive accounting tasks like reconciliations and journal entries. Natural Language Processing (NLP) allows AI to extract insights from unstructured documents such as contracts and receipts. Blockchain integration enhances transparency and transaction validation. There’s a shift toward AI-driven continuous auditing and real-time risk assessment. Explainable AI (XAI) is gaining momentum to ensure trust and accountability in financial decisions. Additionally, AI chatbots are improving finance helpdesk services, vendor inquiries, and procurement support within accounting workflows.

Use Cases

  • Automated invoice processing using AI-based OCR and data extraction

  • Expense classification and fraud detection via machine learning models

  • Real-time revenue forecasting and cash flow management

  • AI-enabled audit trail monitoring to identify anomalies or policy violations

  • Chatbots for handling employee reimbursement queries

  • Tax compliance validation and error detection

  • Predictive modeling for budgeting and financial planning

  • Bank reconciliation automation using AI and RPA integration

  • Contract analysis and lease accounting with NLP tools

  • Automated accruals and closing entries at month-end or year-end

Major Challenges
The market faces challenges such as data privacy concerns, especially when handling sensitive financial data. Legacy system integration poses difficulties for organizations transitioning to AI-enabled platforms. There is a shortage of AI-skilled financial professionals who understand both technology and accounting principles. Change resistance among finance teams hinders digital adoption. High initial implementation costs may deter smaller firms. Compliance with varied regulatory standards across geographies adds complexity. Ensuring the accuracy of AI predictions in dynamic financial scenarios is still evolving. Additionally, concerns around auditability and transparency of AI-driven accounting decisions remain barriers to full-scale adoption.

Opportunities
Opportunities exist in the development of modular, AI-powered accounting tools tailored for specific business needs. SMEs present a high-growth segment as they adopt digital finance solutions. AI-driven ESG and sustainability reporting is an emerging area. Real-time AI dashboards for CFOs offer strategic insights beyond transactional accounting. Partnerships with ERP and cloud platforms can expand AI accounting services globally. Use of AI in compliance monitoring provides strong demand in highly regulated sectors like healthcare and banking. Additionally, finance shared service centers are automating back-office accounting using AI, offering cost reduction and scalability benefits. Vertical-specific AI modules also present niche market potential.

Key Players Analysis
Leading companies in the AI in enterprise accounting market offer comprehensive solutions that integrate seamlessly with ERP systems and cloud financial platforms. They emphasize automation, real-time analytics, and compliance tracking. These vendors invest in NLP, deep learning, and anomaly detection to improve the speed and reliability of accounting processes. They cater to both global enterprises and mid-sized firms with scalable solutions. Strategic partnerships with software giants and audit firms help expand their market presence. Innovation is focused on intelligent reconciliation engines, AI for tax analytics, and financial close automation. Continuous enhancements in UI/UX and AI transparency support user adoption.

Conclusion
AI in Enterprise Accounting is redefining the finance function from a transactional role to a strategic, data-driven decision hub. With strong market growth and increasing demand for speed, compliance, and efficiency, AI adoption is accelerating across finance departments globally. Despite integration and skill-related hurdles, the value proposition of cost savings, accuracy, and real-time insights is compelling. As AI technology matures, it will further empower CFOs and accounting professionals to drive strategic planning, risk management, and performance optimization, cementing its role as a critical enabler of digital finance transformation.


Empowering Insights: Strategic Analysis of the AI in Data Science Market

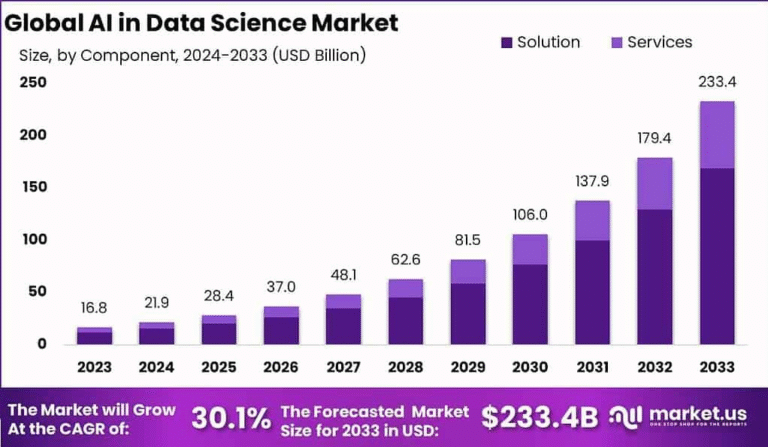
The AI in Data Science Market is valued at USD 22.7 billion in 2024 and is projected to surpass USD 61.3 billion by 2030, growing at a CAGR of 17.8%. The growing need for automated analytics, intelligent data discovery, and predictive modeling is fueling demand for AI-driven data science platforms across industries. Businesses increasingly rely on AI to process vast datasets, uncover hidden patterns, and accelerate decision-making. From healthcare and finance to retail and manufacturing, AI is transforming data science workflows, boosting productivity, and enabling real-time insights in a data-intensive digital economy.

Key Takeaways

  • Market to reach over USD 61.3 billion by 2030

  • 17.8% CAGR driven by demand for real-time analytics

  • AI automates feature engineering, model training, and validation

  • Cloud-based data science platforms seeing rapid adoption

  • BFSI and healthcare lead in AI-driven data projects

  • Generative AI accelerates data augmentation and simulation

  • Integration of NLP for unstructured data analysis is rising

  • AI enables hyper-personalization in marketing and retail

  • Data privacy and explainability tools gaining importance

  • North America dominates; APAC emerging rapidly

Emerging Trends
The market is shaped by the rise of AutoML platforms that automate complex data science tasks. Generative AI is being used to simulate data and create synthetic datasets for training. NLP is advancing to interpret unstructured data like text, audio, and video. AI-augmented BI tools are replacing static dashboards with dynamic insights. Federated learning is emerging to train models without data centralization, addressing privacy concerns. Multi-modal data integration, real-time processing via edge AI, and composable data platforms are gaining popularity. Ethics, fairness, and explainability in AI models are becoming essential features in enterprise-grade data science platforms.

Use Cases

  • Predictive maintenance in manufacturing using AI models on sensor data

  • Fraud detection in finance through anomaly detection algorithms

  • Patient outcome prediction in healthcare via AI-augmented diagnostics

  • Churn prediction and segmentation in telecom and e-commerce

  • Personalized marketing powered by AI-driven customer behavior analysis

  • Risk scoring and credit modeling using AI in BFSI

  • Supply chain optimization with AI-based demand forecasting

  • Energy usage prediction and grid balancing in utilities

  • Product recommendation engines in retail and media

  • Smart city planning using AI-powered spatial and environmental data

Major Challenges
The market faces key challenges such as data privacy and security concerns, particularly with sensitive datasets in finance and healthcare. Model interpretability remains limited, hindering trust in black-box AI solutions. A shortage of skilled professionals to manage AI-driven data projects slows implementation. Integration of AI tools with legacy IT systems is complex and costly. Data silos and lack of standardized formats hinder model training across platforms. High infrastructure costs for compute-intensive AI tasks can be prohibitive for SMEs. Bias in AI models due to skewed data poses ethical risks. Rapid algorithm evolution also necessitates continuous upskilling and system updates.

Opportunities
The market offers opportunities in developing low-code/no-code AI platforms that empower citizen data scientists. Edge computing presents new use cases for AI in remote, real-time environments. Government investments in digital infrastructure and AI R&D open public sector growth. Synthetic data generation supports model training where real data is limited. AI-as-a-service is gaining popularity among startups and SMEs. Custom AI models for sectors like precision agriculture, smart manufacturing, and telemedicine offer vertical growth. There’s rising demand for AI in ESG analytics and regulatory reporting. Partnerships between AI vendors and cloud providers can further accelerate data science innovation.

Key Players Analysis
Leading market participants offer end-to-end AI platforms that combine data ingestion, model development, and deployment tools. These companies focus on scalability, security, and automation, catering to enterprises across finance, retail, healthcare, and tech. They leverage cloud-native architectures and integrate with data lakes and warehouses for seamless operations. Emphasis is placed on explainable AI, regulatory compliance, and ethical AI governance. Key players also support multi-cloud environments and hybrid deployments. Strategic partnerships with consulting firms, hyperscalers, and universities strengthen their market positioning. Investment in AutoML, federated learning, and domain-specific AI models helps address diverse client needs across regions.

Conclusion
The AI in Data Science Market is revolutionizing how organizations harness and interpret data, enabling smarter, faster, and more reliable decision-making. As industries face exponential data growth, AI-driven platforms offer automation, agility, and actionable insights. While integration, talent gaps, and ethics remain concerns, the market’s robust trajectory is underpinned by technological advances and sector-wide digital transformation. With opportunities in edge AI, generative models, and low-code development, AI in data science will continue to be a key enabler of competitive advantage, shaping the future of analytics and intelligent enterprise operations across the globe.


Navigating the Future: Digital Radar Market Insights and Strategic Outlook

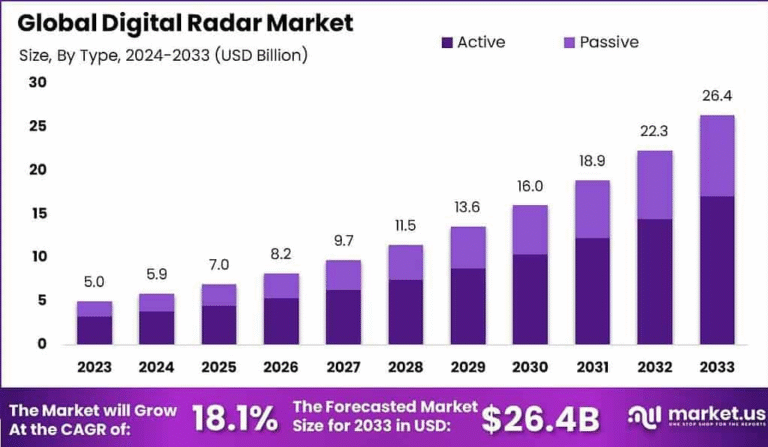
The global Digital Radar Market is poised for substantial growth, valued at approximately USD 7.5 billion in 2024 and projected to surpass USD 14.2 billion by 2030, expanding at a CAGR of 11.1%. This growth is driven by increasing demand for advanced surveillance, autonomous vehicles, and defense modernization. The surge in demand for real-time tracking, threat detection, and weather monitoring significantly impacts commercial and military sectors. With governments investing in smart defense systems and automotive sectors pushing for higher safety standards, the digital radar market is expected to witness a robust increase in adoption across applications.

Key Takeaways

  • Market size to exceed USD 14.2 billion by 2030

  • CAGR forecasted at 11.1% from 2024 to 2030

  • Automotive sector is a major adopter, driven by ADAS integration

  • Rising geopolitical tensions fueling military radar investments

  • Demand for 3D imaging and AI-powered radar systems is surging

  • Weather monitoring applications are growing, especially in disaster-prone regions

  • Integration with IoT and edge computing enhances radar capabilities

  • Shift from analog to digital systems improving signal accuracy

  • Significant uptake in space and drone-based radar technologies

  • Asia-Pacific region expected to witness the fastest growth

Emerging Trends
The digital radar market is undergoing transformation through AI-powered signal processing, edge computing integration, and the deployment of 5G-enabled radar systems. The adoption of millimeter-wave radars in autonomous driving and aviation is rapidly increasing. Quantum radar research and stealth detection innovations are also gaining attention. In defense, digital beamforming and multifunction radars are being explored for cost efficiency and versatility. Additionally, radar-on-chip (RoC) and solid-state radar systems are emerging as compact, reliable solutions for commercial use. The convergence of radar with LiDAR and camera systems for sensor fusion is another key trend reshaping safety in vehicles and smart infrastructure.

Use Cases

  • Autonomous vehicles using radar for lane assist and collision avoidance

  • Military applications for surveillance, missile guidance, and threat detection

  • Air traffic control and airport security radar systems

  • Maritime navigation and vessel tracking in commercial shipping

  • Weather forecasting and natural disaster early warning systems

  • Law enforcement applications such as speed detection and monitoring

  • Railways for obstacle detection and train control systems

  • Space research for terrain mapping and spacecraft navigation

  • Industrial automation for object tracking in factories

  • UAVs/drones for real-time object detection and route planning

Major Challenges
The digital radar market faces challenges such as high development and integration costs, spectrum congestion, and signal interference from increasing electronic clutter. Technical complexities in miniaturizing radar systems without compromising range and accuracy also pose barriers. Cybersecurity vulnerabilities in radar communication links, especially in military and aviation sectors, are growing concerns. Compatibility issues with legacy analog systems and stringent global regulatory frameworks hinder deployment in some regions. Furthermore, competition from emerging sensor technologies like LiDAR and optical systems is pressuring radar manufacturers to innovate faster and maintain cost efficiency without sacrificing performance.

Opportunities
Rising demand for autonomous mobility and smart city infrastructure presents major opportunities for digital radar adoption. Emerging markets in Asia-Pacific and Latin America offer significant untapped potential due to increasing defense budgets and urbanization. Integration of AI and machine learning with radar data can unlock advanced analytics for various applications. There’s growing interest in radar use in space exploration, drones, and healthcare monitoring. Development of low-power, compact radar modules expands possibilities in consumer electronics. Public safety, environmental monitoring, and infrastructure resilience are new avenues for digital radar deployments as governments invest in technology-driven public service enhancements.

Key Players Analysis
Leading companies in the digital radar market are focusing on R&D for AI-based radar systems, forming strategic alliances with automotive and defense firms, and expanding their portfolios through acquisitions. These players emphasize miniaturization, solid-state technologies, and high-resolution imaging radar. They maintain dominance by customizing radar systems for specific verticals like weather, aerospace, and industrial automation. Emphasis on cost reduction, integration flexibility, and improved signal processing positions them strongly in both government contracts and commercial supply chains. Their presence in global markets is reinforced through innovation labs and regional manufacturing units catering to growing local demands.

Conclusion
The digital radar market is on an accelerated trajectory fueled by innovation, strategic demand from defense and automotive sectors, and the need for real-time precision tracking. With evolving trends like AI integration, edge computing, and multifunctional radar modules, the market is positioned for transformative growth. While challenges around cost, complexity, and competition remain, expanding opportunities in mobility, security, and infrastructure modernization underscore the market’s resilience and promise in shaping future technologies.


ADC Payload / Warheads Market Strengthens with Strategic Collaborations and Licensing Agreements

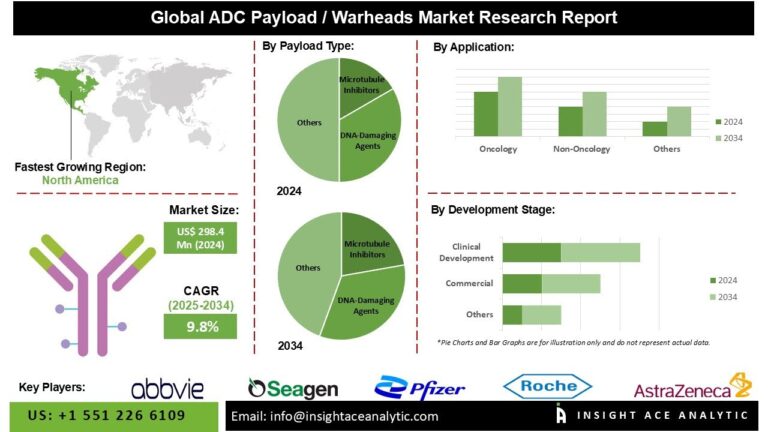
The ADC Payload / Warheads Market is estimated to reach over USD 736.7 Mn by the year 2034, exhibiting a CAGR of 9.8% during the forecast period of 2025-2034.  

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/2990

 Antibody-drug conjugates (ADCs) represent a rapidly evolving class of targeted therapeutics, offering significant potential across diverse disease areas, most notably in oncology. Technological advancements in ADC design have enabled the precise conjugation of monoclonal antibodies with highly potent cytotoxic agents through the use of next-generation chemical linkers. These innovations have improved the selectivity, stability, and therapeutic efficacy of ADCs, reinforcing their role in modern precision medicine.

The development and commercial-scale manufacturing of ADCs are highly complex, requiring specialized facilities, expert personnel, and stringent quality controls. The synthesis of cytotoxic payloads involves intricate multi-step chemical processes, advanced purification techniques, and comprehensive analytical validation, all of which must be conducted under tightly regulated conditions to ensure safety and consistency. Given these challenges, many ADC developers engage contract manufacturing organizations (CMOs) with the requisite infrastructure, technical expertise, and regulatory compliance capabilities. These strategic collaborations support efficient scale-up, streamline regulatory processes, and maintain product integrity throughout the manufacturing lifecycle.

While oncology remains the primary focus of ADC development, ongoing research is expanding their application to non-oncologic indications, including autoimmune diseases and infectious disorders. This therapeutic expansion is driven by the exploration of novel payload classes such as topoisomerase inhibitors, DNA-damaging agents, protein degraders, and immunomodulatory compounds, which are designed to enhance efficacy and overcome resistance mechanisms.

Simultaneously, continuous improvements in linker chemistry have significantly enhanced the pharmacokinetic profiles and safety of ADCs by enabling more controlled and selective payload release at disease sites, thereby minimizing off-target effects and systemic toxicity. These advancements have contributed to the growing demand for specialized payload manufacturing, fostering a competitive landscape among suppliers with advanced technological capabilities and regulatory expertise.

ADCs are also being integrated into combination treatment strategies alongside immune checkpoint inhibitors and other immunotherapies, further amplifying their role in personalized medicine. As a result, ADCs are gaining prominence not only as standalone therapies but also as components of broader, patient-specific treatment regimens. The increasing clinical success, regulatory approvals, and commercial interest in ADCs are expected to drive continued innovation, investment, and growth in this dynamic segment of the biopharmaceutical industry.

List of Prominent Players in the ADC Payload / Warheads Market:

  •       Seagen
  •       Takeda
  •       Roche
  •       Astellas
  •       AbbVie
  •       Pfizer
  •       AstraZeneca
  •       Gilead Sciences
  •       Synaffix
  •       NJ Bio
  •       Levena Biopharma
  •       Abzena
  •       MabPlex
  •       STA Pharmaceutical
  •       Mersana Therapeutics

Market Dynamics:

Drivers:

The global market for ADC payloads and warheads is experiencing strong growth, primarily driven by the increasing prevalence of various cancers, including breast, lung, and hematological malignancies. This growing oncology burden is accelerating the demand for targeted therapies that offer high efficacy with reduced systemic toxicity. Antibody-drug conjugates (ADCs) address this need by enabling the selective delivery of highly potent cytotoxic agents directly to cancer cells, thereby minimizing damage to healthy tissue. This mechanism of action supports the broader movement toward personalized oncology, wherein treatments are tailored based on individual tumor biomarkers.

Further contributing to market expansion are significant advancements in linker technologies and payload engineering. These innovations have improved the pharmacokinetics, tumor selectivity, and therapeutic index of ADCs, leading to better clinical outcomes and wider adoption in oncology treatment protocols. As biopharmaceutical companies continue to invest in next-generation payload classes—including DNA-damaging agents, topoisomerase inhibitors, and novel protein degraders—the market is poised for continued technological evolution and therapeutic diversification. 

Challenges:

Despite these favorable developments, the ADC payload and warhead segment faces considerable challenges. The development and manufacturing of ADCs are inherently complex, requiring the precise integration of monoclonal antibodies, cleavable or non-cleavable linkers, and cytotoxic warheads. Producing these components—especially the highly potent payloads—necessitates specialized containment facilities, advanced purification techniques, and rigorous safety and quality protocols. The high cost of infrastructure, combined with technical barriers and regulatory scrutiny, can constrain scalability and prolong development timelines. These challenges often result in extended time-to-market and increased capital expenditure for drug developers. 

Regional Trends:

North America currently holds the largest share of the global ADC payload and warheads market and is expected to maintain its leading position over the forecast period. The region’s dominance is supported by a well-established biopharmaceutical sector, advanced healthcare infrastructure, and a favorable regulatory framework led by the U.S. Food and Drug Administration (FDA), which promotes the development and approval of novel ADC therapies. Additionally, North America benefits from a high concentration of industry-academic partnerships and robust clinical trial activity that continues to drive innovation and commercialization.

Europe, on the other hand, is emerging as the fastest-growing regional market. This growth is underpinned by increased public and private investment in oncology R&D, expansion of academic-industry collaborations, and a growing number of clinical trials, particularly in key markets such as Germany, the United Kingdom, Switzerland, and France. These factors are positioning Europe as a critical hub for ADC research and development, contributing to the global momentum of the payload and warhead segment.

Recent Developments:

  •   In Oct 2024, Synaffix B.V, and Lonza company, aimed at bringing its clinical-stage platform technology for creating antibody-drug conjugates (ADCs) with the best-in-class therapeutic index to the market, today revealed that it has granted BigHat Biosciences, Inc. (“BigHat”) a license for its ADC technology.  For the creation of a new ADC pipeline program, BigHat will integrate Synaffix technology with their top-tier ML antibody design platform.
  •   In Dec 2024, Gilead Sciences, Inc. and Tubulis, said that they have signed a license and exclusive option to find and create an antibody-drug conjugate (ADC) that targets solid tumors.

Segmentation of ADC Payload / Warheads Market.

Global ADC Payload / Warheads Market – By Payload Type

  •   Microtubule Inhibitors
  •   DNA-Damaging Agents
  •   Topoisomerase Inhibitors
  •   Other Payloads

Global ADC Payload / Warheads Market – By Application

  •   Oncology
  •   Non-Oncology (Emerging)

Global ADC Payload / Warheads Market – By Development Stage

  •   Clinical Development
  •   Phase I, II, III trials Payloads for pipeline ADCs.
  •   Commercial

Global ADC Payload / Warheads Market – By Region

North America-

  •   The US
  •   Canada

Europe-

  •   Germany
  •   The UK
  •   France
  •   Italy
  •   Spain
  •   Rest of Europe

Asia-Pacific-

  •   China
  •   Japan
  •   India
  •   South Korea
  •   Southeast Asia
  •   Rest of Asia Pacific

Latin America-

  •   Brazil
  •   Argentina
  •   Mexico
  •   Rest of Latin America

 Middle East & Africa-

  •   GCC Countries
  •   South Africa
  •   Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Artificial Intelligence (AI) in Packaging Design Market Grows on Back of Computer Vision and Generative Design Tools

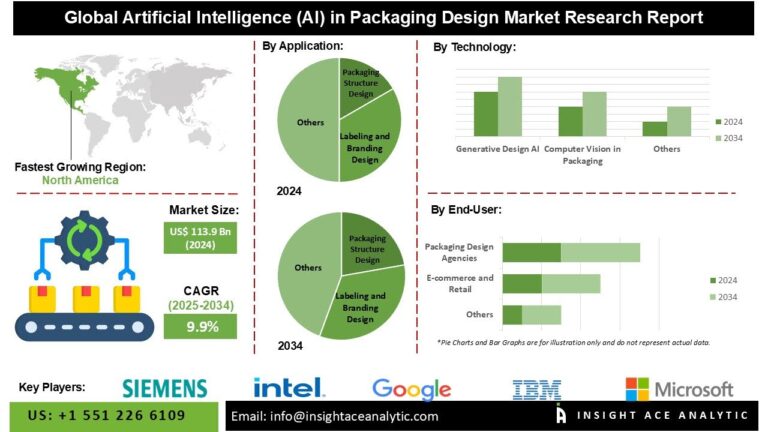
According to the latest research by InsightAce Analytic, the Artificial Intelligence (AI) in Packaging Design Market is valued at  USD 113.9 Bn in 2024 , and it is expected to reach  USD 284.0 Bn by the year 2034, with a CAGR of 9.9% during the forecast period of 2025-2034.

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/2994 

Artificial Intelligence (AI) is playing an increasingly pivotal role in packaging design, leveraging technologies such as machine learning (ML), computer vision, and data analytics to enhance the efficiency, sustainability, and functionality of packaging solutions. AI enables companies to automate complex design workflows, predict consumer preferences, optimize raw material usage, personalize product presentation, and ensure rigorous quality control—all while accelerating time-to-market.

Key applications include AI-assisted product design and prototyping, smart labeling that incorporates dynamic data (e.g., freshness indicators or QR-based traceability), and automated visual inspection systems that detect defects with high precision. These innovations have significantly improved productivity, lowered operational costs, and enhanced the quality and consistency of packaging across industries such as food and beverage, cosmetics, e-commerce, and logistics.

The AI-driven packaging design market is experiencing strong growth, propelled by rising consumer expectations for smarter, more sustainable packaging and heightened industry demand for cost-effective and adaptive solutions. Sectors such as pharmaceuticals, consumer electronics, and fast-moving consumer goods (FMCG) are increasingly investing in intelligent packaging systems to meet regulatory requirements, improve user experience, and differentiate their products in competitive markets.

With continued advancements in AI algorithms, 3D modeling, and sensor integration, the packaging industry is set to undergo further transformation—moving toward hyper-customized, responsive, and environmentally conscious packaging ecosystems.

List of Prominent Players in the Artificial Intelligence (AI) in Packaging Design Market:

  •   Microsoft Corporation
  •   Amazon Web Services (AWS)
  •   IBM Corporation
  •   Siemens AG
  •   Oracle Corporation
  •   Adobe Inc.
  •   Dassault Systèmes
  •   ABB Group
  •   Google LLC
  •   SAP SE
  •   NVIDIA Corporation
  •   Intel Corporation
  •   UST Global
  •   Esko (a Danaher company)

Market Dynamics: 

Drivers:

One of the primary growth drivers in the AI-enabled packaging design market is the technology’s ability to promote sustainability and reduce material waste. By leveraging machine learning and advanced data analytics, AI systems can evaluate product characteristics—such as shape, weight, fragility, and shipping conditions—to create packaging solutions that use minimal material without compromising protection. These data-driven designs contribute to lower packaging waste, reduced carbon footprints, and enhanced supply chain efficiency. Additionally, AI enhances operational sustainability by optimizing production line performance in real time, identifying inefficiencies, and minimizing energy consumption. These capabilities align closely with growing consumer demand for environmentally responsible products and help companies meet regulatory and corporate sustainability goals—ultimately delivering both environmental and economic value. 

Challenges:

Despite its transformative potential, the widespread adoption of AI in packaging design faces several challenges. High upfront investment costs—associated with software, hardware, and infrastructure upgrades—pose a financial barrier for small and mid-sized enterprises. Furthermore, integrating AI into existing design and production systems can be technically complex and may disrupt current workflows. The lack of in-house expertise and the perceived difficulty of implementation further contribute to organizational reluctance. Additionally, limited awareness of AI’s practical benefits within the packaging industry, particularly among traditional manufacturers, has slowed broader adoption and hindered market scalability. 

Regional Trends:

North America is anticipated to maintain its leadership position in the global AI-driven packaging design market, supported by its strong technological infrastructure, a high concentration of early adopters, and the presence of major technology providers and packaging manufacturers. Companies in the region are actively investing in AI solutions to improve design precision, reduce operational costs, and enhance customer engagement through intelligent packaging.

Europe, on the other hand, is expected to witness the highest growth rate during the forecast period. The region’s strong regulatory push for sustainable packaging—alongside innovation-focused policies such as the European Green Deal—is encouraging businesses to adopt AI technologies that support environmental goals. In particular, the pharmaceutical and food and beverage sectors are investing heavily in AI-driven packaging solutions to meet evolving safety, traceability, and consumer transparency requirements. 

Segmentation of Artificial Intelligence (AI) in Packaging Design Market-

By Application-

  • Packaging Structure Design
  • Packaging Functionalities Optimization
  • Labeling and Branding Design
  • Sustainability and Eco-friendly Packaging

By Industry vertical-

  • Food and Beverage
  • Consumer Electronics
  • Healthcare and Pharmaceuticals
  • Personal Care and Beauty

By Technology-

  • Generative Design AI
  • Natural Language Processing (NLP) for Packaging
  • Computer Vision in Packaging
  • AI-powered Simulation and Testing

By End-User-

  • E-commerce and Retail
  • Packaging Design Agencies
  • Manufacturers and Packaging Companies

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Automotive Circular Economy Market Surges as EV Growth Fuels Battery Repurposing and Resource Recovery

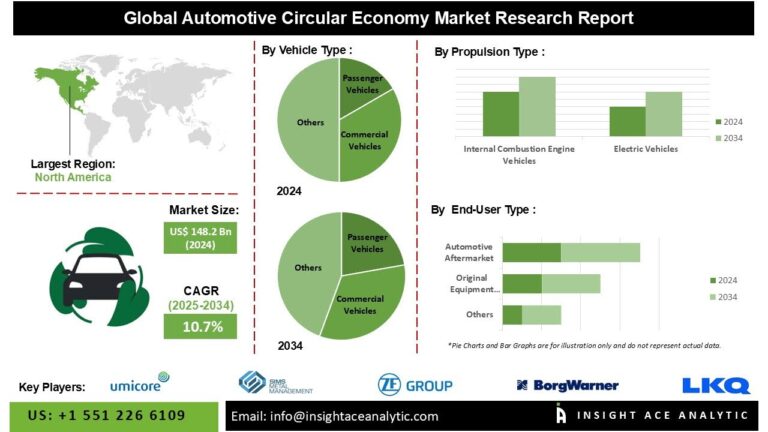
According to the latest research by InsightAce Analytic, the Automotive Circular Economy Market is valued at USD 148.2 Bn in 2024, and it is expected to reach USD 398.3 Bn by the year 2034 , with a CAGR of 10.7%  during the forecast period of 2025-2034.

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/2997 

The automotive circular economy represents a strategic and sustainable industrial model focused on extending the value and lifecycle of materials, components, and vehicles within the automotive sector. This approach encompasses a range of practices—including reuse, remanufacturing, recycling, and life cycle extension—that aim to reduce waste, lower carbon emissions, and limit the dependence on virgin raw materials. For example, repurposing key components such as electronic systems, engines, and transmissions not only delivers cost efficiencies but also substantially mitigates the environmental impact of vehicle production and end-of-life management.

The growing focus on sustainability and resource efficiency across the automotive value chain has elevated the circular economy as a key pillar of industry transformation. By embedding circularity into design, manufacturing, and after-market operations, automotive companies can drive innovation, improve competitiveness, and build more resilient and transparent supply chains. These initiatives also support broader corporate objectives related to regulatory compliance, operational optimization, and environmental stewardship.

Market expansion is being driven by a combination of regulatory pressures, including strict emissions and waste reduction mandates, along with increasing organizational commitments to carbon neutrality. In parallel, consumer preferences are shifting toward sustainable vehicles and responsibly sourced components. Additionally, circular production models offer significant cost-saving opportunities, further incentivizing adoption across original equipment manufacturers (OEMs), suppliers, and aftermarket service providers. Together, these dynamics highlight the strategic importance of circular economy integration in shaping the future of automotive manufacturing and supply chain practices. 

List of Prominent Players in the Automotive Circular Economy Market:

  •   Umicore
  •   ZF Friedrichshafen AG
  •   LKQ Corporation
  •   BorgWarner Inc.
  •   Valeo
  •   Sims Metal (Sims Limited)
  •   Copart Inc.
  •   IAA Holdings, LLC.
  •   RB Global
  •   BMW Group
  •   TOYOTA MOTOR CORPORATION
  •   Renault Group
  •   Aptiv.
  •   Redwood Materials Inc.
  •   Marelli Holdings Co., Ltd.
  •   Bosch GmbH

Market Dynamics

Drivers:

The automotive circular economy is experiencing accelerated growth, largely fueled by the rapid expansion of the electric vehicle (EV) market. A key driver is the opportunity to repurpose EV batteries, which typically retain 70–80% of their original capacity after completing their primary automotive function. These used batteries are increasingly being deployed in secondary applications, including stationary energy storage systems for grid, industrial, and residential use. This not only helps address environmental concerns related to battery waste but also conserves critical raw materials and offers a cost-efficient solution for the growing energy storage demand. As global EV adoption rises, the volume of end-of-life batteries is expected to increase significantly by 2030, unlocking substantial commercial opportunities across multiple sectors. 

Challenges:

Despite its potential, the integration of circular economy principles into the automotive industry faces notable hurdles. One major challenge is the complexity of the global automotive supply chain, which spans multiple regions and involves numerous stakeholders, making the recovery and traceability of components—especially high-tech or hazardous materials—difficult to manage. Additionally, infrastructure limitations in many regions, particularly in emerging markets, hinder the development of efficient recycling, remanufacturing, and reverse logistics systems. These barriers restrict the sector’s ability to scale circular initiatives effectively and highlight the need for investment in technological capabilities and regulatory alignment to support end-of-life vehicle management. 

Regional Trends:

North America is expected to maintain a strong position in the automotive circular economy market, supported by substantial investments in sustainable technologies, a favorable regulatory framework, and the proactive involvement of key industry players. The United States and Canada are advancing initiatives in vehicle recycling, remanufacturing, and battery reuse, reflecting a broader shift toward sustainable mobility solutions. In contrast, Europe is projected to experience the highest growth rate during the forecast period. Countries such as Germany, France, the United Kingdom, and Italy are leading the charge due to their well-established automotive sectors and strong policy commitments to environmental sustainability. Prominent market participants, including LKQ Corporation, BorgWarner, ZF Friedrichshafen AG, and Umicore, are actively engaging in product innovation, strategic alliances, and geographic expansion to strengthen their foothold and capitalize on emerging circular economy opportunities. 

Recent Development:

  • February 2024: Madayn and Copart, Inc. Middle East established a strategic alliance in Oman to tackle the problem of abandoned cars in industrial areas. By locating and retrieving abandoned cars for auction and guaranteeing their appropriate disposal and reuse to promote environmental sustainability.
  • August 2023: Uni-Select acquired by LKQ Corporation. This transaction increased the footprint of LKQ Corporation in the automobile aftermarket sector. This acquisition improved LKQ Corporation’s standing in the automotive circular economy, particularly in North America and the United Kingdom, by expanding its network.

Segmentation of Automotive Circular Economy Market-

By Vehicle Type-

  • Passenger Vehicles
  • Commercial Vehicles
  • Light Commercial Vehicles
    • Trucks
    • Buses

By Propulsion Type-

  • Internal Combustion Engine Vehicles
  • Electric Vehicles
    • Hybrid Electric Vehicles
    • Plug-In Hybrid Electric Vehicles
    • Battery Electric Vehicles

By Process Type –

  • Recycled Products
  • Remanufactured Products
  • Refurbished Products
  • Reused Products

By Component Type-

  • Battery
  • Tire
  • Polymers
  • Body Parts
  • Brakes and Suspensions
  • Others

By End-User-

  • Original Equipment Manufacturers (OEMs)
  • Automotive Aftermarket
  • Others

By Region-

North America-

  •       The US
  •       Canada
  •       Mexico

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.

Elevating Efficiency: Strategic Insights into the Aviation Cloud Market

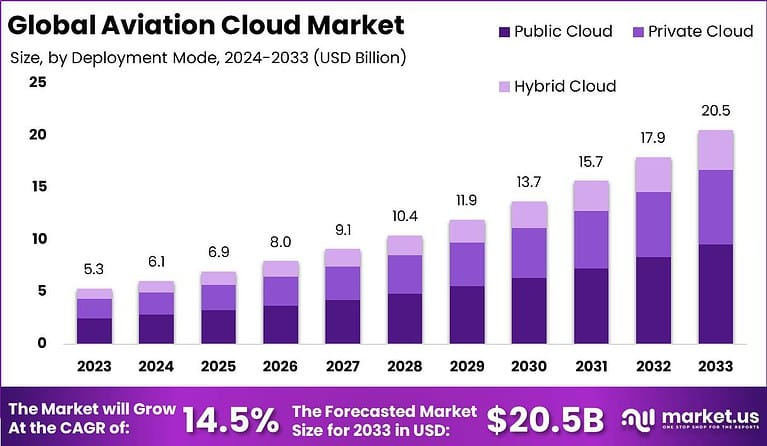
The global Aviation Cloud Market is valued at approximately USD 6.8 billion in 2024 and is projected to reach over USD 14.5 billion by 2030, growing at a CAGR of 13.1%. Rising demand for real-time data, improved flight operations, and digital transformation initiatives across the aviation sector are driving adoption. Cloud platforms are enabling airlines, airports, and MRO providers to enhance efficiency, reduce operational costs, and improve customer experiences. As aviation recovers post-pandemic and air traffic surges, scalable and secure cloud solutions are becoming essential to support automation, analytics, and sustainable growth in global air travel.

Key Takeaways

  • Market expected to surpass USD 14.5 billion by 2030

  • CAGR of 13.1% from 2024 to 2030

  • Driven by digitization and operational efficiency needs

  • Airlines adopting cloud for predictive maintenance and scheduling

  • Airports using cloud for real-time passenger and baggage tracking

  • Increased adoption of SaaS and IaaS in aviation operations

  • North America leads due to tech maturity and airport modernization

  • MROs leveraging cloud for inventory and supply chain visibility

  • Cloud enables integrated systems across departments and geographies

  • Cybersecurity and compliance becoming top priorities in aviation IT

Emerging Trends
Key trends shaping the aviation cloud market include integration of AI and IoT with cloud platforms to support real-time aircraft monitoring and predictive analytics. Airlines are adopting cloud-native mobile apps for flight crew communication and customer service enhancements. Hybrid and multi-cloud deployments are rising to improve system resilience and regulatory compliance. Use of cloud for biometric passenger verification and automated check-ins is expanding. Cloud-based digital twins are gaining popularity for simulating flight operations and maintenance. Blockchain integration for secure data sharing in aircraft leasing and supply chains is also emerging. Sustainability-focused cloud analytics help monitor and reduce carbon emissions.

Use Cases

  • Cloud-based flight planning and crew management systems

  • Real-time baggage tracking and airport passenger flow analytics

  • Predictive aircraft maintenance using cloud-hosted AI models

  • In-flight connectivity and entertainment management via cloud

  • Aviation training platforms using cloud-based simulators

  • MROs using cloud to manage parts inventory and logistics

  • Aviation cybersecurity systems with cloud-based threat monitoring

  • Airline CRM systems hosted on cloud for personalized services

  • Compliance tracking and reporting with cloud-based dashboards

  • Drone traffic management and airspace coordination using cloud

Major Challenges
Challenges include data security concerns due to the sensitive nature of flight and passenger data, making cybersecurity a top priority. Regulatory complexities across countries hinder seamless global cloud adoption. Legacy systems in aviation infrastructure make cloud integration technically difficult. Downtime or latency issues in mission-critical operations can impact safety and efficiency. High initial investments and long ROI cycles discourage smaller carriers. There’s also a limited availability of aviation-specific cloud expertise. Vendor lock-in risks and lack of interoperability across platforms limit flexibility. Moreover, ensuring real-time data access in remote or airborne environments remains a significant operational challenge.

Opportunities
The aviation cloud market offers immense opportunities in digital transformation for airlines, airports, and aviation authorities. Emerging markets in Asia-Pacific and the Middle East are investing in smart airports and offer strong growth prospects. Sustainability and emissions tracking tools hosted on the cloud are in rising demand. There is growing opportunity in offering scalable aviation SaaS solutions to small and mid-sized carriers. AI and ML-based predictive systems can reduce delays and improve customer satisfaction. Governments’ focus on air traffic modernization and integration of urban air mobility (UAM) also opens new use cases. Partnerships with aerospace firms for cloud innovation are expanding.

Key Players Analysis
Leading players in the aviation cloud space focus on building secure, scalable, and aviation-specific cloud platforms. They invest in AI, IoT, and edge computing integration to deliver real-time insights for operations, safety, and customer service. These companies collaborate closely with airports, airlines, and MROs to customize solutions that improve turnaround times and operational efficiency. Emphasis is placed on compliance with aviation regulations and cybersecurity standards. Their offerings span SaaS for airline operations, PaaS for development environments, and IaaS for infrastructure support. By forming strategic alliances and global cloud partnerships, they expand regional presence and drive aviation sector modernization.

Conclusion
The Aviation Cloud Market is set to transform the global aviation industry by enabling smarter, safer, and more efficient operations. As air traffic grows and digital demands increase, cloud technologies offer the agility and scalability necessary to adapt. While integration and security challenges persist, the adoption of AI, predictive analytics, and real-time connectivity is creating resilient, passenger-centric aviation ecosystems. With growing investment in digital airports and smart flight systems, aviation cloud platforms will become central to achieving sustainability, competitiveness, and innovation across commercial and defense aviation sectors.


Streamlining Transactions: Strategic Analysis of the Payment Service Provider Market

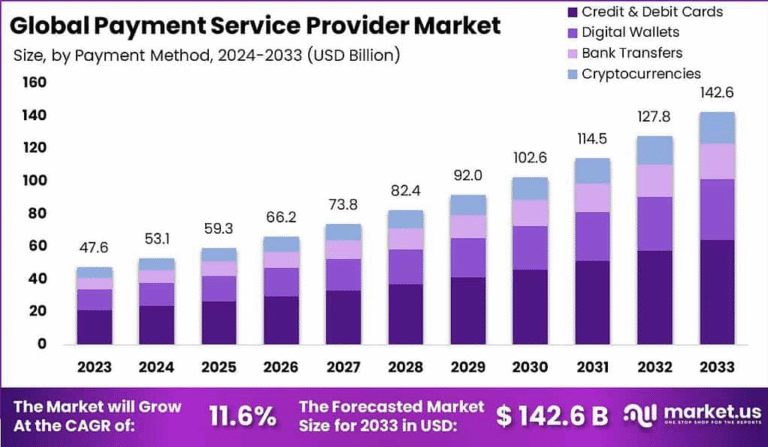
The global Payment Service Provider (PSP) market is valued at approximately USD 45.8 billion in 2024 and is projected to surpass USD 92.7 billion by 2030, growing at a CAGR of 12.4%. This growth is driven by rising e-commerce penetration, digital banking, and contactless payment trends. The demand for seamless, secure, and real-time payment experiences is reshaping how consumers and businesses transact. PSPs are central to this transformation, offering integrated solutions for online, in-store, and mobile payments. Rapid digitization across sectors such as retail, travel, education, and healthcare is propelling the need for scalable payment platforms.

Key Takeaways

  • Market expected to reach USD 92.7 billion by 2030

  • CAGR projected at 12.4% from 2024 to 2030

  • Growth driven by online commerce and digital wallets

  • Mobile-first solutions gaining dominance in emerging markets

  • Increasing demand for fraud prevention and compliance tools

  • SMEs adopting PSPs for global reach and low-cost processing

  • Embedded finance and API-based services on the rise

  • Contactless payments seeing rapid consumer adoption

  • Real-time transaction capabilities becoming standard

  • Regulatory frameworks pushing for transparency and security

Emerging Trends
The PSP market is undergoing rapid evolution with key trends like embedded payments in apps, API-first payment infrastructure, and blockchain-enabled payment rails. Buy Now Pay Later (BNPL) integration and cross-border transaction support are gaining popularity. AI-driven fraud detection and KYC automation enhance trust and compliance. There is rising interest in white-label PSP platforms and merchant-branded checkout solutions. Digital currency and CBDC integrations are being explored for next-gen PSP capabilities. Subscription billing and smart invoicing tools are being added for B2B scalability. Voice-assisted and biometric-based authentication are emerging for faster, frictionless customer experiences in both digital and physical retail environments.

Use Cases

  • E-commerce platforms integrating PSPs for seamless checkout and fraud protection

  • Subscription-based businesses using recurring billing and invoicing tools

  • Physical retailers leveraging point-of-sale systems with digital wallet support

  • Marketplaces enabling vendor payouts through multi-currency PSP solutions

  • Ride-sharing and food delivery apps using real-time transaction processing

  • Cross-border B2B firms adopting PSPs for global currency acceptance

  • Non-profits utilizing PSPs for secure online donations and compliance tracking

  • Education platforms enabling fee collection through mobile PSP apps

  • Healthcare providers offering contactless billing and insurance integration

  • Gig economy platforms using PSPs for fast, automated worker payments

Major Challenges
The PSP market faces challenges such as increasing transaction fraud and cybersecurity threats, requiring constant innovation in fraud prevention tools. Regulatory uncertainty across jurisdictions hampers cross-border PSP operations. High competition and pricing pressures limit profit margins, especially among smaller providers. Integration complexity with legacy financial systems poses technical hurdles. Consumer privacy concerns and data localization laws complicate compliance. The lack of financial inclusion in some regions creates barriers to adoption. Scalability issues for high-volume merchants and latency in real-time payments also remain concerns. Additionally, disruptions in digital infrastructure or service downtime can significantly impact user trust and revenue flows.

Opportunities
Growing demand for digital-first banking and financial services opens new avenues for PSPs in embedded finance. Expansion into underserved markets with mobile-friendly payment solutions presents vast potential. Integration of AI/ML to improve transaction security and personalize user experience offers significant value. There’s opportunity in building sector-specific PSPs for industries like education, health, and logistics. Governments’ push for cashless economies and fintech-friendly regulations further accelerates market growth. Partnerships with e-commerce giants and banks can enable broader market reach. Cloud-native platforms offering instant scalability are in demand. As businesses prioritize customer-centric models, PSPs offering customizable, omnichannel solutions are well-positioned for long-term success.

Key Players Analysis
Leading players in the PSP market are focusing on delivering unified, omnichannel solutions that integrate in-store, mobile, and online payments. They prioritize scalability, API accessibility, and enhanced security features such as tokenization and biometric verification. These providers are expanding into high-growth regions through strategic alliances with banks, fintechs, and marketplaces. Investment in AI and analytics enhances their fraud detection and customer insight capabilities. Subscription-based pricing and modular service offerings make them accessible to SMEs and large enterprises alike. Providers also emphasize regulatory compliance, offering tools for AML, PCI DSS, and GDPR adherence, ensuring trust across sectors and geographies.

Conclusion
The Payment Service Provider market stands at the forefront of digital transformation, driving seamless, secure, and scalable transactions across the global economy. As businesses and consumers increasingly demand convenience, speed, and security, PSPs are becoming vital enablers of commerce. Though the market faces challenges in regulation, competition, and security, the opportunities in embedded finance, AI integration, and global expansion remain strong. With continuous innovation and strategic partnerships, PSPs will play a pivotal role in shaping the future of payments, empowering enterprises and end-users in an increasingly connected and cashless world.


Powering Digital Engagement: Strategic Insights into the Social Media Management Market

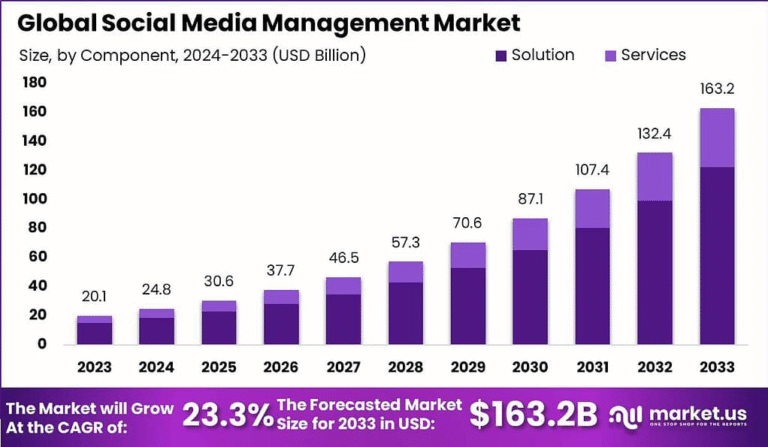
The global Social Media Management Market is valued at approximately USD 19.4 billion in 2024 and is projected to exceed USD 44.1 billion by 2030, growing at a CAGR of 14.9%. The surge is driven by rising digital marketing budgets, increasing social media penetration, and the need for real-time audience engagement. Enterprises, from SMBs to large corporations, are adopting social media management platforms to streamline content planning, performance analytics, customer interaction, and brand monitoring. As online presence becomes a competitive differentiator, businesses are leveraging these tools to build loyalty, drive conversions, and align with audience behavior.

Key Takeaways

  • Market to reach over USD 44.1 billion by 2030

  • CAGR forecasted at 14.9% from 2024 to 2030

  • Increased use across e-commerce, entertainment, and BFSI sectors

  • Demand driven by real-time engagement and customer service needs

  • Integration of AI enhances campaign personalization and performance tracking

  • SMEs adopting cloud-based tools for cost efficiency

  • Influencer marketing integration boosts platform utility

  • Growing emphasis on data-driven content strategies

  • Multi-platform management critical for omnichannel outreach

  • North America leads; APAC shows high growth potential

Emerging Trends
AI and machine learning are transforming the social media management landscape by automating content creation, sentiment analysis, and predictive analytics. Platforms are increasingly offering integrated influencer management, social listening, and ROI-focused dashboards. Chatbots and generative AI tools enable real-time customer interactions. Cross-platform content scheduling with localization capabilities is rising. Short-form video content tools and trend detection algorithms are gaining traction. Compliance with data privacy regulations like GDPR is shaping content governance. Tools offering integration with CRM, e-commerce platforms, and advertising channels are now standard. Voice and visual search optimization, along with augmented reality filters, are the next frontier in social media engagement.

Use Cases

  • Centralized content scheduling and publishing across platforms

  • Social listening to monitor brand mentions and sentiment

  • Customer support automation via social chatbots

  • Campaign performance tracking and analytics dashboards

  • Influencer collaboration and outreach management

  • Crisis communication and online reputation management

  • Competitor benchmarking and industry trend analysis

  • Personalized ad targeting and engagement tracking

  • Integration with CRM for lead generation and nurturing

  • Localization of content for regional brand presence

Major Challenges
Key challenges include platform fragmentation, which complicates consistent multi-channel engagement. Data overload and lack of actionable insights can hinder decision-making. Managing negative feedback or viral misinformation requires rapid response mechanisms. Ensuring compliance with changing data privacy laws adds regulatory complexity. The high pace of content cycles demands constant creativity and agility. Budget limitations for SMEs can restrict adoption of comprehensive tools. Integration difficulties with legacy systems and internal workflows can slow digital transformation. Additionally, fake followers and non-genuine engagement can distort analytics. Balancing automation with authentic customer interaction remains a persistent challenge for brands.

Opportunities
There is significant opportunity in expanding AI-driven personalization and predictive content planning. As social commerce grows, platforms enabling seamless integration with online stores will gain traction. Growing influencer marketing requires dedicated management and analytics features. Emerging markets with rising internet penetration offer untapped user bases. Real-time language translation tools can unlock global audience engagement. Unified customer experience across marketing, sales, and service channels presents new value streams. Vertical-specific tools for healthcare, finance, and education represent niche growth areas. Additionally, ESG communication and sustainability storytelling via social platforms present new corporate engagement opportunities in an increasingly values-driven marketplace.

Key Players Analysis
Key players in the Social Media Management market are focusing on building unified platforms that combine content creation, scheduling, analytics, and customer engagement. They invest heavily in AI, machine learning, and natural language processing to automate workflows and optimize campaign outcomes. These companies cater to enterprises and SMEs by offering scalable, modular pricing models and cloud-native solutions. Strategic partnerships with social networks, CRM providers, and e-commerce platforms enhance product capabilities. Focus is also placed on mobile-first features, influencer management, and integrated social advertising tools. Geographic expansion, multi-language support, and compliance with privacy laws are central to sustaining their global footprint.

Conclusion
The Social Media Management Market is rapidly evolving as digital interactions redefine brand-consumer dynamics. With substantial market growth ahead, fueled by automation, real-time engagement, and data-driven decision-making, businesses increasingly rely on robust social media strategies. Despite challenges in compliance, authenticity, and platform diversity, innovation in AI and analytics is reshaping how brands manage their online presence. As organizations seek greater alignment between marketing efforts and business outcomes, social media management tools will become vital to competitive differentiation, audience loyalty, and scalable communication in an ever-connected digital ecosystem.