Friday, October 9, 2026
Home Blog Page 123

Fortifying Digital Frontiers: An In-Depth Analysis of the Network Security Market

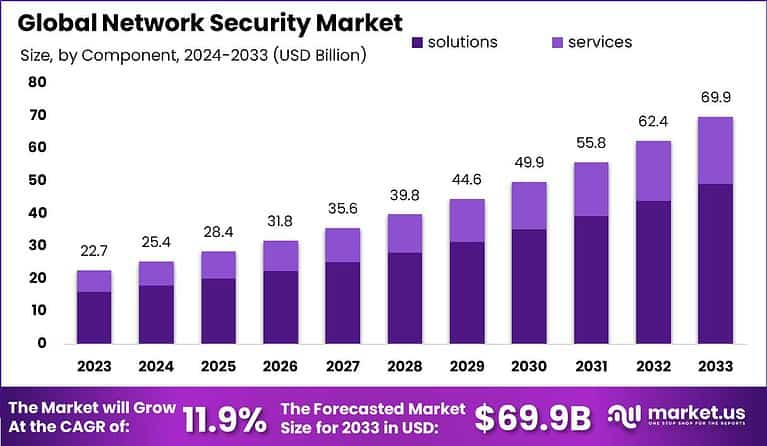
The global Network Security Market is valued at approximately USD 35.7 billion in 2024 and is projected to surpass USD 68.4 billion by 2030, expanding at a CAGR of 11.2%. Growth is driven by the escalating frequency of cyberattacks, expanding enterprise digital footprints, and stricter regulatory requirements. The shift to hybrid work models and cloud-based infrastructure has intensified demand for advanced security solutions. Organizations across all sectors are increasingly investing in next-generation firewalls, intrusion detection systems, and zero-trust frameworks to protect critical data, ensure business continuity, and maintain compliance in a rapidly evolving threat landscape.

Key Takeaways

  • Market expected to exceed USD 68.4 billion by 2030

  • CAGR projected at 11.2% between 2024 and 2030

  • Rising cyber threats fueling enterprise security investments

  • Zero-trust architecture adoption accelerating across sectors

  • BFSI and healthcare lead in spending due to data sensitivity

  • Cloud-native and edge security solutions gaining traction

  • Regulatory mandates (GDPR, HIPAA, etc.) boost compliance needs

  • SMEs adopting managed security services due to cost-effectiveness

  • AI and ML integration improving threat detection accuracy

  • APAC expected to witness fastest growth due to digital transformation

Emerging Trends
Emerging trends in the network security market include the rapid integration of AI and machine learning for threat detection and response automation. Zero-trust models are becoming standard, especially in hybrid work environments. Secure Access Service Edge (SASE) and cloud-delivered security services are seeing increased adoption. Encryption technologies are evolving to counter post-quantum threats. Identity and access management tools are becoming more adaptive and context-aware. Extended Detection and Response (XDR) platforms are consolidating visibility across endpoints, networks, and cloud workloads. Additionally, decentralized cybersecurity ecosystems using blockchain for secure identity and transaction verification are gaining momentum across enterprise IT landscapes.

Use Cases

  • Protecting corporate networks against ransomware and phishing attacks

  • Securing remote access for employees through VPN and zero-trust policies

  • Real-time traffic monitoring in financial institutions and healthcare facilities

  • Cloud workload protection for SaaS and IaaS platforms

  • Threat intelligence sharing across industry consortiums

  • Data loss prevention in sensitive environments like defense and banking

  • Firewall-as-a-service for scalable SMB protection

  • Multi-layered protection for industrial IoT and smart factories

  • Identity verification and access control in e-commerce platforms

  • Secure communication infrastructure for government agencies and critical services

Major Challenges
The network security market faces key challenges including a growing shortage of skilled cybersecurity professionals, making it difficult for organizations to manage complex security infrastructures. Rapidly evolving threat landscapes outpace traditional defenses, requiring constant updates and innovation. Budget constraints, especially in SMEs, hinder the adoption of advanced solutions. Integrating security across hybrid, multi-cloud environments presents significant technical complexities. False positives and alert fatigue reduce operational efficiency. Moreover, complying with ever-evolving global cybersecurity regulations poses logistical and legal challenges. Additionally, insider threats, encrypted traffic inspection, and the sophistication of state-sponsored attacks add further strain to current security systems.

Opportunities
Significant opportunities lie in the development of AI-powered security automation and threat prediction systems. The rise of IoT, 5G, and edge computing creates demand for specialized network security solutions. SMEs represent a vast untapped market for scalable, cost-effective managed security services. Adoption of cloud-first strategies is driving demand for container and serverless workload protection. Governments worldwide are investing heavily in critical infrastructure cybersecurity, opening new public sector markets. The rise of quantum computing also presents a market for post-quantum cryptography solutions. Cyber insurance and security-as-a-service models are also gaining traction, offering opportunities for service providers and software vendors.

Key Players Analysis
Key players in the network security market are focusing on holistic, integrated platforms that combine endpoint, network, and cloud protection. They invest in AI-driven threat intelligence, automation, and orchestration to deliver faster and more accurate responses. Leading firms are developing scalable solutions tailored to both enterprises and SMEs. Strategic acquisitions and partnerships enable broader portfolio expansion across sectors like IoT, healthcare, and finance. Innovation in cloud-native architecture, zero-trust enforcement, and encrypted traffic analytics is central to maintaining competitive edge. These players are also expanding globally, particularly in emerging markets, and offer compliance-driven services to address regional cybersecurity mandates.

Conclusion
The network security market is undergoing rapid evolution as organizations face increasingly sophisticated threats in a complex digital landscape. With a strong growth trajectory, driven by cloud migration, remote work, and regulatory mandates, cybersecurity is now a strategic priority. While challenges around skills, cost, and integration persist, advancements in AI, zero-trust, and cloud-native solutions present powerful tools to mitigate risks. Continued innovation, global collaboration, and education will be key to navigating future threats. As digital transformation accelerates, network security remains foundational to safeguarding trust, data integrity, and operational resilience across every sector.
 

Greener Horizons: Strategic Insight into the Cloud Sustainability Market

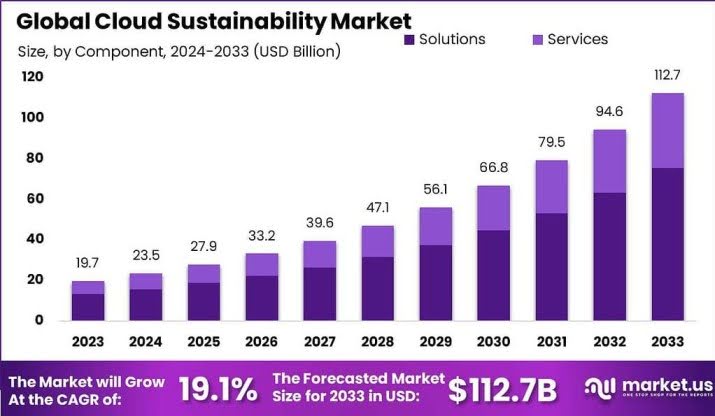
The global Cloud Sustainability Market is estimated to be valued at USD 5.2 billion in 2024 and is projected to surpass USD 13.4 billion by 2030, growing at a CAGR of 17.2%. The market’s growth is driven by increasing regulatory pressure, enterprise ESG commitments, and the rising demand for carbon-conscious digital infrastructure. Cloud providers are investing in renewable energy, green data centers, and sustainable cloud architectures. Organizations are shifting workloads to eco-efficient cloud platforms, recognizing their potential to lower emissions, reduce energy costs, and meet net-zero goals. Demand is particularly strong in IT, BFSI, and manufacturing sectors.

Key Takeaways

  • Market projected to reach USD 13.4 billion by 2030

  • CAGR of 17.2% between 2024 and 2030

  • Rise in adoption of energy-efficient cloud architectures

  • Strong demand from enterprises aiming for net-zero carbon

  • Sustainability becoming a key differentiator among cloud providers

  • Green data centers seeing rapid global deployment

  • North America leads, but APAC shows fastest growth

  • Cloud-native sustainability analytics gaining traction

  • Edge computing integration reduces latency and energy use

  • Government mandates fueling demand in Europe and Asia

Emerging Trends
Green cloud frameworks are being adopted to optimize resource usage and lower carbon footprints. Major trends include the rise of carbon-aware cloud workloads, sustainability KPIs in cloud SLAs, and AI-powered optimization of energy consumption. Cloud vendors are investing in modular and liquid-cooled data centers for efficiency. There is a surge in tools for carbon tracking and reporting integrated within cloud management suites. Edge-cloud hybrid models are gaining momentum for localized, low-energy computing. Circular economy practices—like server reusability and energy reclamation—are influencing infrastructure decisions. Transparent sustainability reporting and carbon footprint calculators are also becoming standard in enterprise cloud services.

Use Cases

  • Sustainable workload orchestration for carbon-efficient operations

  • Green IT transformation initiatives in large enterprises

  • Carbon reporting and analytics via cloud-native dashboards

  • Energy-optimized AI and ML model training environments

  • Low-carbon edge-cloud deployments for smart cities

  • Financial institutions using green cloud for ESG compliance

  • Media and telecom companies reducing energy costs in content delivery

  • Government agencies hosting climate data on green cloud platforms

  • Smart manufacturing leveraging cloud to optimize energy usage

  • Health systems shifting to green cloud for patient data storage

Major Challenges
The cloud sustainability market faces hurdles such as high upfront investment in green infrastructure and lack of global carbon accounting standards. Limited awareness among SMEs and inconsistent regulatory environments across regions slow adoption. Measuring true end-to-end carbon footprints in multi-cloud environments is complex. Integration of legacy systems into sustainable cloud frameworks poses technical barriers. Some enterprises resist migration due to perceived risks of performance loss or vendor lock-in. Additionally, transparency in sustainability claims by providers is often questioned, creating trust gaps. Ensuring continuous improvements while balancing cost, performance, and environmental goals remains a persistent market challenge.

Opportunities
There’s rising opportunity in developing carbon-optimized cloud platforms tailored to specific industries like energy, logistics, and manufacturing. As governments impose stricter sustainability mandates, demand for compliant cloud services will surge. Cloud vendors can differentiate through innovations in circular cloud infrastructure, real-time emissions tracking, and carbon-neutral SLAs. AI-driven workload management for energy optimization offers significant potential. Emerging economies represent untapped markets for green cloud adoption. Strategic partnerships with clean energy providers can further enhance offerings. There’s growing demand for sustainability-as-a-service platforms to assist enterprises with ESG reporting, green transformation, and eco-centric digital strategies at scale.

Key Players Analysis
Key companies in the cloud sustainability market focus on reducing operational emissions, optimizing energy consumption, and sourcing renewable power. They differentiate through carbon-aware workload management tools and data center innovations like immersion cooling and modular infrastructure. Many are investing in proprietary platforms to track and report sustainability metrics in real time. Strategic partnerships with utility providers and ESG data platforms allow integrated green solutions. These players leverage AI and analytics to continuously optimize resource usage and emissions across cloud environments. Emphasis is placed on transparency, third-party audits, and compliance with global green standards to maintain competitive advantage.

Conclusion
The Cloud Sustainability Market is emerging as a critical enabler of enterprise environmental strategies and global net-zero goals. With increasing awareness of digital carbon footprints and pressure from stakeholders, organizations are rapidly adopting green cloud solutions. While challenges around measurement and standardization persist, advancements in green infrastructure, AI optimization, and regulatory support are accelerating market momentum. As demand grows across sectors and geographies, cloud sustainability will transition from a differentiator to a necessity, reshaping how businesses architect, deploy, and manage cloud environments in the pursuit of a cleaner digital future.

Plant Breeding and CRISPR Plants Market Benefits from Regulatory Advances and R&D Funding

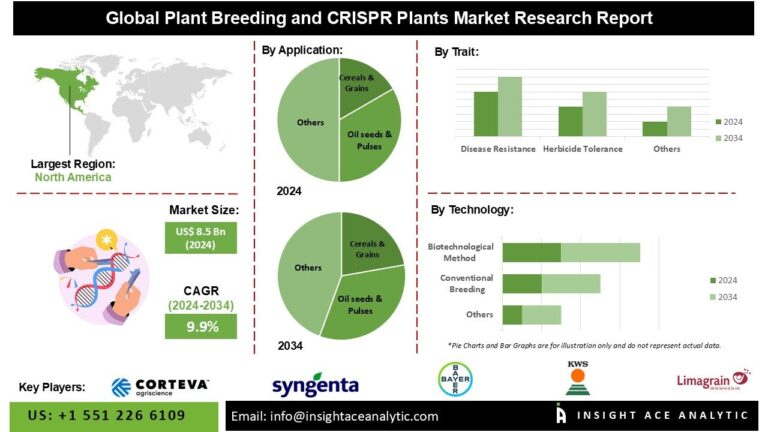
According to the latest research by InsightAce Analytic, the Plant Breeding and CRISPR Plants Market is valued at USD 8.5 Bn in 2024, and it is expected to reach USD 21.1 Bn by the year 2034  with a CAGR of 9.9% during the forecast period of 2025-2034.

Plant breeding and CRISPR (Clustered Regularly Interspaced Short Palindromic Repeats) technologies are playing an increasingly vital role in enhancing crop productivity to support the growing global population. As consumer preferences shift toward environmentally responsible farming practices, these technologies are being adopted to develop crop varieties with improved resistance to pests and diseases, thereby minimizing the need for chemical pesticides.

In the face of climate change, which poses significant threats to agricultural productivity through increased heat, drought, and other environmental stresses, CRISPR and advanced plant breeding offer solutions by enabling the development of stress-tolerant crops. These innovations help ensure food security by improving yield stability under adverse conditions.

The market for CRISPR-edited plants and plant breeding is witnessing robust growth, driven by a convergence of factors such as climate challenges, escalating global food demand, and a heightened focus on sustainable agricultural practices. Additionally, regulatory restrictions on the use of chemical pesticides are accelerating the shift toward genetically optimized crops. Increasing investments in research and development of precision breeding technologies further fuel the expansion of this sector, positioning CRISPR and plant breeding as key enablers of the future of agriculture. 

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/3003 

List of Prominent Players in the Plant Breeding and CRISPR Plants Market:

  •   Bayer AG
  •   Corteva
  •   Syngenta Group
  •   Eurofins Scientific
  •   KWS SAAT SE & Co. KGaA
  •   Limagrain
  •   BASF
  •   Beijing Dabeinong Biotechnology Co., Ltd.
  •   SAKATA SEED CORPORATION
  •   Rijk Zwaan Zaadteelt en Zaadhandel B.V.
  •   UPL
  •   Cibus Inc.
  •   Inari Agriculture, Inc.
  •   SGS Société Générale de Surveillance SA.
  •   Benson Hill Inc.
  •   KeyGene
  •   Phytoform
  •   Hudson River Biotechnology
  •   PacBio
  •   Evogene Ltd.
  •   BGI Group
  •   Sanatech Seed Co., Ltd.
  •   Pairwise
  •   TROPIC
  •   Plantae by Huminn

Market Dynamics: CRISPR and Plant Breeding

Drivers:

The demand for improved crop varieties is a key factor propelling the growth of the CRISPR and plant breeding market. As the global population continues to grow and environmental challenges intensify, there is an urgent need to develop innovative agricultural methods that can enhance productivity while utilizing limited arable land. CRISPR and modern plant breeding techniques are increasingly being applied to improve crop yields, enhance nutritional quality, and develop resistance to pests and diseases. For example, in February 2022, the U.S. National Institute of Food and Agriculture (NIFA) allocated over $14 million to support traditional plant breeding efforts aimed at creating more resilient, high-yielding crop varieties. These advancements align with the global push for sustainable food systems and are expected to significantly drive market growth. 

Challenges:

A major challenge facing the CRISPR and plant breeding market is the lack of harmonized international regulations for gene-edited crops. While countries like the United States and Japan have adopted more permissive, science-based policies—treating gene-edited crops differently from genetically modified organisms (GMOs) when no foreign DNA is involved—regions such as the European Union enforce strict regulations equating gene editing with traditional GMOs. This regulatory inconsistency complicates global commercialization, discourages investment, and creates uncertainty for developers and seed producers. The prolonged approval timelines and elevated research and compliance costs further hinder the pace at which new crop varieties can enter the market. 

Regional Trends:

The Asia-Pacific region is projected to hold a dominant share of the CRISPR and plant breeding market, driven by immediate food security needs and the region’s diverse agricultural landscape. Countries like China and India are making substantial investments in research and development, with a particular focus on enhancing staple crops such as rice in terms of yield, nutritional value, and resilience to pests and diseases. Furthermore, cross-border collaborations with global biotechnology companies and academic institutions are fostering innovation tailored to regional agricultural demands, accelerating adoption across local markets.

North America is expected to witness the fastest growth during the forecast period, underpinned by a strong ecosystem of technological innovation and a well-established agricultural sector. The region is home to several leading biotechnology firms that are at the forefront of developing and commercializing gene-edited crops. In addition to staples, there is a growing emphasis on high-value cash crops such as corn and soybeans, where CRISPR technology is being leveraged to improve drought resistance, pest tolerance, and overall productivity. These developments position North America as a key driver of future growth in the global plant breeding and CRISPR plant market. 

Recent Development:

  • February 2025: KWS SAAT SE & Co. KGaA (Germany) strengthened its market position in the sugarbeet seed sector by introducing new combination varieties that integrated strong Cercospora protection (CR+) with the CONVISO SMART system. These types were first offered in a number of European markets, and more are in the works.
  • January 2025: Apricus Seeds (US) and Syngenta Vegetable Seeds (Switzerland) have entered into a global license partnership agreement that grants Syngenta exclusive use of Apricus’ watermelon, squash, and melon genetics. This collaboration expanded Syngenta’s cucurbit line. 

Segmentation of Plant Breeding and CRISPR Plants Market-

By Application-

  • Cereals & Grains
    • Corn
    • Rice
    • Wheat
    • Others
  • Oilseeds & Pulses
    • Soybean
    • Canola
    • Cotton
    • Others
  • Fruits & Vegetables
  • Others

By Trait-

  • Herbicide Tolerance
  • Disease Resistance
  • Yield & Grain Size Improvement
  • Temperature & Stress Tolerance
  • Drought Resistance
  • Others

By Technology-

  • Conventional Breeding
    • Cross-breeding and Selection Method
      • Pedigree Breeding
      • Mass Selection
      • Bulk Breeding
      • Pure Line Selection
    • Hybridization Methods
      • Single-cross Hybrids
      • Three-way Cross Hybrids
      • Double Cross Hybrids
  • Biotechnological Methods
    • Genetic Transformation
      • Agrobacterium-mediated transformation
      • Particle bombardment/gene gun
      • PEG-mediated transformation
      • Electroporation
    • Marker-assisted Breeding
      • SNP markers
      • SSR markers
      • Others
    • Gene Editing Technologies
      • CRISPR-Cas9
      • TALENS
      • Zinc Finger Nucleases (ZFNs)
    • Tissue Culture Methods
      • Micropropagation
      • Embryo rescue
      • Anther/pollen culture
      • Protoplast fusion

By Type-

  • Biotechnological Methods
    • Molecular Breeding
    • Hybrid Breeding
    • Genetic Engineering
    • Genome Editing
  • Conventional Breeding

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa 

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.

Synthetic Tiles Market Driven by Cost-Effective, Stylish, and Eco-Friendly Flooring Solutions

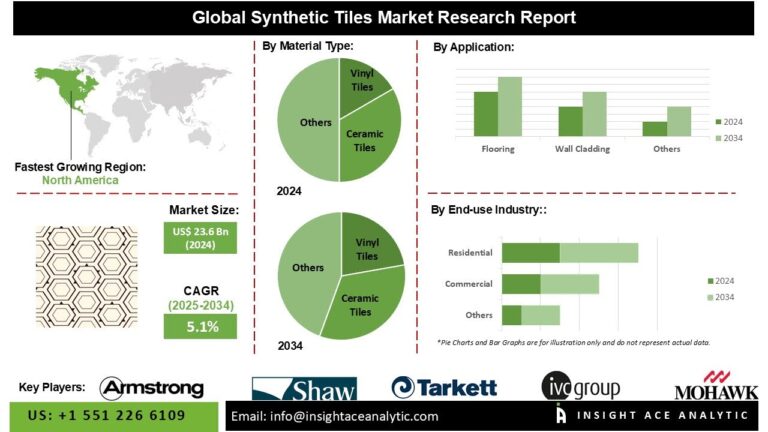
According to the latest research by InsightAce Analytic, the Synthetic Tiles Market is valued at  USD 23.6 Bn in 2024, and it is expected to reach  USD 23.6 Bn in 2024, with a CAGR of  5.1% during the forecast period of 2025-2034.

Synthetic tiles are engineered flooring materials designed to replicate the appearance of natural surfaces such as stone, wood, and ceramic, while offering enhanced durability and reduced maintenance requirements. These tiles are widely adopted across both residential and commercial sectors due to their affordability, diverse design options, and ease of installation.

The synthetic tiles market is experiencing steady growth, primarily driven by rising construction activity, a surge in home renovation projects, and increasing demand for sustainable building materials. Key growth factors include heightened consumer preference for eco-friendly products that minimize environmental impact, as well as advancements in manufacturing technologies that allow for highly realistic textures and patterns. These developments are significantly contributing to the expansion of the global synthetic tiles market. 

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/3007 

List of Prominent Players in the Synthetic Tiles Market:

  •   Mohawk Industries
  •   IVC Group (Mohawk Industries subsidiary)
  •   Tarkett
  •   Shaw Industries Group, Inc.
  •   NOX Corporation
  •   Forbo Holding AG
  •   Interface, Inc.
  •   Armstrong Flooring, Inc.
  •   Mannington Mills, Inc.
  •   Beaulieu International Group

Market Dynamics

Drivers:

The synthetic tiles market is projected to witness substantial growth, driven by increasing demand for cost-effective, durable, and visually appealing flooring solutions. Advancements in manufacturing technologies, coupled with rising consumer awareness of sustainable building practices, are expected to further stimulate market development. Additional growth drivers include accelerating urbanization, a surge in home renovation activities, and the widespread adoption of synthetic materials in commercial applications due to their resilience and low maintenance requirements. Looking ahead, the market is likely to benefit from a stronger emphasis on environmentally friendly products and innovative design offerings, positioning synthetic tiles as a competitive alternative within the broader flooring industry. 

Challenges:

Despite growing interest in eco-conscious construction materials, skepticism among consumers regarding the sustainability of synthetic tiles remains a potential barrier. Moreover, regulatory complexities related to environmental standards may constrain innovation, as manufacturers must ensure compliance while developing new products. Another significant challenge is the volatility in raw material prices—particularly petroleum-based components used in vinyl production—which can impact overall manufacturing costs and limit the industry’s ability to maintain competitive pricing. 

Regional Trends:

North America is expected to hold a leading share of the global synthetic tiles market in terms of revenue, supported by stringent building codes and a regional focus on environmentally sustainable construction. The demand for recyclable, low-impact materials has contributed to the widespread adoption of synthetic tiles. Additionally, infrastructure modernization efforts and the preference for lightweight, energy-efficient materials have further fueled market growth.

Meanwhile, Europe is anticipated to register the fastest growth rate during the forecast period, driven by rapid infrastructure development across both residential and commercial sectors. The region’s construction boom, coupled with the superior performance and aesthetic value of synthetic tiles, is encouraging their use across a variety of applications, bolstering the region’s market expansion. 

Segmentation of Synthetic Tiles Market-

By Material Type-

  • Vinyl Tiles
  • Ceramic Tiles
  • Porcelain Tiles
  • Polyurethane Tiles
  • Others

By Tile Size-

  • Small (e.g., 12×12 inches)
  • Medium (e.g., 18×18 inches)
  • Large (e.g., 24×24 inches)

By Tile Shape-

  • Square
  • Rectangle
  • Hexagonal
  • Others

By Tile Design-

  • Solid Color
  • Patterns
  • Textured
  • Wood-Look
  • Stone-Look
  • Others

By Installation Type-

  • Glue-Down Tiles
  • Click-Lock Tiles
  • Peel and Stick Tiles

By Price Range-

  • Economy
  • Mid-Range
  • Premium

By Application-

  • Flooring
  • Wall Cladding
  • Roofing
  • Others

By Distribution Channel-

  • Online Retailers
  • Specialty Stores
  • Building Material Suppliers
  • Wholesalers/Distributors

By End-User-

  • Residential
  • Commercial
  • Industrial 

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Mistakes to Avoid and How Your Miami Truck Accident Lawyer Can Help

0

After a Miami truck accident, don’t admit fault, speculate about causes, or provide incomplete statements at the scene, as these can undermine your rights. Always seek immediate medical attention to document injuries.

Avoid accepting fast insurance settlements, and promptly gather all relevant evidence, such as photos and witness contacts.

Consult a qualified truck accident attorney, like the Law Offices of Anidjar and Levine, as soon as possible; timely legal guidance preserves your options and strengthens your claim.

For expert assistance, reach out to a Miami Truck Accident Lawyer.

Next, you’ll discover how each step specifically protects your interests.

Admitting Fault or Providing Incomplete Statements at the Scene

Although the aftermath of a truck accident can leave you feeling disoriented and overwhelmed, it’s vital not to admit fault or provide incomplete statements at the scene. When you speak with police or other parties, limit your comments to the facts and avoid speculating about the cause of the accident. Admitting fault, even unintentionally, can jeopardize your ability to serve others by ensuring justice or fair compensation for all involved.

Truck accidents often involve intricate issues, such as driver negligence, and your statements may later be used to determine liability. Accident reconstruction experts may analyze every detail to establish what occurred, making it indispensable that your account remains unbiased and accurate. By refraining from making incomplete or premature statements, you allow investigators to conduct a thorough accident reconstruction and help your Miami truck accident lawyer advocate effectively on your behalf while upholding your responsibility to the greater good.

Failing to Seek Immediate Medical Attention

Protecting your legal rights after a truck accident involves more than just careful communication at the scene; promptly seeking medical attention is equally important. Even if you feel your injuries are minor, immediate evaluation by emergency response professionals ensures your well-being and establishes a clear medical record of your condition. Delaying treatment can not only compromise your health but also undermine your ability to serve others effectively in the future. It’s vital to understand that some injuries are not immediately apparent and can worsen without prompt care.

Furthermore, thorough medical documentation from the outset provides necessary evidence should you pursue a legal claim. Documentation from emergency response personnel and subsequent healthcare providers serves as a reliable record, linking your injuries directly to the accident. This step is fundamental in demonstrating the seriousness of your situation and helps your Miami truck accident lawyer build a strong, credible case on your behalf.

Accepting Quick Settlement Offers From Insurance Companies

When insurance companies contact you with a fast settlement offer after a truck accident, it’s essential to approach these proposals with caution. These early offers may seem convenient, especially if you wish to quickly resolve the matter and return to serving others in your community. However, accepting a quick settlement often means agreeing to terms that do not fully address your long-term needs or the extent of your damages. Insurance negotiations are inherently intricate, and initial offers typically favor the insurer’s interests rather than providing fair compensation for your injuries and losses.

A crucial settlement pitfall is the risk of forfeiting your right to pursue further compensation once you accept an offer. You may later discover additional expenses or medical needs that the initial settlement did not cover. Consulting a Miami truck accident lawyer ensures you steer through these insurance negotiations wisely, avoiding costly settlement pitfalls and safeguarding your ability to continue serving others effectively.

Not Gathering Sufficient Evidence After the Accident

Failing to gather sufficient evidence after a truck accident can considerably undermine your ability to pursue fair compensation for your injuries and losses. Immediate and thorough evidence collection is vital, as it forms the foundation of a strong legal claim. You should document the accident scene by taking clear photographs of vehicle damage, road conditions, and any visible injuries. Secure copies of police reports and medical records promptly. Equally important is obtaining witness testimony; witnesses can provide objective perspectives that help clarify the events leading up to the crash. Collect their contact information and brief statements while the details remain fresh in their minds. By ensuring all relevant evidence is preserved, you strengthen your capacity to serve not only your own interests, but also the broader pursuit of justice and accountability. A meticulous approach to evidence collection increases the likelihood of a favorable outcome in your truck accident case.

Waiting Too Long to Consult a Qualified Truck Accident Attorney

Although the aftermath of a truck accident can feel overwhelming, delaying the decision to consult a qualified truck accident attorney can considerably jeopardize your legal rights and potential compensation. Timely consultation ensures that essential evidence is preserved, deadlines are met, and you benefit from legal proficiency from the outset. When you wait too long, you risk losing valuable opportunities to serve both your own interests and those who rely on you. Acting promptly demonstrates responsibility and maximizes your chance of a favorable outcome. Consider these risks associated with delayed action:

  • Evidence may be lost or destroyed, compromising your claim’s strength
  • Witness recollections can fade, reducing testimonial accuracy
  • Statutory deadlines may expire, eliminating your legal recourse
  • Insurance companies might take advantage of your unrepresented status
  • Critical documentation and records could become inaccessible

Engaging a legal professional immediately empowers you to protect your rights and pursue fair compensation for all affected parties.

Conclusion

By avoiding these common mistakes after a truck accident, you can protect your rights and strengthen your case. Engaging the Law Offices of Anidjar and Levine ensures you receive thorough guidance at every stage, from collecting vital evidence to negotiating with insurance companies. Rely on your attorney’s experience to navigate complex legal processes, maximize your compensation, and help you avoid costly errors. For expert assistance, contact a Miami Truck Accident Attorney. Taking prompt, informed action is crucial for achieving the best possible outcome in your claim.

Precision at the Core: Probe Card Market Growth, Trends, and Outlook

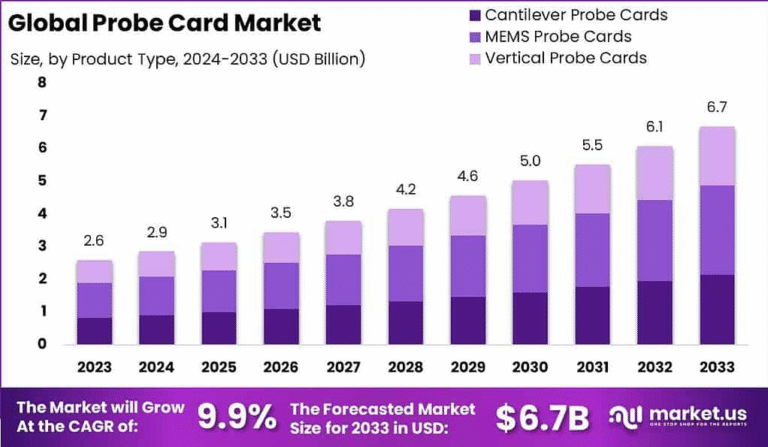
The global Probe Card market, valued at approximately USD 3.5 billion in 2024, is projected to exceed USD 5.6 billion by 2030, growing at a CAGR of 8.1%. This growth is fueled by rising demand for advanced semiconductor testing in AI, 5G, and automotive applications. Increasing wafer complexity and the transition to smaller process nodes significantly impact demand for high-performance probe cards. As chipmakers invest in R&D and testing accuracy, probe cards are becoming indispensable in wafer-level testing. The market is driven by innovation in probe technologies and evolving packaging and testing standards.

Key Takeaways

  • Market to surpass USD 5.6 billion by 2030

  • CAGR estimated at 8.1% (2024–2030)

  • MEMS probe cards dominate due to precision and reliability

  • Growth fueled by 5G, AI chips, and automotive semiconductors

  • Wafer-level testing demand increasing across fabs

  • Advanced packaging drives complex probe card design

  • High-end memory and logic ICs pushing need for multi-die testing

  • Asia-Pacific leads market with major semiconductor fabs

  • Focus on reducing test cost per die through reusable probe cards

  • Shift toward fully automated testing and smart probes

Emerging Trends
Emerging trends include the rise of MEMS-based and vertical probe card technologies, supporting finer pitches and complex die testing. The push toward heterogeneous integration and advanced packaging is reshaping probe card configurations. Customization is becoming key to address specific IC test requirements. Integration of AI and data analytics into wafer test systems is helping optimize probe performance. Demand is also rising for high-temperature and cryogenic probe cards, especially for automotive and quantum computing components. Environmental sustainability is gaining importance, with reusable probe materials and waste reduction initiatives. Miniaturized electronics and shrinking node sizes continue to challenge probe card innovation.

Use Cases

  • Wafer-level testing of memory and logic ICs in semiconductor fabs

  • Testing of high-frequency RF and 5G chipsets

  • Automotive-grade chip testing under extreme conditions

  • Quality assurance in AI and GPU processors manufacturing

  • Fine-pitch testing in mobile SoCs and microcontrollers

  • Advanced packaging testing in fan-out and 2.5D/3D ICs

  • Burn-in and reliability testing for aerospace/defense semiconductors

  • High-volume production testing for consumer electronics

  • Multi-die system testing in heterogeneous chipsets

  • R&D validation of prototype semiconductor devices

Major Challenges
The probe card market faces challenges including the rising complexity of IC designs and finer pitches, which demand higher precision and costlier probe solutions. Manufacturing probe cards for 3D ICs and high-speed devices requires advanced technologies and significant R&D investment. Frequent maintenance and short life cycles of probe cards can affect testing efficiency and cost. Lack of standardization and compatibility issues with different wafer test systems hinder seamless integration. Supply chain disruptions and fluctuations in semiconductor demand cycles also impact production planning. Additionally, ensuring probe card durability while maintaining low contact resistance remains a persistent engineering hurdle.

Opportunities
Expanding applications of semiconductors in AI, automotive, and IoT create new opportunities for advanced probe card solutions. The rise of 3D packaging and chiplet architecture demands sophisticated testing interfaces, opening doors for innovation. Emerging semiconductor markets in India and Southeast Asia offer new customer bases. There’s a strong opportunity for automated, smart probe cards that enhance yield prediction using analytics. Cryogenic and high-voltage probe solutions will see increased demand from next-gen computing and EV industries. As foundries push for time-to-market efficiency, probe cards that reduce downtime and improve accuracy will be critical. Sustainable manufacturing practices also present strategic growth levers.

Key Players Analysis
Leading probe card manufacturers are investing in R&D to support next-generation chips, focusing on reducing cost per test while maintaining accuracy. They are diversifying product portfolios across vertical and MEMS-based solutions to address different test requirements. Strategic collaborations with semiconductor foundries and test equipment providers are common to streamline integration and compatibility. These companies prioritize innovation in materials and probe designs to support harsh environments and advanced packaging. By expanding regional production capabilities and service networks, they cater to localized demand. Many also engage in joint development projects with fabless firms to develop application-specific, high-reliability probe solutions.

Conclusion
The Probe Card market is evolving rapidly alongside semiconductor advancements, driven by increasing complexity in IC designs and demand for precise, cost-effective testing. As industries rely more heavily on high-performance chips, probe cards play a pivotal role in ensuring functionality and reliability. Despite challenges around design precision and cost pressures, strong opportunities exist in emerging applications like AI, 5G, and EVs. The market’s future hinges on continuous innovation, sustainability, and integration with automated test environments. With strategic investments and adaptive technologies, probe cards will remain critical enablers in the next wave of semiconductor innovation.


Unlocking Compliance and Optimization: Software License Management Market Outlook 2025

Introduction:
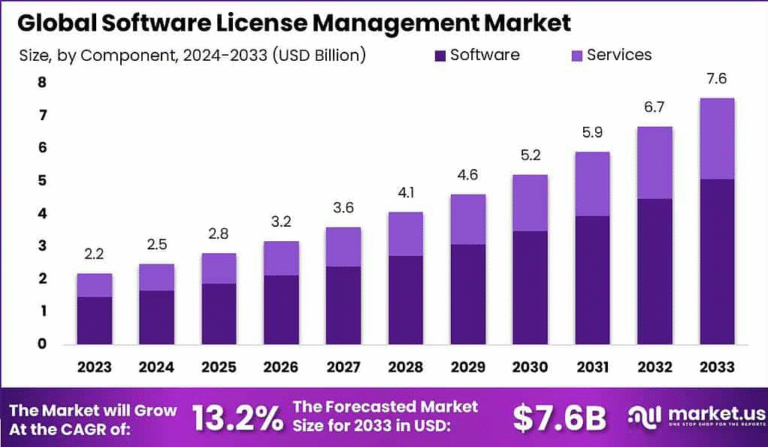
The Software License Management (SLM) Market is expected to reach USD 6.2 billion by 2030, growing at a CAGR of 10.4% from 2024. Increasing software adoption across enterprises, coupled with rising concerns about compliance, cost optimization, and audit readiness, is fueling demand. SLM solutions help organizations track, control, and optimize software usage across hybrid IT environments. The shift toward SaaS, cloud computing, and subscription-based licensing models has intensified the need for centralized, automated license tracking. Businesses are increasingly investing in SLM platforms to reduce legal risks, manage IT assets efficiently, and ensure alignment with dynamic vendor licensing terms.

Key Takeaways:

  • Market projected to hit USD 6.2 billion by 2030

  • CAGR of 10.4% driven by compliance and digital transformation

  • Cloud and SaaS models are accelerating SLM adoption

  • Audit preparedness and risk mitigation are key purchase drivers

  • Enterprises seek centralized license visibility and control

  • Hybrid environments require multi-platform license tracking

  • Automation reduces manual errors and administrative overhead

  • Cost savings through optimized software usage

  • Strong adoption in BFSI, IT, and healthcare sectors

  • North America leads; APAC is emerging rapidly

Emerging Trends:
AI and machine learning are being integrated into SLM platforms to predict software usage trends and recommend cost-saving measures. Blockchain is emerging as a tool for secure, transparent license validation. Cloud-native SLM solutions offer seamless scalability and integration with hybrid environments. Vendors are providing user-centric dashboards for real-time usage analytics. License-as-a-service and pay-per-use models are gaining popularity, especially in SMBs. Integration with IT asset management (ITAM) and Configuration Management Databases (CMDB) is becoming a standard. Automation of audit reporting and compliance tracking is enhancing operational efficiency. SLM platforms are evolving to manage IoT and API-based software deployments across enterprises.

Use Cases:

  • Monitoring enterprise-wide license usage and compliance

  • Identifying unused software for cost optimization

  • Ensuring license alignment during cloud migrations

  • Automating audit reports for vendor inspections

  • Enforcing compliance across geographically distributed teams

  • Managing software renewals and subscription cycles

  • Detecting over- or under-utilization of license entitlements

  • Integrating with ITAM tools for holistic asset visibility

  • Controlling access to licensed software in virtual environments

  • License pooling and sharing across departments or business units

Major Challenges:
Complex vendor licensing models can be difficult to interpret and manage. Legacy systems often lack integration capabilities with modern SLM tools. Ensuring real-time tracking across hybrid and multi-cloud environments remains challenging. High implementation and training costs can be a barrier for SMEs. Inadequate data quality and visibility impede accurate license optimization. Regulatory differences across regions complicate global compliance strategies. Resistance from internal stakeholders may slow the adoption of new processes. Vendor audits can lead to unexpected financial liabilities if license data is inaccurate. Managing licenses for non-traditional platforms (e.g., APIs, IoT) remains underdeveloped. Security and data privacy concerns in cloud-based solutions persist.

Opportunities:
Rapid cloud adoption is increasing the need for SLM across enterprises. SMEs represent an untapped market for affordable, easy-to-use solutions. Integration with FinOps platforms can offer enhanced visibility into IT spend. AI-powered analytics can provide actionable insights into license utilization. Growing remote and hybrid workforces demand scalable license management. Increased regulatory scrutiny creates demand for proactive compliance tools. Multi-tenant license management offers opportunities for managed service providers (MSPs). Emerging markets are investing in IT governance, opening regional growth avenues. SLM’s role in cybersecurity frameworks is expanding. Customizable licensing reports support better IT procurement and strategic planning.

Key Players Analysis:
The SLM market includes a mix of global enterprise software vendors, IT asset management providers, and specialized compliance-focused startups. Companies differentiate through depth of integrations, user experience, automation capabilities, and vendor support. Some focus on cloud-first deployments, while others offer hybrid or on-premise solutions tailored to highly regulated industries. Competitive edge is often defined by real-time analytics, scalable licensing models, and global compliance features. Strong ecosystems, including APIs and ITSM tool compatibility, play a role in market leadership. Vendors are increasingly investing in AI and machine learning to automate policy enforcement and improve ROI on software investments.

Conclusion:
The Software License Management Market is becoming essential to organizations navigating increasingly complex IT ecosystems and licensing landscapes. As digital transformation accelerates and compliance risks rise, SLM solutions offer a critical pathway to governance, cost optimization, and audit readiness. While challenges remain in integration and education, the market’s trajectory is reinforced by technological innovation, regulatory demands, and enterprise needs for transparency and efficiency. As AI, automation, and cloud-native tools evolve, SLM will continue to drive strategic value, enabling businesses to control software costs, mitigate risks, and maximize ROI from digital assets in an increasingly software-defined world.


Flexibility at Scale: On-Demand Warehousing Market Outlook 2025

Introduction:
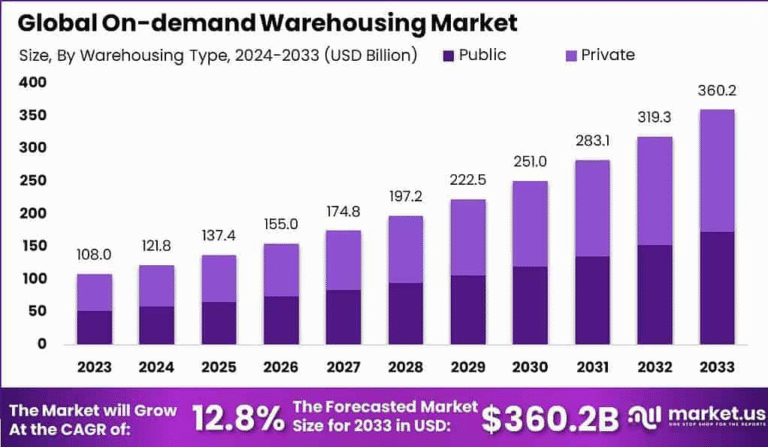
The On-demand Warehousing Market is projected to surpass USD 30 billion by 2030, growing at a CAGR of 19.3% from 2024. This rapid growth is fueled by rising e-commerce volumes, supply chain disruptions, and demand for flexible storage solutions. Businesses seek scalable warehousing without long-term leases to optimize inventory during seasonal peaks and geographic expansions. The gig economy and real-time logistics models are influencing warehousing strategies. On-demand platforms enable companies to rent space and services as needed, lowering operational costs and enhancing responsiveness, making this model a cornerstone in modern, agile supply chain management.

Key Takeaways:

  • Market expected to exceed USD 30 billion by 2030

  • CAGR of 19.3% driven by e-commerce and logistics flexibility

  • High demand from SMEs and omnichannel retailers

  • Enables seasonal, short-term, and location-flexible storage

  • Reduces capital expenditure on fixed warehouse assets

  • Real-time inventory visibility enhances decision-making

  • Integration with third-party logistics (3PLs) and shipping partners

  • Digital platforms match warehouse supply with user demand

  • North America and Asia-Pacific lead in adoption

  • Retail, fashion, and consumer goods are major user sectors

Emerging Trends:
AI and data analytics are optimizing space allocation and inventory placement in real-time. Platforms are integrating with e-commerce systems for seamless fulfillment. Smart contracts using blockchain are enabling transparent and secure transactions. Sustainable warehousing practices, including energy-efficient storage spaces, are on the rise. Drones and robotics are being introduced for automated inventory handling. Cloud-based WMS solutions allow centralized visibility across decentralized storage networks. Predictive analytics forecast space demand based on order history and location trends. Warehousing-as-a-Service (WaaS) models are emerging, offering bundled logistics solutions. Urban micro-warehousing is trending to support last-mile delivery. Shared warehousing is reducing costs for small businesses.

Use Cases:

  • Seasonal inventory overflow management for retailers

  • Temporary storage during new market entry or expansion

  • Short-term warehousing for promotional or flash sale events

  • E-commerce fulfillment in proximity to high-demand zones

  • Reverse logistics and returns management for online retailers

  • B2B goods consolidation and distribution

  • Disaster recovery storage during supply chain disruptions

  • Temporary warehousing for construction and industrial projects

  • Staging points for last-mile delivery in urban centers

  • Cold storage for food and pharmaceutical short-term needs

Major Challenges:
Ensuring consistent service levels across varied warehouse partners can be difficult. Integration between on-demand platforms and legacy IT systems is often complex. Real-time visibility and control over third-party inventory remains a concern. Regulatory compliance and liability distribution between users and providers lack standardization. Quality control and safety standards vary widely across facilities. 

Data privacy risks arise from shared digital platforms. Limited awareness among traditional businesses slows adoption. Geographical coverage gaps exist in rural or underserved regions. Dependence on reliable logistics partners adds an external risk layer. Balancing cost-efficiency with speed and service consistency is a continuing challenge.

Opportunities:
Rising demand for agility in supply chain operations presents vast growth potential. SMEs benefit from pay-per-use storage models without capital investment. Urban e-commerce fulfillment opens the door for micro-warehouse networks. Cross-border trade creates demand for flexible international staging points. Integration with real-time tracking and IoT devices improves operational accuracy. Warehouse sharing models help monetize underutilized space. Growing demand for green logistics creates opportunities in sustainable facility design. Subscription-based warehousing services provide recurring revenue potential. Partnerships with last-mile delivery platforms add service value. Government support for digital logistics platforms and smart infrastructure accelerates adoption in emerging economies.

Key Players Analysis:
The on-demand warehousing market consists of digital logistics startups, traditional 3PLs, and platform-based aggregators. These players offer cloud-based interfaces for businesses to rent warehouse space, along with optional fulfillment services. Some focus on B2B users while others cater to e-commerce brands. 

Competitive differentiation lies in geographic coverage, API integration, real-time inventory tracking, and value-added logistics services. Companies are increasingly forming alliances with transport firms, retail platforms, and warehouse owners. Investment in predictive analytics, user-friendly dashboards, and flexible pricing models is prominent. Players emphasize quick onboarding, scalable solutions, and seamless connectivity with existing retail and supply chain ecosystems.

Conclusion:
The On-demand Warehousing Market is transforming traditional storage into a dynamic, digital-first model that prioritizes flexibility, cost-efficiency, and speed. As businesses shift toward more agile and scalable logistics operations, on-demand solutions are becoming central to supply chain resilience. 

Despite challenges in standardization and integration, innovations in AI, cloud platforms, and shared logistics models are driving rapid adoption. The market offers immense potential across industries—from e-commerce to manufacturing—especially in a world demanding real-time responsiveness and resource efficiency. With the continued convergence of technology and logistics, on-demand warehousing is positioned to redefine the future of inventory and distribution management.


Smart Storage Revolution: AI in Warehousing Market Outlook 2025

Introduction:
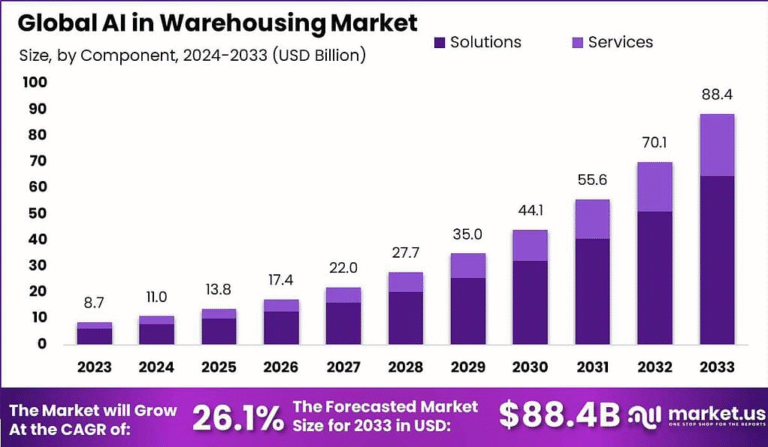
The AI in Warehousing Market is projected to reach over USD 12.5 billion by 2030, growing at a CAGR of 20.6% from 2024. The surge is fueled by the rising demand for automation, accuracy, and efficiency in warehouse operations across retail, logistics, manufacturing, and e-commerce sectors. AI technologies—such as machine learning, computer vision, and robotics—are reshaping inventory management, order fulfillment, and predictive maintenance. Labor shortages and increasing SKU complexity are accelerating AI deployment. As supply chains become more data-driven, AI-powered warehousing solutions offer real-time visibility, cost savings, and resilience in a fast-evolving logistics landscape.

Key Takeaways:

  • Market to exceed USD 12.5 billion by 2030
  • CAGR of 20.6% driven by automation and logistics growth
  • High adoption in retail, e-commerce, and manufacturing sectors
  • Computer vision aids in real-time inventory trackingAI robots optimize picking and sorting processes
  • Predictive analytics reduce equipment downtime
  • Labor shortages drive demand for AI-driven workflows
  • North America leads in innovation and deployment
  • Cloud-based warehouse management solutions gain traction
  • Increased demand for energy-efficient smart warehousing

Emerging Trends:
AI is increasingly integrated into autonomous mobile robots (AMRs) for real-time navigation and dynamic task execution. Predictive analytics tools are being used for demand forecasting and stock replenishment. Vision-based quality control systems ensure faster and more accurate inspections. Voice-assisted AI enhances human-robot collaboration in hybrid warehouse environments. AI-enabled digital twins are helping simulate warehouse layouts and improve throughput. Integration with IoT devices is providing real-time environmental monitoring. Edge AI is enabling faster, decentralized decision-making in time-sensitive tasks. AI-powered safety systems are enhancing worker protection. Cloud-AI platforms are emerging for centralized control and insights across multi-location warehouse networks.

Use Cases:

  • Automated guided vehicles (AGVs) for goods movement
  • AI-driven inventory forecasting and optimization
  • Real-time visual inspection for quality assurance
  • Predictive maintenance of warehouse equipment
  • Dynamic slotting to reduce picking time
  • Intelligent parcel sorting and routing in logistics hubs
  • AI-powered workforce scheduling and task assignment
  • Real-time demand forecasting for e-commerce fulfillment
  • Environmental monitoring using AI and IoT integration
  • AI-assisted safety surveillance and incident detection

Major Challenges:
High initial investment and integration costs can hinder adoption, especially for small and mid-sized warehouses. Legacy infrastructure poses compatibility issues with modern AI systems. Shortage of skilled personnel to manage AI platforms remains a bottleneck. Concerns over data privacy and cybersecurity in cloud-based systems are rising. Algorithmic bias and errors can affect warehouse decision-making. Real-time data collection and processing at scale can lead to latency or inaccuracies. Lack of standardization across AI tools complicates interoperability. Resistance to change from traditional warehouse operators may delay implementation. Dependence on continuous data training for accuracy increases operational complexity. Ensuring consistent ROI from AI deployment remains uncertain.

Opportunities:
Rising e-commerce volumes offer large-scale AI deployment opportunities in last-mile fulfillment. Development of modular AI systems enables scalable adoption for small businesses. Integration with robotics expands automated capabilities across industries. Government initiatives for smart logistics and Industry 4.0 create supportive environments. Cross-border warehousing expansion demands AI for multilingual, multi-region operations. AI can enhance sustainability by optimizing energy use and reducing waste. Real-time customer analytics integration into warehousing creates end-to-end supply chain visibility. Cloud-based AI platforms offer cost-effective, flexible solutions. Partnerships between tech companies and logistics providers foster innovation. Training and certification programs in AI warehouse operations open up workforce development opportunities.

Key Players Analysis:
The AI in Warehousing market consists of robotics manufacturers, logistics tech firms, AI software developers, and warehouse management system (WMS) providers. Key players focus on delivering integrated solutions combining machine learning, robotics, IoT, and data analytics. Some specialize in specific areas like robotic picking, vision systems, or AI-powered inventory management. Companies invest heavily in R&D for autonomous navigation, real-time tracking, and energy-efficient designs. Strategic collaborations with logistics providers and retail giants help scale solutions. Market leaders emphasize interoperability, scalability, and customizable AI modules. Competitive differentiation is shaped by cost efficiency, accuracy rates, and ease of integration with existing infrastructure.

Conclusion:
AI in warehousing is ushering in a transformative era of intelligent logistics, driving operational efficiency, cost reduction, and resilience across supply chains. Despite challenges like high deployment costs and integration hurdles, the technology offers immense potential through robotics, real-time data, and predictive analytics. As digital transformation accelerates across industries, AI becomes critical to managing rising inventory complexity and labor constraints. With continuous innovation, supportive policy frameworks, and scalable solutions, AI-powered warehousing is set to redefine the future of storage, distribution, and fulfillment—positioning itself as a cornerstone of next-generation supply chain optimization.

Digital Reading Revolution: eBooks Market Outlook 2025

Introduction:
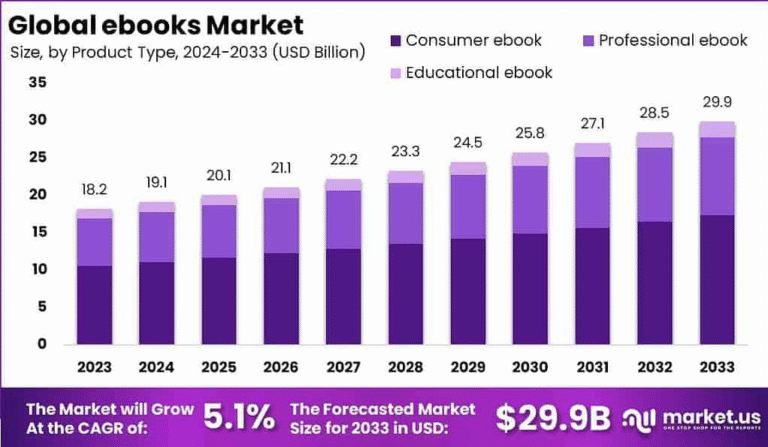
The global eBooks market is projected to surpass USD 24 billion by 2030, growing at a CAGR of 7.2% from 2024. The market’s growth is driven by increasing digital adoption, convenience of portable reading, and the proliferation of smartphones, tablets, and eReaders. Educational institutions and publishers are rapidly shifting to digital formats to reduce costs and increase accessibility. Consumer preference for instant access, customizable fonts, and integrated dictionaries is further propelling demand. As reading habits evolve toward mobile platforms and subscription models, the eBooks market is becoming a key segment of the digital content economy across entertainment, education, and publishing.

Key Takeaways:

  • Market to exceed USD 24 billion by 2030

  • CAGR of 7.2% driven by mobile and eReader adoption

  • E-learning and academic publishing lead digital shift

  • High demand for multilingual and genre-diverse content

  • Self-publishing platforms empower indie authors

  • Subscription-based models expand reader access

  • Enhanced interactivity in children’s and educational eBooks

  • Cost-effectiveness vs. print attracts institutions

  • North America and Asia-Pacific hold dominant shares

  • Cloud libraries and offline access features improve UX

Emerging Trends:
AI-powered recommendation engines are personalizing user experiences in eBook platforms. Voice-enabled and read-along formats are emerging, especially in children’s content. Interactive and gamified eBooks are gaining popularity in education. Blockchain-based digital rights management (DRM) solutions are ensuring better author protection. Subscription and bundled content models are replacing per-title purchases. Integration with audiobooks and cross-media ecosystems offers multi-format experiences. Cloud syncing and offline accessibility are becoming standard features. EBooks are expanding into niche genres such as fan fiction, light novels, and webtoons. Publishers are adopting data-driven strategies to analyze reader behavior and tailor offerings. Eco-conscious readers prefer digital formats over print.

Use Cases:

  • Academic eBooks in schools and universities for cost-effective learning

  • Leisure reading across genres like fiction, biographies, and self-help

  • Corporate eBooks for training, onboarding, and compliance materials

  • Multilingual eBooks expanding global reach for authors and publishers

  • Enhanced educational eBooks with embedded quizzes and videos

  • Accessibility-focused eBooks with text-to-speech and font adjustments

  • Religious and spiritual texts in portable digital formats

  • Legal and technical manuals distributed to professionals digitally

  • Public library eBook lending with DRM-enabled access control

  • EBook collections for travelers and digital nomads

Major Challenges:
Piracy and unauthorized distribution continue to affect revenue and IP protection. Many readers still prefer the tactile experience of printed books. Compatibility issues across different devices and formats disrupt user experience. Discoverability remains difficult for new and self-published authors due to platform saturation. Pricing disparities between eBooks and physical copies confuse consumers. DRM restrictions can frustrate legitimate users. Access to eBooks in rural or underdeveloped regions remains limited. Market fragmentation across platforms creates data silos and inconsistent experiences. The lack of regulation in self-publishing may lead to content quality concerns. Technological limitations still exist in rendering complex formats like scientific equations and charts.

Opportunities:
Growing smartphone penetration in emerging markets presents new audiences for eBooks. Educational institutions adopting digital-first strategies offer long-term growth potential. Integration with audiobook platforms opens hybrid content opportunities. Self-publishing tools provide authors greater control and profitability. EBook bundling with other media—like podcasts or video series—can drive cross-platform engagement. Government and NGO initiatives to promote literacy digitally can widen market scope. Advanced AI can create personalized and adaptive learning eBooks. Eco-conscious consumers increasingly opt for digital over print. Cloud-based academic repositories and corporate libraries are gaining traction. Multilingual and regional content expansion taps into underserved demographic segments.

Key Players Analysis:
The eBooks market includes a mix of traditional publishers, digital-first platforms, self-publishing services, and technology companies. Some focus on academic and educational content, while others specialize in consumer fiction, professional manuals, or genre-specific platforms. Key vendors differentiate through pricing models, content variety, accessibility features, and user interface design. Subscription and rental-based services are rising among tech-driven companies. Vendors compete on library size, offline capabilities, cross-device syncing, and support for multimedia-rich formats. Collaboration with authors, educational institutions, and content creators is central to expanding digital libraries. Global presence, multilingual offerings, and seamless DRM are critical to remaining competitive in this dynamic space.

Conclusion:
The eBooks market is transforming the way content is consumed, offering flexibility, accessibility, and cost-efficiency for readers worldwide. Technological innovation, self-publishing empowerment, and growing educational adoption are key drivers shaping the future of digital reading. While challenges such as piracy and platform fragmentation persist, opportunities in mobile growth, AI integration, and hybrid content models present strong growth prospects. As consumer preferences shift and digital ecosystems mature, eBooks will continue to play a pivotal role in the evolution of publishing, making reading more inclusive, interactive, and sustainable in the digital age.