Thursday, October 8, 2026
Home Blog Page 71

Low-density PET Foam Market to Soar to USD 652.8 Million by 2030 Amid Green Energy & EV Surge

0

Global Low-density PET Foam Market was valued at US$ 430.5 million in 2023 and is projected to reach US$ 652.8 million by 2030, growing at a CAGR of 6.1% during the forecast period. This expansion reflects increasing demand across wind energy, transportation, and construction sectors where lightweight, high-performance materials are becoming essential.

Low-density PET Foam offers exceptional strength-to-weight ratios, thermal insulation properties, and recyclability – making it a superior alternative to traditional materials like PVC and polyurethane foams. With sustainability regulations tightening globally, manufacturers are rapidly adopting PET foam solutions that meet both performance and environmental requirements.

Get Full Report Here: https://www.24chemicalresearch.com/reports/277242/global-lowdensity-pet-foam-market-2024-232

Recent Development

Low-density PET Foam market has seen a surge in adoption across wind energy and electric vehicle (EV) sectors, driven by global initiatives toward carbon neutrality and sustainable infrastructure. In recent months, major manufacturers such as Gurit and Armacell have expanded their production capacities in Europe and Asia to meet escalating demand for lightweight, recyclable materials. Additionally, several R&D programs are underway focusing on flame retardant and high-strength PET foam variants for next-gen aerospace and building applications. These innovations are aligning with stricter regulatory standards and supporting the transition to circular economy models in key global markets.

Market Overview & Regional Analysis

Europe currently holds 38% of the global market share, driven by stringent environmental policies and advanced wind energy infrastructure. The region’s push toward a circular economy has accelerated PET foam adoption in transportation and building applications, with Germany and France leading in technological innovations.

North America follows closely, where the material’s use in marine applications and EV battery components is expanding rapidly. Meanwhile, Asia-Pacific shows the highest growth potential, with China’s wind turbine production and India’s infrastructure development fueling demand. However, raw material price fluctuations in the region present ongoing challenges.

Key Market Drivers and Opportunities

The market is primarily driven by three factors: renewable energy expansion (particularly wind turbine blade cores), lightweighting trends in automotive and aerospace sectors, and sustainable construction material demand. Wind energy applications alone account for 45% of current PET foam utilization.

Emerging opportunities include space-grade foam for satellite components, next-gen battery insulation systems, and 3D-printed architectural elements. The development of fire-retardant PET foam variants has also opened doors for stricter building code compliance.

Challenges & Restraints

While growth prospects remain strong, the industry faces hurdles including PBT (polybutylene terephthalate) substitution risks in certain applications, competing bio-based foam technologies, and the high capital intensity of recycling infrastructure. Processing complexities with thicker foam blocks also limit some manufacturing applications.

Trade tensions surrounding recycled PET feedstock and regional discrepancies in recycling policies create supply chain uncertainties. Additionally, the market must overcome perception challenges against plastic-based solutions in some green building segments.

Market Segmentation 

By Type

  • Virgin PET Foam
  • Recycled PET Foam

By Application

  • Wind Energy
  • Transportation
  • Marine
  • Building & Construction
  • Packaging
  • Others

Key Players

  • Armacell International
  • 3A Composites
  • Gurit Holding
  • DIAB Group
  • Changzhou Tiansheng New Materials
  • Sekisui Plastics
  • Petro Polymer Shargh
  • Carbon-Core

Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/277242/global-lowdensity-pet-foam-market-2024-232

Report Scope

This report provides a comprehensive analysis of the global Low-density PET Foam market from 2024 through 2032, featuring:

  • Market size estimations and growth projections
  • Detailed application and material type segmentation
  • Regional demand patterns and growth hotspots
  • Technology development roadmaps

The analysis includes:

  • Competitive landscape mapping
  • Company market share analysis
  • Product benchmarking
  • Manufacturing capacity assessments
  • Strategic initiative tracking

Primary research components cover:

  • End-user demand analysis
  • Supply chain evaluations
  • Regulatory impact assessments
  • Innovation trend mapping

About 24chemicalresearch

Founded in 2015, 24chemicalresearch has rapidly established itself as a leader in chemical market intelligence, serving clients including over 30 Fortune 500 companies. We provide data-driven insights through rigorous research methodologies, addressing key industry factors such as government policy, emerging technologies, and competitive landscapes.

  • Plant-level capacity tracking
  • Real-time price monitoring
  • Techno-economic feasibility studies

With a dedicated team of researchers possessing over a decade of experience, we focus on delivering actionable, timely, and high-quality reports to help clients achieve their strategic goals. Our mission is to be the most trusted resource for market insights in the chemical and materials industries.

Contact us:

International: +1(332) 2424 294 | Asia: +91 9169162030

Website: https://www.24chemicalresearch.com/

See Related report:

Global Recycled PET Foam Market Research Report 2024(Status and Outlook)

https://www.24chemicalresearch.com/reports/277244/global-recycled-pet-foam-market-2024-699
Global Flying Suits Market to Reach USD 415.3M by 2032, Growing at 5.3% CAGR from 2025

0

Global flying suit market was valued at USD 275.6 million in 2024 and is projected to reach USD 415.3 million by 2032, growing at a CAGR of 5.30% during the forecast period (2025-2032).

Flying suits are specialized garments designed for aerial sports and activities, offering both functionality and safety. The market is segmented into female and male flying suits, catering to different body types and performance requirements.

Get ahead of the competition—download our Sample Report for a comprehensive market overview – https://www.24chemicalresearch.com/download-sample/276132/flying-suits-market

What Are Flying Suits & Why Are They Taking Off?

Flying suits are high-performance garments engineered to ensure aerodynamic efficiency, thermal comfort, and safety during high-altitude free-fall or gliding. Originally designed for basic recreational skydiving, today’s flying suits feature smart textiles, reinforced protection zones, and even emergency tracking technology. These garments serve adrenaline junkies, tactical defense teams, and even researchers in extreme conditions.

Industry Dynamics: Key Trends and Growth Drivers

Soaring Adventure Sports Culture

An expanding base of skydiving, BASE jumping, wingsuit flying, and speed flying enthusiasts especially among Gen Z and millennials continues to be a central demand driver. The rise of social media virality around extreme air sports is fueling this growth.

Material Science Driving Safety and Performance

New-age suits integrate breathable membranes, impact-absorbing foam, and fire-resistant composites. Modular designs allow components to be easily upgraded or replaced, extending product life and customization key in both defense and high-performance recreation.

Regional Snapshot

Europe leads the global market with a 38% share, thanks to regulated safety standards and mature adventure tourism ecosystems in countries like Germany, Switzerland, and France.

North America follows closely. The U.S. accounts for a whopping 72% of regional sales, underpinned by over 400 active drop zones and military procurement of tactical suits.

Asia-Pacific is the fastest-growing region, fueled by emerging adventure tourism in China, India, and Southeast Asia.

Market Segmentation: By Type

  • Wingsuit Flying Suits
  • Tracking Suits
  • Speed Flying Suits
  • Freestyle Suits

Market Segmentation: By Application

  • Recreational/Sports: Skydivers, paragliders, and adventure tourists.

  • Military & Defense: Tactical gear with flame resistance and GPS compatibility.

  • Search & Rescue: Specialized suits for airborne operations, including smokejumpers.

  • Special Operations: High-performance suits for rapid response units and extreme environments.

Key Market Players and Their Role in Market Evolution

Rather than just naming companies, it’s important to understand how they’re pushing the boundaries:

  • Birdsuit and TonySuits are pioneers in aerodynamic design, offering tailored suits for performance enthusiasts.

  • Squirrel and Phoenix-Fly have elevated wingsuit dynamics through proprietary fabric blends and gliding architecture.

  • Vertical Suits and Fly Your Body are driving material innovation with thermal regulation and fireproofing aimed at special forces and smokejumpers.

  • Nitrowings and FlyLikeBrick focus on lightweight modular builds, enabling quick suit customization for stunt professionals and competition circuits.

  • Flying Clothing Company offers CE-certified suits, responding to Europe’s safety regulation demands.

Market Challenges to Watch

Despite growth potential, some obstacles persist:

  • High Cost: Units range from $800 to $2,500, limiting access for casual users.

  • Certification Variability: Inconsistent global safety standards can slow adoption and complicate international sales.

  • Seasonality & Weather Dependency: Air sports see fluctuating interest based on regional weather patterns.

  • Counterfeit Concerns: Fake products risk safety and undermine consumer trust, prompting legal pushback by leading manufacturers.

Future Outlook: What’s Next for the Flying Suits Market?

With growing interest from non-recreational sectors like military defense, firefighting, and scientific expeditions, the flying suits market is on the verge of expanding beyond its traditional consumer base. The integration of smart sensors, biofeedback tracking, and custom fabric tech could define the next wave of flying suit innovation. As more brands collaborate with aerospace engineers and performance athletes, expect safer, smarter, and more adaptable gear to dominate by 2032.

Check the Executive Summary and Table of Contents for key findings and structure- https://www.24chemicalresearch.com/reports/276132/flying-suits-market

Frequently Asked Questions (FAQs)

  1. What is a flying suit and who uses it?
    A flying suit is a high-performance garment designed to optimize aerodynamics, safety, and comfort during airborne sports or operations. It’s used by skydivers, military personnel, special ops units, and rescue teams.
  1. What is driving the growth of the flying suits market?
    Key growth drivers include increasing adventure tourism, rising disposable income, technological innovations in fabric design, and expanded military and emergency applications.
  1. Which regions are leading the global flying suits market?
    Europe holds the largest market share (38%), followed by North America. Asia-Pacific is the fastest-growing region due to a booming adventure sports scene.
  1. What are the main types of flying suits available today?
    Popular categories include wingsuit flying suits, tracking suits, speed flying suits, and freestyle suits each serving specific air sports or operational purposes.
  1. What are the major challenges for flying suit manufacturers?
    High costs, fragmented safety certifications, seasonal demand, and counterfeit products are major challenges facing industry stakeholders.

Contact Us:

Email: help@24chemicalresearch.com

International: +1(332) 2424 294 | Asia: +91 9169162030 

Website: https://www.24chemicalresearch.com/

Follow us on LinkedIn: https://www.linkedin.com/company/24chemicalresearch

View Related Reports: 

Global Flying Bags Market – https://www.24chemicalresearch.com/reports/293500/flying-bags-market

Fiberglass Dust Bag Market Growth Accelerates with Coated Filter Innovation and Circular Solutions

0

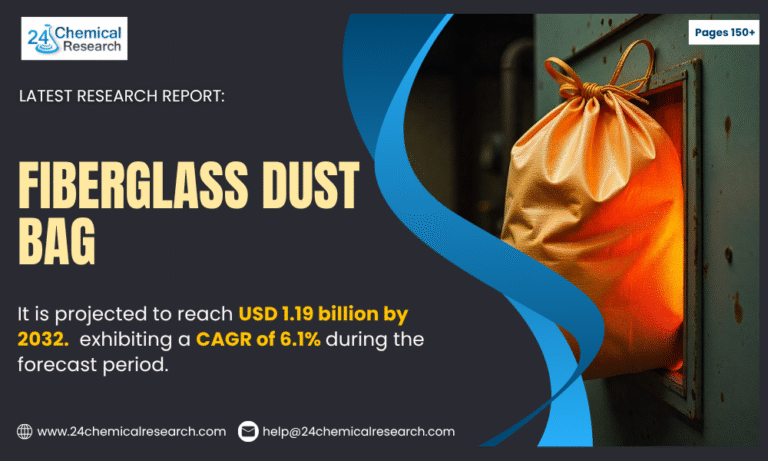
Global Fiberglass Dust Bag Market continues to demonstrate robust growth, with its valuation reaching USD 743.2 million in 2024. According to the latest industry analysis, the market is projected to grow at a CAGR of 6.1%, reaching approximately USD 1.19 billion by 2032. This growth is largely fueled by tightening environmental regulations worldwide and increasing industrial activities in emerging economies where high-temperature filtration solutions are becoming indispensable.

Fiberglass dust bags are critical components in industrial dust collection systems, offering superior thermal resistance (withstanding temperatures up to 260°C/500°F) and chemical stability. Their unique construction from woven or needle-punched fiberglass fabric makes them ideal for harsh operating environments in cement plants, power stations, and waste incineration facilities. As industries transition toward more sustainable operations, these filtration solutions are gaining prominence due to their durability and efficiency.

Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/296838/global-fiberglass-dust-bag-forecast-market-2025-2032-916

Recent Developments

Recent developments in the fiberglass dust bag market center on technological enhancements and sustainability initiatives. Manufacturers are increasingly adopting PTFE and silicone coatings, allowing fiberglass bags to maintain filtration efficiency of up to 99.97% even after 20,000 hours of operation, particularly in cement and power generation sectors. Circular economy efforts have also gained momentum, with industry leaders piloting recycling systems that recover up to 90% of fiberglass content from used bags. Additionally, companies like HL FILTER and Zhejiang Grace Environmental Technology have ramped up R&D investments to produce low-emission, high-durability filtration products tailored for extreme industrial conditions. These innovations not only extend product lifespan but also help end-users reduce replacement costs and meet stringent environmental standards

Market Overview & Regional Analysis

Asia-Pacific dominates the global fiberglass dust bag market, accounting for over 50% of demand, driven by China’s rapid industrialization and India’s expanding manufacturing sector. The region’s cement production alone grew at 5.8% CAGR from 2020-2024, creating substantial demand for high-efficiency filtration systems. Government initiatives like India’s Project SATHI, which allocated $420 million for thermal power plant modernization, are further accelerating market growth.

North America maintains significant market share through technological leadership in baghouse filtration systems and stringent emission standards. Europe’s market is shaped by the Industrial Emissions Directive (IED) and circular economy policies, while Latin America and Africa present emerging opportunities despite infrastructure challenges. The Middle East shows particular promise with ongoing megaprojects in construction and energy sectors.

Key Market Drivers and Opportunities

The market is primarily driven by global environmental regulations mandating particulate matter control, with standards now requiring 99.9% filtration efficiency in many applications. Cement plants account for 30% of demand, followed by power generation at 25% and waste management at 20%. The shift toward sustainable industrial practices presents opportunities for coated fiberglass solutions that offer longer service life and recyclability.

Innovations in PTFE and silicone-based coatings are creating high-value segments, with coated variants maintaining 99.97% efficiency after 20,000 operating hours in cement kilns. Circular economy initiatives are gaining traction, with pilot programs recovering 85-90% of glass fiber content from spent bags. These advancements align with global sustainability trends while improving cost-efficiency for end-users.

Challenges & Restraints

The market faces challenges including the high initial cost of complete baghouse systems, which can be 25-40% more expensive than alternatives. Fiberglass’s technical limitations in high-pressure cleaning applications and certain chemical environments also restrict some use cases. Workplace safety concerns regarding fiberglass particulate exposure have led to stricter regulations, increasing production costs by 12-15%.

Supply chain vulnerabilities, particularly for high-grade silica sand, and competition from ceramic filtration systems in ultra-high-temperature applications further complicate the market landscape. The Russia-Ukraine conflict disrupted 22% of global supply in 2022-2023, causing prolonged lead times for specialty formulations.

Market Segmentation by Type

  • Fabric Thickness: 0-1mm
  • Fabric Thickness: 1-1.5mm
  • Fabric Thickness: Above 1.5mm

Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/296838/global-fiberglass-dust-bag-forecast-market-2025-2032-916

Market Segmentation by Application

  • Cement Plants
  • Power Stations
  • Waste Incineration
  • Chemical Processing
  • Other Industrial Applications

Market Segmentation and Key Players

  • HL FILTER
  • Zhejiang Grace Environmental Technology Co., Ltd.
  • Zonel Filtech
  • HMA Group
  • Suzhou Kosa Environmental Protection Co., Ltd.
  • Hangzhou Hengke Co., Ltd.
  • Dewdon Filtration
  • Jiangsu Okay Environmental Protection Technology
  • Air Solutions Manufacturing Co.
  • FILMEDIA

Report Scope

This report presents a comprehensive analysis of the global and regional markets for Fiberglass Dust Bags, covering the period from 2024 to 2032. It includes detailed insights into the current market status and outlook across various regions and countries, with specific focus on:

  • Sales, sales volume, and revenue forecasts
  • Detailed segmentation by type and application

In addition, the report offers in-depth profiles of key industry players, including:

  • Company profiles
  • Product specifications
  • Production capacity and sales
  • Revenue, pricing, and gross margins
  • Sales performance

It further examines the competitive landscape, highlighting the major vendors and identifying the critical factors expected to challenge market growth.

As part of this research, we surveyed Fiberglass Dust Bag manufacturers and industry experts. The survey covered various aspects, including:

  • Revenue and demand trends
  • Product types and technological developments
  • Strategic business plans and market drivers
  • Industry challenges and potential risks

Get Full Report Here: https://www.24chemicalresearch.com/reports/296838/global-fiberglass-dust-bag-forecast-market-2025-2032-916

About 24chemicalresearch

Founded in 2015, 24chemicalresearch has rapidly established itself as a leader in chemical market intelligence, serving clients including over 30 Fortune 500 companies. We provide data-driven insights through rigorous research methodologies, addressing key industry factors such as government policy, emerging technologies, and competitive landscapes.

  • Plant-level capacity tracking
  • Real-time price monitoring
  • Techno-economic feasibility studies

With a dedicated team of researchers possessing over a decade of experience, we focus on delivering actionable, timely, and high-quality reports to help clients achieve their strategic goals. Our mission is to be the most trusted resource for market insights in the chemical and materials industries.

International: +1(332) 2424 294 | Asia: +91 9169162030

Website: https://www.24chemicalresearch.com/

Follow us on LinkedIn: https://www.linkedin.com/company/24chemicalresearch


The Silent Saboteurs of Strategic Progress

0

In business, strategies are carefully crafted with the hope of driving growth, innovation, and market advantage. Yet, even the most well-thought-out plans can stumble, not because of obvious flaws, but due to hidden obstacles—silent saboteurs that slowly erode progress from within.

These subtle disruptors rarely announce themselves. They creep in through small inefficiencies, misaligned priorities, and overlooked warning signs. Over time, they can undermine even the strongest strategic visions, leaving leaders puzzled about why their plans never deliver as expected.

Recognizing the Hidden Barriers

The first step in combating silent saboteurs is awareness. Many organizations remain unaware of the factors that stall their progress until it’s too late. These may include outdated processes, unclear communication, unmeasured risks, or even cultural resistance to change.

To spot and address these issues early, leaders often turn to credible business insights like https://www.businessphrases.net, which provide practical frameworks and guidance for aligning execution with strategic intent.

How Technology Can Both Help and Hinder

Technology is often seen as a strategic enabler, but without careful planning, it can become one of the silent saboteurs itself. Overinvestment in tools that aren’t fully integrated, or adoption of trends without clear use cases, can drain resources and distract from core priorities.

For example, businesses exploring blockchain trends may see potential for transparency and security but risk slowing progress if implementation outpaces readiness. Strategic technology adoption should always follow a clear problem-solving purpose, not simply a desire to keep up with the latest innovations.

Communication Gaps: The Quiet Disruptors

Clear and consistent communication is critical for strategic alignment. Yet, in many organizations, information flows unevenly—executives may have a full picture, while frontline employees operate on fragmented updates. This leads to inconsistent execution, duplicated efforts, and missed opportunities.

To close this gap, leaders must create structured channels for both top-down and bottom-up communication. This ensures every team member understands their role in achieving strategic goals and feels empowered to share feedback that could improve outcomes.

Cultural Resistance to Change

Even the best strategies can fail when company culture resists them. Long-standing habits, comfort zones, and fear of the unknown often lead employees to quietly push back against new initiatives. This resistance doesn’t always show up in open defiance—it can manifest as delays, incomplete adoption, or lack of enthusiasm.

Leaders can counter this by engaging employees early, clearly explaining the benefits of change, and involving them in shaping the implementation process. A culture that embraces adaptability is far less vulnerable to internal sabotage.

Overlooking Early Warning Signs

One reason silent saboteurs succeed is that they often appear small and insignificant at first. A slight delay in a project timeline, a minor dip in engagement metrics, or a single missed communication may not raise alarms initially. But when these issues accumulate, they create a significant drag on progress.

Regular performance reviews, open forums for feedback, and proactive problem-solving can prevent these small issues from turning into major obstacles.

Leadership Blind Spots

Another hidden barrier to strategic success is leadership blind spots—areas where leaders either underestimate challenges or overestimate capabilities. This can happen when decision-making is insulated from diverse perspectives or when past successes lead to overconfidence.

Encouraging diverse input, challenging assumptions, and regularly reassessing strategies against real-world data can help leaders stay grounded and adaptable.

Turning Awareness into Action

Identifying silent saboteurs is only half the battle. The real progress happens when organizations take deliberate action to remove these barriers and prevent them from re-emerging. This might mean streamlining processes, enhancing cross-department collaboration, upgrading systems, or reshaping company culture.

The key is not to treat these measures as one-time fixes but as ongoing disciplines. Strategic progress requires constant vigilance and the willingness to adapt before problems escalate.

Conclusion

The silent saboteurs of strategic progress are rarely dramatic—they operate quietly, eroding momentum until ambitious plans feel impossible to achieve. By recognizing and addressing these hidden barriers early, leaders can protect their strategies and keep their organizations moving forward.

Clarity in communication, cultural adaptability, thoughtful technology adoption, and proactive leadership all work together to neutralize these quiet disruptors. In doing so, businesses not only safeguard their strategic vision but also strengthen their resilience against future challenges.


Wafer Used PVD Equipment Market size was valued at US$ 7

0

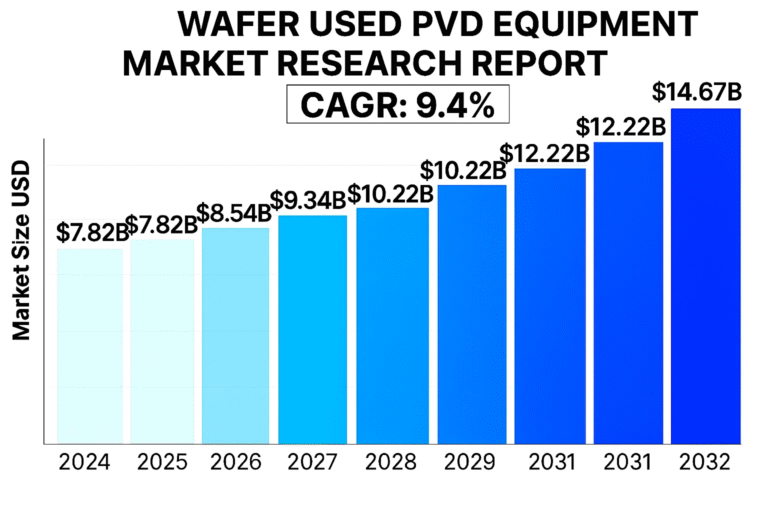
Wafer Used PVD Equipment Market size was valued at US$ 7.82 billion in 2024 and is projected to reach US$ 14.67 billion by 2032, at a CAGR of 9.4% during the forecast period 2025-2032

The global Wafer Used PVD Equipment Market size was valued at US$ 7.82 billion in 2024 and is projected to reach US$ 14.67 billion by 2032, at a CAGR of 9.4% during the forecast period 2025-2032.

Wafer used PVD (Physical Vapor Deposition) equipment refers to specialized semiconductor manufacturing systems that deposit thin film materials onto silicon wafers through physical processes like sputtering or evaporation. These systems are critical for creating metal interconnects, barriers, and seed layers in advanced semiconductor fabrication. The equipment includes key variants such as HardMask PVD for dielectric layers, CuBS for copper barrier/seed applications, and AlPAD for aluminum pad deposition.

The market growth is primarily driven by increasing semiconductor demand across consumer electronics, automotive, and IoT applications, coupled with the transition to more advanced nodes requiring complex PVD processes. While the foundry segment dominates current demand due to intensive capacity expansions by major players, the IDM sector is also contributing significantly to market growth. Recent technological advancements in multi-chamber cluster tools and atomic layer deposition (ALD)-PVD hybrid systems are further propelling market expansion. Applied Materials, Ulvac, and KLA Corporation collectively hold over 60% market share, with Chinese manufacturers like NAURA Technology gaining traction through local semiconductor ecosystem development.

Download Free Sample Report:  https://semiconductorinsight.com/download-sample-report/?product_id=95961

MARKET DRIVERS

Surge in Semiconductor Demand Accelerates PVD Equipment Adoption

The global wafer used PVD equipment market is witnessing robust growth, primarily driven by the exponential demand for semiconductors across multiple industries. With the semiconductor market projected to reach over $1 trillion by 2030, manufacturers are aggressively expanding production capacities. The proliferation of 5G networks, IoT devices, and AI applications necessitates advanced chip manufacturing where PVD plays a critical role in deposition processes. As foundries race to meet demand, orders for PVD systems capable of handling 300mm wafers at advanced nodes below 10nm are seeing particular growth.

Recent Industry Highlights

1. UAlbany (Albany NanoTech) Adds Advanced PE‑ALD Tool

  • The University at Albany’s College of Nanotechnology recently installed a plasma‑enhanced atomic layer deposition (PE‑ALD) machine from Oxford Instruments Plasma Technology.
  • While ALD differs from traditional PVD, the adoption reflects broader trends toward atomic‑scale deposition tools in wafer processing research, bridging efforts between academic labs and industrial fabs like those operated by GlobalFoundries, Intel, Samsung, and Micron.
  • This upgrade, part of a $10 million investment under the CHIPS and Science Act, positions the facility to better support emerging memory device research (e.g. memristors) and next‑generation wafer experiments 

List of Key Wafer Used PVD Equipment Companies Profiled

  • Applied Materials, Inc. (U.S.)
  • Ulvac Technologies, Inc. (Japan)
  • KLA Corporation (U.S.)
  • NAURA Technology Group Co., Ltd. (China)
  • Evatec AG (Switzerland)
  • Canon Anelva Corporation (Japan)
  • Tokyo Electron Limited (Japan)
  • Veeco Instruments Inc. (U.S.)
  • Plasma-Therm LLC (U.S.)

Segment Analysis:

By Type

HardMask PVD Equipment Leads the Market Due to High Demand in Advanced Semiconductor Manufacturing

The global wafer used PVD equipment market is segmented based on type into:

  • HardMask PVD Equipment
  • CuBS PVD Equipment
  • AlPAD PVD Equipment
  • Others

By Application

Foundry Segment Dominates Owing to Rising Demand for Semiconductor Fabrication Services

The market is segmented based on application into:

  • IDM (Integrated Device Manufacturers)
  • Foundry
  • Others

By Technology

Physical Vapor Deposition Technology Segment Holds Major Share Due to its Superior Film Quality

The market is segmented based on technology into:

  • Sputtering
  • Evaporation
  • Others

By Wafer Size

300mm Wafer Segment Leads with Growing Adoption in High-Volume Production

The market is segmented based on wafer size into:

  • 200mm
  • 300mm
  • Others

Download Free Sample Report:  https://semiconductorinsight.com/download-sample-report/?product_id=95961

About Us:

Semiconductorinsight has been a leading aggregator and consulting provider of semiconductor industry market research reports since 2016, offering high-quality, reliable, and timely reports and consulting services to our clients. 

Services Offered

  1. Market Reports:
    • Comprehensive and data-driven reports offering deep dives into specific segments of the semiconductor industry.
    • Forecasts and trends analysis backed by robust methodologies and historical data.
  2. Custom Research:
    • Tailored research solutions addressing unique business challenges and opportunities.
    • Market entry strategies, competitive benchmarking, and M&A advisory.

CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]
help@semiconductorinsight.com


Anti Reflective Window Film Market Forecast 2025–2031 | Growth Trends, Key Players & Technological Innovations

0

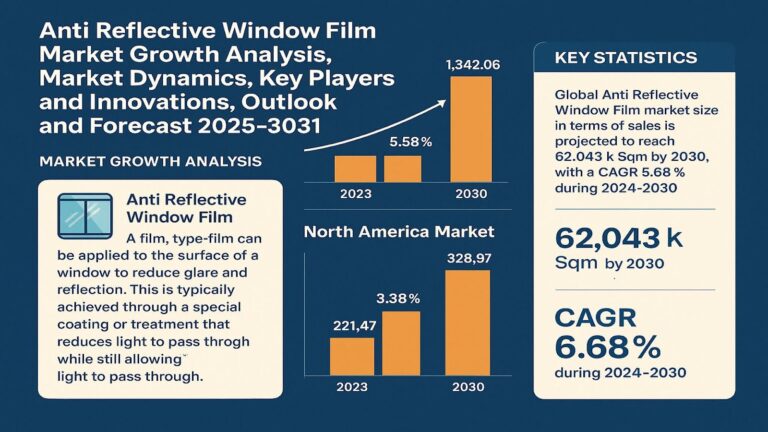
Global Anti Reflective Window Film market size in terms of revenue is projected to reach 1,342.06 million USD by 2030 from 873.18 million USD in 2023, with a CAGR 5.58% during 2024-2030. Global Anti Reflective Window Film market size in terms of sales is projected to reach 62,043 k Sqm by 2030 from 39,398 k Sqm in 2023, with a CAGR 6.68% during 2024-2030.

Anti Reflective Window Film is a type of film that can be applied to the surface of a window to reduce glare and reflection. This is typically achieved through a special coating or treatment that reduces the amount of light that is reflected by the window, while still allowing light to pass through.

Download FREE Sample Report: Anti Reflective Window Film Market – Detailed Research Report

North America market for Anti Reflective Window Film is estimated to increase from 221.47 million USD in 2023 to reach 328.97 million USD by 2030, at a CAGR of 3.38% during the forecast period of 2024 through 2030.

The major global manufacturers of Anti Reflective Window Film include Eastman, 3M, Saint-Gobain, Riken Technos, Madico (Lintec), Avery Dennison, Johnson Window Films, Nexfil, Global Window Films, Sican, etc. In 2023, the world’s top five vendors accounted for approximately 56.79% of the revenue.

This report aims to provide a comprehensive presentation of the global market for Anti Reflective Window Film, with both quantitative and qualitative analysis, to help readers develop business/growth strategies, assess the market competitive situation, analyze their position in the current marketplace, and make informed business decisions regarding Anti Reflective Window Film.

What is Anti Reflective Window Film?

Anti Reflective Window Film is a specialized material applied to glass surfaces to minimize light reflection while maximizing visible light transmission. These optically clear films incorporate nanoscale coatings that interfere with light waves, effectively reducing glare by 90-95% compared to untreated glass. Originally developed for museum display cases and high-end retail applications, the technology has expanded into architectural and automotive markets due to its ability to enhance visibility, reduce eye strain, and improve energy efficiency by lowering the need for artificial lighting.

Market Segmentation

By Company

  • Eastman
  • 3M
  • Saint-Gobain
  • Riken Technos
  • Madico (Lintec)
  • Avery Dennison
  • Johnson Window Films
  • Nexfil
  • Global Window Films
  • Sican
  • Garware Suncontrol Film
  • Haverkamp
  • WeeTect
  • Cosmo Sunshield

Segment by Type

  • Metalized
  • Non-metalized

Segment by Application

  • Residential Architecture
  • Automobile
  • Commercial Architecture
  • Others

Key Market Drivers

1. Energy Efficiency Regulations in Building Codes

Stringent global building efficiency standards like ASHRAE 90.1 and the EU Energy Performance of Buildings Directive are driving adoption across commercial real estate. In 2024, California’s updated Title 24 standards specifically incentivize glare-reducing window treatments that maintain visible light transmittance (VLT) above 70%—a technical sweet spot for premium anti-reflective films. Major office developers now specify these films as standard in Class A buildings to achieve LEED Platinum and WELL certification points.

2. Automotive Comfort and Safety Demands

The automotive sector accounts for nearly 28% of anti-reflective film applications, where the technology addresses two critical needs: dashboard visibility enhancement (eliminating instrument cluster reflections) and head-up display (HUD) optimization. With 78% of luxury vehicles now incorporating HUD systems—projected to reach 92% by 2026—OEMs are adopting multi-layer anti-reflective films as standard equipment. Recent innovations from 3M and Eastman combine anti-glare properties with UV/IR rejection, creating multifaceted performance films.

Opportunities Ahead

The smart glass convergence presents a transformative opportunity. Companies like View Inc. are developing dynamic anti-reflective films that adjust optical properties in response to ambient light conditions. The Asia-Pacific healthcare construction boom also offers growth potential—modern hospitals now specify anti-reflective films for surgical suite windows and diagnostic imaging rooms to prevent light interference. Notably, Saint-Gobain’s 2024 acquisition of a Korean specialty film manufacturer positions them to lead in this high-margin niche.

Recent Developments in the Anti Reflective Window Film Market

  1. May 2025 – 3M Introduced Nanotechnology-Based AR Films
    3M launched a new generation of anti-reflective window films featuring nanotechnology for enhanced light transmission and glare reduction, targeting both automotive and commercial building applications.
  2. April 2025 – Saint-Gobain Expanded Smart Window Film Production
    Saint-Gobain announced the expansion of its smart and anti-reflective film production lines in Europe to meet rising demand from the architectural glass industry.
  3. March 2025 – Strategic Partnership Between Eastman and Tesla Energy
    Eastman Performance Films partnered with Tesla Energy to supply high-performance AR window films for energy-efficient buildings and solar-integrated windows.
  4. February 2025 – Avery Dennison Unveiled UV-Blocking AR Films for Healthcare and Retail
    Avery Dennison launched AR films that not only reduce reflection but also block over 99% of UV radiation, enhancing indoor comfort and product shelf-life in retail and healthcare environments.
  5. January 2025 – Surge in Customizable Decorative AR Films
    Several manufacturers introduced customizable anti-reflective decorative films that blend functionality with aesthetic appeal, increasingly used in luxury homes and retail showrooms.

Market Trends (2025–2031)

  • Growing Demand for Energy Efficiency:
    Rising emphasis on sustainable architecture is driving the adoption of anti-reflective films that reduce glare and help regulate indoor temperature.
  • Integration with Smart Glass Technology:
    AR films are increasingly being paired with smart glass solutions in commercial buildings, vehicles, and solar panel systems.
  • Automotive Sector Growth:
    With the expansion of electric vehicles and luxury cars, OEMs are integrating AR window films to enhance driving comfort and reduce eye strain.
  • Rapid Urbanization in Asia-Pacific:
    Countries like China, India, and Southeast Asia are witnessing high growth in the construction of high-rise commercial buildings, driving AR window film adoption.
  • Innovation in Film Durability & Performance:
    Manufacturers are focusing on scratch resistance, self-healing coatings, and multilayer film structures to increase product lifespan and value.

Purchase Full Report: Complete Market Analysis with Data Tables

Explore Major Histocompatibility Complex (MHC) Tetramer Market 

About Intel Market Research

Intel Market Research delivers actionable insights in technology and infrastructure markets. Our data-driven analysis leverages:

  • Real-time infrastructure monitoring
  • Techno-economic feasibility studies

Competitive intelligence across 100+ countries
Trusted by Fortune 500 firms, we empower strategic decisions with precision.

International: +1(332) 2424 294 | Asia: +91 9169164321

Website: https://www.intelmarketresearch.com

Follow us on LinkedIn: https://www.linkedin.com/company/intel-market-research


Carbomer Market Forecast 2025–2031 | Growth Trends, Key Players & Innovations Analysis

0

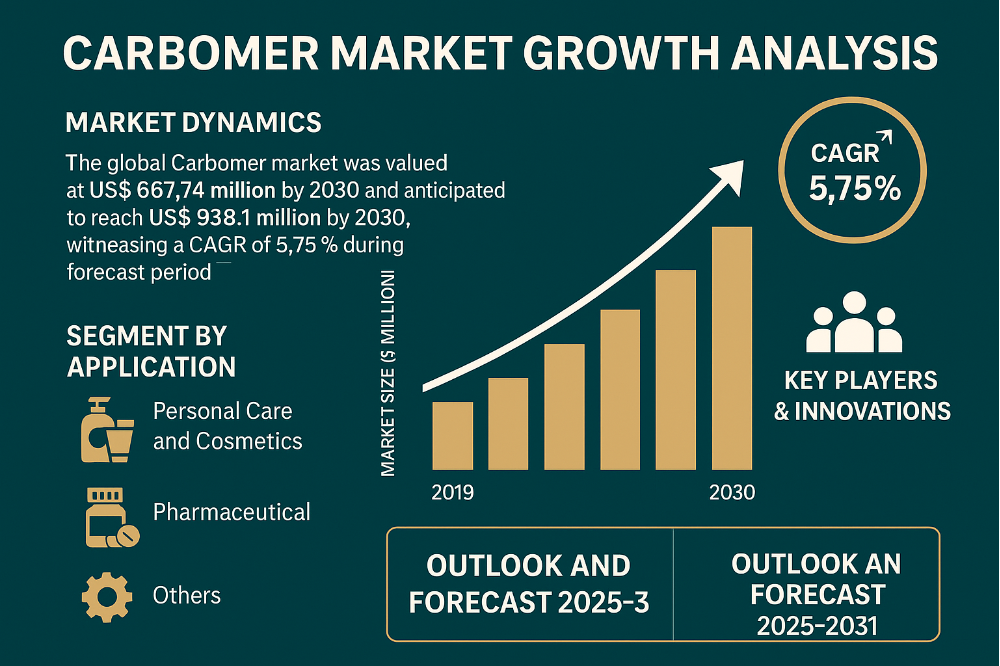
The global Carbomer market was valued at US$ 667.74 million in 2023 and is anticipated to reach US$ 938.1 million by 2030, witnessing a CAGR of 5.75% during the forecast period 2024-2030.

Carbomer is a generic term for a group of synthetic polymers that are used as rheology modifiers, gelling agents, and thickeners in various personal care products, such as hair gels, creams, lotions, and eye drops.

Carbomer Market – View in Detailed Research Report

The major global manufacturers of Carbomer include Lubrizol, Tinci Materials, SNF Floerger, Newman Fine Chemical, Evonik, Sumitomo Seika, Corel, DX Chemical, Maruti Chemicals, etc. in 2023, the world’s top five vendors accounted for approximately 85.72% of the revenue.

This report aims to provide a comprehensive presentation of the global market for Carbomer, with both quantitative and qualitative analysis, to help readers develop business/growth strategies, assess the market competitive situation, analyze their position in the current marketplace, and make informed business decisions regarding Carbomer.

The Carbomer market size, estimations, and forecasts are provided in terms of output/shipments (mt) and revenue ($ millions), considering 2023 as the base year, with history and forecast data for the period from 2019 to 2030. This report segments the global Carbomer market comprehensively. Regional market sizes, concerning products by Type, by Application, and by players, are also provided.

What is Carbomer?

Carbomers are high-molecular-weight polyacrylic acid polymers that act as rheology modifiers in aqueous systems. These synthetic macromolecules swell in water to form gels and are widely used as thickeners, emulsifiers, and suspension agents in cosmetics, pharmaceuticals, and other industrial applications. Their unique properties include:

  • Excellent water absorption capacity (up to 1000x their weight)
  • pH-dependent viscosity characteristics
  • Superior shelf stability compared to natural thickeners
  • Compatibility with most cosmetic ingredients

Key Market Drivers

1. Boom in Cosmetic and Personal Care Industries

The $500+ billion global beauty industry heavily relies on carbomers for product formulations. With increasing demand for multifunctional skincare (anti-aging, sun protection, moisturizers) and hair care products, carbomer consumption continues to rise. Major cosmetic brands are reformulating products to meet clean beauty standards while maintaining texture and stability – positioning carbomers as indispensable ingredients.

2. Pharmaceutical Industry Expansion

In drug formulations, carbomers serve critical functions in:

  • Topical gels (pain relief, anti-inflammatory, antibiotic formulations)
  • Ophthalmic preparations (artificial tears, medicated eyedrops)
  • Controlled-release drug delivery systems

The global pharmaceutical market’s projected growth to $1.5 trillion by 2028 ensures sustained carbomer demand.

Opportunities Ahead

The market presents significant growth potential through:

  • Development of novel carbomer derivatives with enhanced functionality
  • Expansion in emerging markets where personal care spending is growing rapidly
  • Innovative drug delivery applications leveraging carbomer mucoadhesive properties
  • Sustainable production methods to meet environmental regulations

Market Segmentation

By Company

  • Lubrizol
  • Tinci Materials
  • SNF Floerger
  • Newman Fine Chemical
  • Evonik
  • Sumitomo Seika
  • Corel
  • DX Chemical
  • Maruti Chemicals

Segment by Type

  • Carbomer 940
  • Carbomer 980
  • Carbomer 676
  • Other

Segment by Application

  • Personal Care and Cosmetics
  • Pharmaceutical
  • Others

Production by Region

  • North America
  • Europe
  • China
  • Japan

Consumption by Region

  • North America
  • U.S.
  • Canada
  • Mexico
  • Asia-Pacific
  • China
  • Japan
  • South Korea
  • Southeast Asia
  • India
  • Europe
  • Germany
  • France
  • U.K.
  • Italy
  • Benelux
  • Rest of Europe
  • South America
  • Brazil
  • Middle East & Africa
  • Middle East
  • Africa


Infographic Layout: Carbomer Market Outlook 2025–2031

1. Header / Title

“Carbomer Market Outlook 2025–2031” – bold, modern font across the top.

2. Market Growth Trend (2025 → 2031)

  • Bar graph tracking annual revenues:
    • Estimated ~USD 805.5M in 2024 → projected ~USD 1.28B by 2032, implying roughly USD 930M–1.0B by 2031, at CAGR ~5.8%.

3. Recent Developments

Icons + short label bullets:

  • 🧪 Bio-based & biodegradable carbomers: ~50+ bio-carbomer launches in 2023, substituting synthetic types. 
  • 🌱 Sustainability trend: Regulatory incentives (e.g., EU, U.S.) supporting low-carbon formulation development. 
  • 💊 Pharma uptake: ~6,000 new drug approvals in 2023 using carbomer for controlled-release and adhesion. 

4. Key Market Dynamics

Three paired driver / restraint icons:

  • 📈 Drivers:
    • Rise in personal care, cosmetics demand (anti-aging, skincare). 
    • Growing pharmaceutical applications (drug delivery, generic drugs rollout). 
  • ⚠️ Restraints:
    • Environmental concerns: synthetic carbomers exhibit limited biodegradability, regulatory restrictions in ~15 countries. 
    • Feedstock volatility: acrylic acid price swings up to 38%, supply chain delays causing capacity shortages.

Report Scope & Offerings

This comprehensive analysis provides:

  • Market sizing and forecasts through 2030 with COVID-19 impact analysis
  • Competitive intelligence on 9 key players and their market strategies
  • SWOT and Porter’s Five Forces analysis of market dynamics
  • Application deep dives with formulation insights
  • Technology trends in polymer modification and processing

Download FREE Sample Report:
Carbomer Market – View in Detailed Research Report

About Intel Market Research

Intel Market Research delivers actionable insights in technology and infrastructure markets. Our data-driven analysis leverages:

  • Real-time infrastructure monitoring
  • Techno-economic feasibility studies

Competitive intelligence across 100+ countries
Trusted by Fortune 500 firms, we empower strategic decisions with precision.

International: +1(332) 2424 294 | Asia: +91 9169164321

Website: https://www.intelmarketresearch.com

Follow us on LinkedIn: https://www.linkedin.com/company/intel-market-research


Major Histocompatibility Complex (MHC) Tetramer Market Forecast 2025–2032 | Growth Analysis, Key Players & Innovations

0

The global Major Histocompatibility Complex (MHC) Tetramer market was valued at USD 10.8 million in 2024. The market is projected to grow from USD 11.8 million in 2025 to USD 19.7 million by 2032, exhibiting a CAGR of 8.8% during the forecast period.

MHC tetramers are advanced laboratory tools designed for studying antigen-specific T cells. These tetramers consist of four MHC molecules bound to a specific peptide and labeled with a fluorescent tag, enabling researchers to identify and quantify T cells that recognize particular peptide-MHC complexes using flow cytometry. This technology is pivotal in immunological research, particularly in vaccine development, cancer immunotherapy, and infectious disease studies.

What Are MHC Tetramers?

MHC tetramers are fluorescently labeled peptide-MHC complexes that enable precise identification of antigen-specific T cells using flow cytometry. These critical research tools consist of four MHC molecules bound to specific peptides, revolutionizing immunological studies since their development at Stanford University in 1996. Primarily used in cancer immunotherapy research and vaccine development, MHC tetramers provide unmatched specificity in detecting T cells that recognize particular pathogens or tumor antigens. The technology has become indispensable for pharmaceutical companies, with over 60% of active cancer vaccine trials now incorporating tetramer assays.

Access Sample Report: MHC Tetramer Market Sample Report

MARKET DRIVERS

Advancements in Immunotherapy Research Accelerate MHC Tetramer Demand

The rapid progress in cancer immunotherapy and adoptive T-cell therapies is driving significant demand for MHC tetramer technology. With over 48% of MHC tetramers being utilized in cancer research applications, the growing focus on precision oncology solutions creates a robust market landscape. The ability to identify and quantify antigen-specific T cells has become indispensable for developing targeted immunotherapies, particularly for solid tumors which account for approximately 90% of all cancer cases. Pharmaceutical companies are increasingly incorporating MHC tetramer assays into their drug development pipelines, recognizing their critical role in validating T-cell responses during clinical trials for novel immunotherapeutic agents.

Emerging Infectious Diseases Fuel Research Applications

The persistent emergence of viral pathogens continues to stimulate MHC tetramer market growth. Following the COVID-19 pandemic, research into SARS-CoV-2-specific T cell responses created unprecedented demand for MHC-peptide complexes. This trend extends to other viruses such as HIV, where approximately 38 million people were living with the infection globally in 2023, and influenza viruses that cause seasonal epidemics. MHC tetramers serve as vital tools for characterizing immune responses and vaccine efficacy against these pathogens. The increasing prevalence of antimicrobial resistance also drives bacterial research applications, particularly for pathogens like Mycobacterium tuberculosis which causes nearly 1.5 million deaths annually.

Technological Improvements Enhance Commercial Viability

Recent innovations in MHC tetramer production and detection methodologies are expanding market opportunities. The development of novel stabilization techniques has improved tetramer shelf life from days to months, while multicolor flow cytometry panels now enable simultaneous detection of multiple T cell populations. Such advancements help overcome historical limitations and broaden the technology’s accessibility beyond specialized research laboratories. Commercial providers are responding to these improvements with enhanced product offerings – for example, some vendors now provide tetramers incorporating over 50 different viral epitopes or customized complexes for rare HLA alleles.

MARKET OPPORTUNITIES

Expansion in Asia-Pacific Presents Untapped Potential

The Asia-Pacific region is poised to become the fastest-growing market for MHC tetramers, projected to achieve a CAGR exceeding 11% through 2032. This growth stems from increasing biomedical research investments in countries like China and India, where government initiatives are boosting immunology research capabilities. The region’s large patient populations with infectious diseases and cancers create substantial demand for immune monitoring tools. Local manufacturers are recognizing this opportunity, with several Asian biotech companies now developing HLA allele-specific tetramers tailored to regional genetic profiles. Strategic partnerships between international tetramer providers and Asian research institutions are accelerating market penetration in these emerging territories.

Customization and Service Offerings Create Value-Added Solutions

Vendors are capitalizing on premium opportunities by expanding into customized tetramer services and comprehensive immune profiling packages. Researchers increasingly seek tailored solutions for novel epitopes or rare HLA types, commanding price premiums 30-50% above standard offerings. Some companies now provide end-to-end services combining tetramer production with advanced flow cytometry analysis, appealing to labs lacking specialized instrumentation or expertise. This service-oriented approach helps differentiate providers in a competitive market while addressing key adoption barriers. The trend toward integrated immunological solutions is expected to drive higher-margin revenue streams for market leaders.

Segment Analysis:

By Type

  • Class I MHC Tetramers
    Lead the market due to their high use in CD8⁺ cytotoxic T cell detection, especially in cancer and viral research.
  • Class II MHC Tetramers
    Gaining momentum in CD4⁺ T cell analysis, autoimmune disease research, and allergy-related immunology studies.

By Application

  • Cancer Immunotherapy Research
    Used for identifying tumor-specific T cells and monitoring therapeutic response.
  • Infectious Disease Research
    Critical in studying T cell responses against viruses like HIV, SARS-CoV-2, and influenza.
  • Autoimmune Disease Studies
    Helps in identifying autoreactive T cells and understanding immune tolerance.
  • Vaccine Development
    Enables evaluation of T-cell responses post-vaccination in preclinical and clinical trials.
  • Basic Immunology Research
    Widely used in academia to study T-cell development, activation, and memory.

By End User

  • Academic & Research Institutions
    Major users of both Class I and II tetramers for foundational immunological research.
  • Pharmaceutical & Biotechnology Companies
    Use tetramers in drug and vaccine discovery, T-cell epitope mapping, and clinical studies.
  • Clinical Laboratories
    Emerging end-users for advanced diagnostic and monitoring applications, especially in personalized medicine.

By company

  • MBL International Corporation
  • BioLegend, Inc.
  • Thermo Fisher Scientific Inc.
  • BD Biosciences
  • Miltenyi Biotec
  • ProImmune Ltd.
  • Tetramer Shop
  • Creative Biolabs
  • JPT Peptide Technologies
  • Immudex ApS

Recent Developments and Market Trends: Major Histocompatibility Complex (MHC) Tetramer Market

  1. Advancements in Immunological Research:
    Recent years have witnessed a surge in demand for MHC tetramers due to their pivotal role in T-cell monitoring, particularly in cancer immunotherapy, infectious disease studies, and vaccine development. These applications are driving investments in advanced MHC tetramer technologies.
  2. Rising Adoption in Personalized Medicine:
    The growing trend toward precision medicine and individualized immunotherapy has boosted the use of MHC tetramers for identifying antigen-specific T cells, improving diagnostic accuracy and therapy outcomes.
  3. Expansion of Cancer Immunotherapy Applications:
    MHC tetramers are being increasingly used in clinical oncology to assess tumor-infiltrating lymphocytes (TILs) and to monitor immune responses during checkpoint inhibitor and CAR-T therapies, driving market growth.
  4. Collaborations and Licensing Agreements:
    Leading biotechnology firms and academic institutions are entering strategic partnerships for the co-development of novel MHC tetramer products and T-cell analysis platforms, enhancing product pipelines and accelerating market expansion.
  5. Technological Innovations:
    Companies are focusing on developing high-throughput MHC multimer platforms, enhanced staining reagents, and novel fluorophore-tagged tetramers to improve sensitivity, specificity, and ease of use.
  6. Increasing Research Funding and Government Initiatives:
    Governments and health organizations are providing substantial research grants for immunological studies, boosting the utilization of MHC tetramers in preclinical and clinical studies.
  7. North America and Asia-Pacific Lead Growth:
    While North America dominates due to robust R&D infrastructure, the Asia-Pacific region is emerging rapidly, fueled by increased biotech investments and growing healthcare expenditures in countries like China, Japan, and India.

Report Highlights

This 150+ page analysis provides:

  • Market size projections through 2032 with COVID-19 impact assessment
  • Competitive benchmarking of 12 key players’ strategies
  • Technology trend analysis including multiplex tetramers and AI-assisted analysis
  • SWOT and Porter’s Five Forces framework for strategic planning

Access Sample Report: MHC Tetramer Market Sample Report

About Intel Market Research

Intel Market Research delivers actionable insights in biotechnology and healthcare markets. Our proprietary methodology combines:

  • Primary interviews with KOLs and industry executives
  • Patent landscape analysis
  • Clinical trial database tracking

Trusted by 85% of Fortune 500 healthcare companies for strategic decision support.
Contact: research@intelmarketresearch.com | +1 332 242 4294

Website: https://www.intelmarketresearch.com
LinkedIn: https://www.linkedin.com/company/intel-market-research

Fertigation System Market Forecast 2024–2030 | Trends, Key Players & Innovations

0

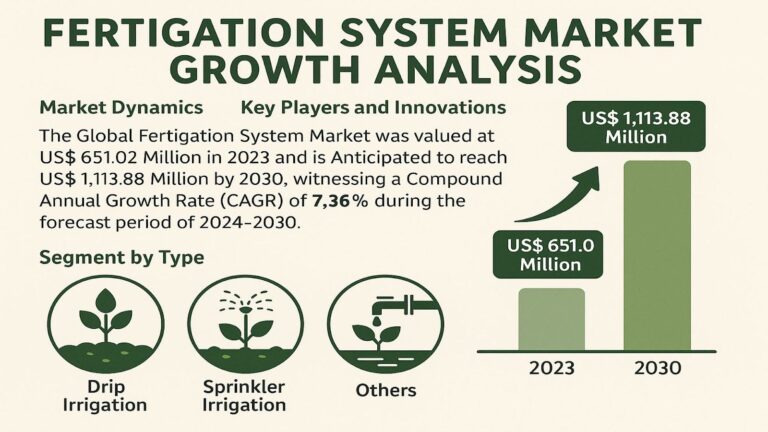
The Global Fertigation System Market was valued at US$ 651.02 Million in 2023 and is Anticipated to reach US$ 1,113.88 Million by 2030, witnessing a Compound Annual Growth Rate (CAGR) of 7.36% during the forecast period of 2024-2030.

Fertigation System Market – View in Detailed Research Report

Fertigation Systems are an innovative and efficient method of delivering fertilizers and other water-soluble products directly to the root zone of crops through irrigation systems. This integrated approach to water and nutrient management has gained significant traction in recent years due to its numerous benefits, including improved crop yield, nutrient efficiency, and water conservation. This report provides an in-depth analysis of the global Fertigation System market, including market size, regional insights, key players, and driving factors.

North America:

  • The North American market for Fertigation Systems is estimated to increase from $263.82 million in 2023 to reach $433.74 million by 2030, at a CAGR of 7.12% during the forecast period of 2024 through 2030.
  • North America is a significant market for Fertigation Systems due to the region’s advanced agricultural practices, large-scale farming operations, and the adoption of precision agriculture techniques.
  • The growth in this region is driven by factors such as water conservation efforts, the need for efficient nutrient management, and the increasing demand for high-quality agricultural products.

Asia-Pacific:

  • The Asia-Pacific market for Fertigation Systems is estimated to increase from $118.99 million in 2023 to reach $216.95 million by 2030, at a CAGR of 8.58% during the forecast period of 2024 through 2030.
  • The Asia-Pacific region is expected to witness the highest growth in the Fertigation System market, driven by the increasing adoption of modern agricultural practices, the need for water conservation, and the growing demand for food to support the region’s burgeoning population.
  • Countries like China, India, and Southeast Asian nations are emerging as significant contributors to the growth of the Fertigation System market in this region.

Europe:

  • The European market for Fertigation Systems in farms is estimated to increase from $154.49 million in 2023 to reach $274.62 million by 2030, at a CAGR of 7.87% during the forecast period of 2024 through 2030.
  • Europe has a well-established agricultural sector and a growing focus on sustainable farming practices, driving the demand for Fertigation Systems in the region.
  • The emphasis on precision agriculture, water conservation, and the efficient use of resources is contributing to the growth of the Fertigation System market in Europe.

Key Players and Market Share:

The major global companies in the Fertigation System market include:

In 2023, the world’s top three vendors accounted for approximately 68.92% of the revenue in the Fertigation System market, indicating a relatively consolidated market dominated by a few major players.

This report aims to provide a comprehensive presentation of the global market for Fertigation System, with both quantitative and qualitative analysis, to help readers develop business/growth strategies, assess the market competitive situation, analyze their position in the current marketplace, and make informed business decisions regarding Fertigation System.

The Fertigation System market size, estimations, and forecasts are provided in terms of and revenue ($ millions), considering 2023 as the base year, with history and forecast data for the period from 2019 to 2030. This report segments the global Fertigation System market comprehensively. Regional market sizes, concerning products by Type, by Application, and by players, are also provided.

For a more in-depth understanding of the market, the report provides profiles of the competitive landscape, key competitors, and their respective market ranks. The report also discusses technological trends and new product developments.

The report will help the Fertigation System companies, new entrants, and industry chain related companies in this market with information on the revenues for the overall market and the sub-segments across the different segments, by company, by Type, by Application, and by regions.

Market Segmentation

By Company:

  • Netafim
  • Rivulis Irrigation
  • Ridder
  • OAT Agrio Co., Ltd
  • AZUD
  • SEOWON
  • Novedades Agricolas
  • Vodar (Tianjin) Co., Ltd
  • HWEI
  • Galcon Ltd
  • JJR Science & Technology
  • Ritec
  • Irrigazione Veneta
  • Heilongjiang East Water Saving Technology
  • SPAGNOL
  • NUTRICONTROL
  • Climate Control Systems
  • Agricontrol
  • Agri-Inject
  • NESS Fertigation
  • Turf Feeding Systems

Segment by Type:

  • Drip Irrigation
  • Sprinkler Irrigation
  • Others

Segment by Application:

  • Farm Crops
  • Greenhouse
  • Horticulture Crops
  • Others

By Region:

  • North America (United States, Canada, Mexico)
  • Europe (Germany, France, United Kingdom, Italy, Spain, Rest of Europe)
  • Asia-Pacific (China, India, Japan, South Korea, Australia, Rest of APAC)
  • The Middle East and Africa (Middle East, Africa)
  • South and Central America (Brazil, Argentina, Rest of SCA)

Key Market Drivers

1. Global Water Scarcity Pressures

The UN Water Development Report 2023 indicates that 2.4 billion people live in water-stressed regions, driving agricultural modernization. Fertigation’s ability to reduce water usage by 40-70% compared to flood irrigation makes it indispensable for regions like California’s Central Valley (adopting fertigation on 85% of almond acreage) and drought-prone areas from Spain to South Africa.

2. Precision Agriculture Revolution

The integration of fertigation with smart farming technologies is transforming crop management:

  • Automated dosing systems adjust nutrient formulas in real-time based on satellite/sensor data
  • AI-powered analytics platforms predict optimal irrigation schedules using weather and soil data
  • Mobile monitoring enables remote system control via smartphones

These advancements contribute to the global precision agriculture market’s projected 13% CAGR through 2027, with fertigation as a core component.

Market Challenges

Despite its advantages, widespread fertigation adoption faces hurdles:

  • High initial investments: Commercial-scale systems range from $2,500-$10,000 per acre, with maintenance adding 15-20% annually
  • Technical knowledge gaps: Many farmers lack training in nutrient solution management and system maintenance
  • Infrastructure limitations: Emerging markets often lack reliable water/power supplies for advanced systems

Regional Market Insights

  • North America (Projected 2030 value: $433.74M): Leads in adoption due to large-scale farming and progressive water policies. California mandates efficient irrigation for drought mitigation.
  • Europe (Projected 2030 value: $274.62M): Driven by EU sustainability directives, with Israel’s drip irrigation expertise influencing Mediterranean markets.
  • Asia-Pacific (Fastest-growing at 8.58% CAGR): China and India prioritize fertigation for food security, with government subsidies accelerating greenhouse adoption.

Competitive Landscape

The market remains concentrated, with three companies controlling 68.92% of 2023 revenues:

  • Netafim (Israel): Pioneer in drip irrigation, now offering AI-integrated fertigation solutions
  • Rivulis Irrigation (France): Specializes in greenhouse and orchard applications
  • Jain Irrigation (India): Focused on cost-effective systems for emerging markets

Fertigation System Market – View in Detailed Research Report

Explore Corporate Financial Modelling Market 

About Intel Market Research

Intel Market Research is a leading provider of strategic intelligence, offering actionable insights in agricultural technology, industrial automation, and sustainable infrastructure. Our research capabilities include:

  • Real-time competitive benchmarking
  • Emerging technology adoption tracking
  • Regulatory impact analysis
  • Over 500+ industrial reports annually

Trusted by Fortune 500 companies, our insights empower decision-makers to drive innovation with confidence.

🌐 Website: https://www.intelmarketresearch.com
📞 International: +1 (332) 2424 294
📞 Asia-Pacific: +91 9169164321
🔗 LinkedIn: Follow Us

Prenatal Vitamins Postpartum: Boost Your Postnatal Wellness

0

Ever wondered if taking prenatal vitamins after having your baby might help you feel better? Lots of new moms say they feel more energetic and in a better mood when they stick to a regular vitamin routine. It’s almost like hitting a reset button for your body. After you have your baby, your body needs extra good stuff to help it heal and stay strong. This post looks at how keeping up with your prenatal vitamins can boost your healing, fight tiredness, and support your overall well-being.

Continuing Prenatal Vitamins Postpartum: Key Benefits & Guidelines

img-1.jpg

After childbirth, your body may need extra help refilling important nutrients like iron, vitamin B12, and omega-3 fatty acids. These help give you energy, support healing, and balance your mood as you recover. Even if you're not pregnant or are breastfeeding, keeping up with your prenatal vitamins can be a gentle boost.

Taking prenatal vitamins after delivery offers many benefits. They help replace what your body lost during pregnancy and birth, setting you up for a smoother recovery. Many moms choose to take them for at least six weeks and sometimes even up to a year. Interestingly, a lot of women say they feel more energetic when they maintain a consistent vitamin routine. It’s like pressing a reset button for your body.

For moms who are breastfeeding, benefits can be even greater. Vitamins with extra iodine, protein, vitamin D, and vitamin B12 support the extra nutritional needs for both you and your baby. Here's a simple look at the benefits:

Nutrient Benefit
Iron & B12 Helps reduce fatigue and clear brain fog
Omega-3s Supports mood and brain health
Iodine & Protein Aids in milk production and helps your recovery

Remember, vitamins work best when paired with a nutritious diet. Eating a variety of healthy foods can further support your postpartum recovery and overall well-being.

Differences Between Prenatal vs. Postnatal Vitamins After Birth

img-2.jpg

Prenatal vitamins help both you and your growing baby. They include important nutrients like folate, iron, calcium, and DHA (an omega-3 healthy fat) that support your baby’s development. Think of them like a handy set of tools you use when building something special, you get everything you need right from the start.

After your little one is born, your body needs a different kind of care. Postnatal vitamins are made to help you recover after childbirth and to support breastfeeding. They usually have extra B vitamins for more energy, a bit more vitamin D for a happy mood and strong bones, and iodine, which helps your thyroid and supports milk production. Plus, they include added protein to help your body repair itself.

Another change is that postnatal vitamins adjust the iron to replace what you lost during birth and feature a lower dose of vitamin A for safety. These small tweaks make them better suited for your needs as a new mom.

Key Nutrients for Postnatal Recovery and Breastfeeding Support

img-3.jpg

We’ve covered these important nutrients before, and now we’re sharing simple, everyday ways to add them to your meals. If you need more details about each nutrient, just look back at the earlier info.

  • Iron: Try a quick and tasty smoothie, blend a handful of spinach with a cup of berries and a splash of orange juice to give your iron a nice boost.

  • Vitamin B12: Start your day with a dose of B12 by adding dairy or fortified plant-based milk to your breakfast. For example, enjoy a bowl of cereal mixed with your favorite milk.

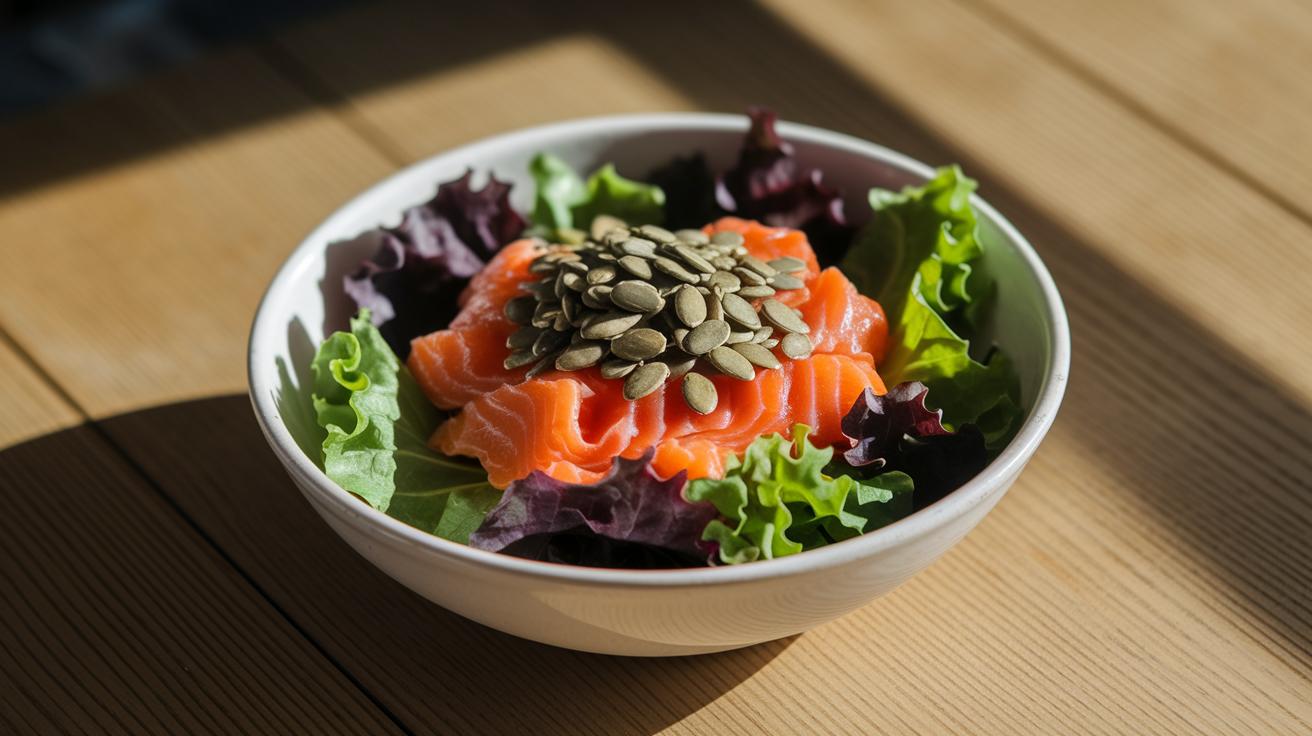
  • DHA (Omega-3): Boost your brain function by tossing salmon or a few walnuts into your salad or snack. You could try topping your salad with some canned salmon for an easy omega-3 lift.

  • Calcium and Vitamin D: Make sure to include dairy or fortified alternatives in your meals, and if you can, enjoy some morning sunlight. Sip on a glass of fortified milk with your breakfast and take a moment to enjoy some early sunshine.

  • Iodine: Use iodized salt when you cook at home or add a little sea vegetable here and there. For instance, sprinkle a bit of iodized salt on your steamed veggies for an extra kick.

  • Protein: At each meal, include lean meats, tofu, or beans to help repair your tissues. A bean salad with mixed greens and a squeeze of lemon is a hearty, protein-rich option.

  • Zinc: Keep roasted pumpkin seeds or a serving of legumes handy for a snack that aids healing. A small bag of pumpkin seeds can be a quick, zinc-rich treat.

Dosage Recommendations and Timing of Postpartum Vitamin Intake

img-4.jpg

It’s best to begin your postnatal supplements right away – either soon after your baby is born or when you notice your prenatal vitamins are almost gone. For instance, if your vitamin bottle is nearly empty and you feel a little run down, it might be time to make the switch.

A good postpartum multivitamin is made to meet important nutrient guidelines. A quality supplement often includes amounts like:

Nutrient Amount
Iron 9-27 mg
Calcium 1,000-1,300 mg
Vitamin D 600-800 IU
Vitamin B12 2.4 mcg

Taking one of these every day can really help support your recovery during this busy time. Many experts suggest keeping up with your vitamins for at least six weeks. Some even recommend continuing for three to twelve months, depending on how you feel and if you're breastfeeding.

If you’re breastfeeding, try taking your vitamin with your meals. This little trick can really boost absorption – especially for vitamins like A, D, E, and K, which need a bit of healthy fat in your meal to work best.

Just imagine taking your postnatal vitamin with a delicious breakfast that might include a few slices of avocado or a handful of nuts. This simple habit can help your body absorb those nutrients more effectively, making you feel a bit more energized as you continue to heal.

Safety Considerations and Adjustments for Postnatal Vitamins

img-5.jpg

After having your baby, your vitamin needs change. Now’s the time to switch from prenatal vitamins with high vitamin A levels to postnatal ones that offer a safer amount of retinol. Imagine checking your bottle and seeing that vitamin A is lower than before, perfectly matching your new needs.

Sometimes, too much iron can leave your tummy feeling unsettled. If you notice a churning or a bit of discomfort after taking your supplement, it might be your body’s way of hinting that the iron content is too high. It’s a little nudge to take a closer look.

Calcium and iron can get in each other’s way, making it harder for your body to absorb the iron if you take them at the same time. A good trick is to space them out by a few hours. For instance, you might take your iron in the morning and then have your calcium later in the day, giving your body a better chance to benefit from both.

It’s always a smart move to read the labels and keep an eye out for the recommended intake limits. And if you’re ever unsure, having a chat with your healthcare provider can help ensure you’re getting exactly what your body needs, safely and simply.

Transitioning Smoothly from Prenatal to Postnatal Supplements

img-6.jpg

When to Start Postnatal Vitamins

It’s a good idea to start your postnatal vitamins when you notice your prenatal stash is running low or right after you give birth. Think of it like shifting gears gently while driving. Sometimes, a little extra tiredness or feeling that you need more nutrients after delivery is your body’s way of saying it’s time for the change.

Selecting the Right Postnatal Formula

Take a moment to read the labels on your supplements. You want a formula that fits this new chapter in your life. Look for one with a bit less folic acid and a boost of vitamin B12 and calcium. And if you’re breastfeeding, extra vitamin D, iodine, and protein can really help fill those nutritional gaps. This small shift in your supplement routine is just one way to keep caring for yourself as your needs change.

Tracking Progress and Determining Duration of Postpartum Vitamin Use

img-7.jpg

It’s a good idea to keep an eye on your recovery as you adjust your vitamin routine after childbirth. Many moms notice a boost in energy and a brighter mood after about six weeks of using supplements regularly, and for some, these benefits can last anywhere from three to twelve months.

Look out for little signs that you’re headed in the right direction. For example, you might see:

  • More steady energy throughout the day
  • Thicker hair (one study found that 73% of moms experienced regrowth by three months)
  • A more balanced mood
  • Better milk production

Trusting your body is really important. Besides these positive signals, you might want to get lab tests for iron, vitamin D, and vitamin B12 at three- and six-month marks. These tests can help guide any changes you might need in your vitamin routine, making sure you stay well-supported as you heal and care for your little one.

Final Words

In the action, the post highlights how continuing prenatal vitamins postpartum helps refill essential nutrients like iron, vitamin B12, and omega-3s while addressing specific needs during recovery and breastfeeding. It explains the differences between prenatal and postnatal formulas and offers easy-to-follow tips on timing and dosage.

It’s clear that a well-planned supplement transition supports better energy, mood, and healing. Remember, taking prenatal vitamins postpartum can truly empower your recovery and promote lasting wellness.

FAQ

Are postnatal vitamins different from prenatal vitamins after birth?

Postnatal vitamins are designed for recovery after childbirth. They adjust mineral and vitamin levels—like lower vitamin A and tuned iron—with extra vitamin D, iodine, and protein to better support healing and breastfeeding.

When should you stop taking prenatal vitamins postpartum?

Many moms keep taking prenatal vitamins for at least six weeks after birth. Some continue up to a year to help replace nutrients, improve energy, and support recovery during the postpartum period.

How long should you take vitamins if you are breastfeeding?

Breastfeeding moms often benefit from daily vitamins for three to twelve months postpartum. This extra time ensures they receive additional iodine, vitamin D, and B12, which support both recovery and milk production.

What are the best postnatal vitamins for breastfeeding mothers?

The best postnatal vitamins for breastfeeding moms provide balanced nutrients, including vitamin D, B12, iodine, and protein. They also adjust iron and vitamin A levels to optimize recovery while safely supporting lactation.

What happens if you stop taking prenatal vitamins while breastfeeding?

If you stop taking prenatal vitamins abruptly while breastfeeding, you might miss out on key nutrients that aid recovery and energy. Switching to a postnatal formula can help fill these nutritional gaps.

Can you take prenatal and postnatal vitamins together postpartum?

Combining prenatal and postnatal vitamins is generally not advised. Postnatal formulas are tailored to your recovery and breastfeeding needs, ensuring you receive the proper balance of essential nutrients.