Thursday, October 8, 2026
Home Blog Page 75

Balancing Indulgence With Nutrition During Pregnancy: Bliss

0

Have you ever thought you could enjoy a little treat while keeping healthy during pregnancy? Picture savoring a slice of cake alongside a refreshing smoothie made with fresh berries and greens. It might seem tricky to balance cravings with healthy choices, but really, it comes down to being mindful with every meal.

This chat is all about how small swaps and easy meal planning can help you look after both your cravings and your baby’s growth. Have you ever noticed how a little change in your meal can make you feel so much more content?

Keep reading to discover how a balanced approach can make your pregnancy meals feel incredibly satisfying.

Comprehensive Balance: Indulgence and Nutrition in Pregnancy
img-1.jpg

Pregnancy nutrition matters at every stage, and you can still enjoy little treats while keeping you and your baby healthy. Think of it as savoring each bite with care, mixing indulgence with real, nutritious foods.

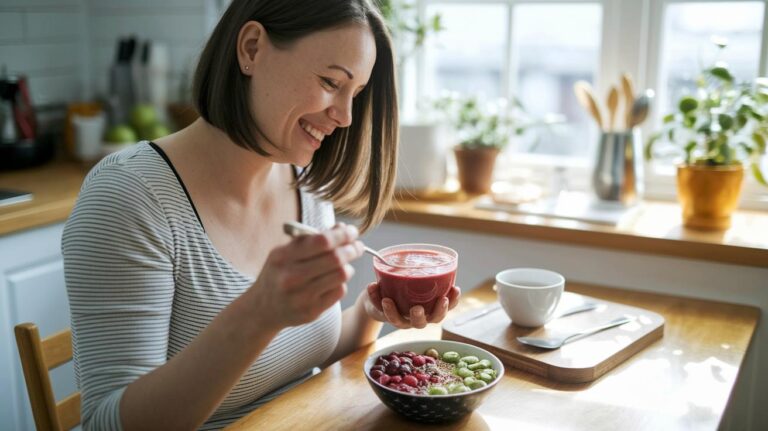
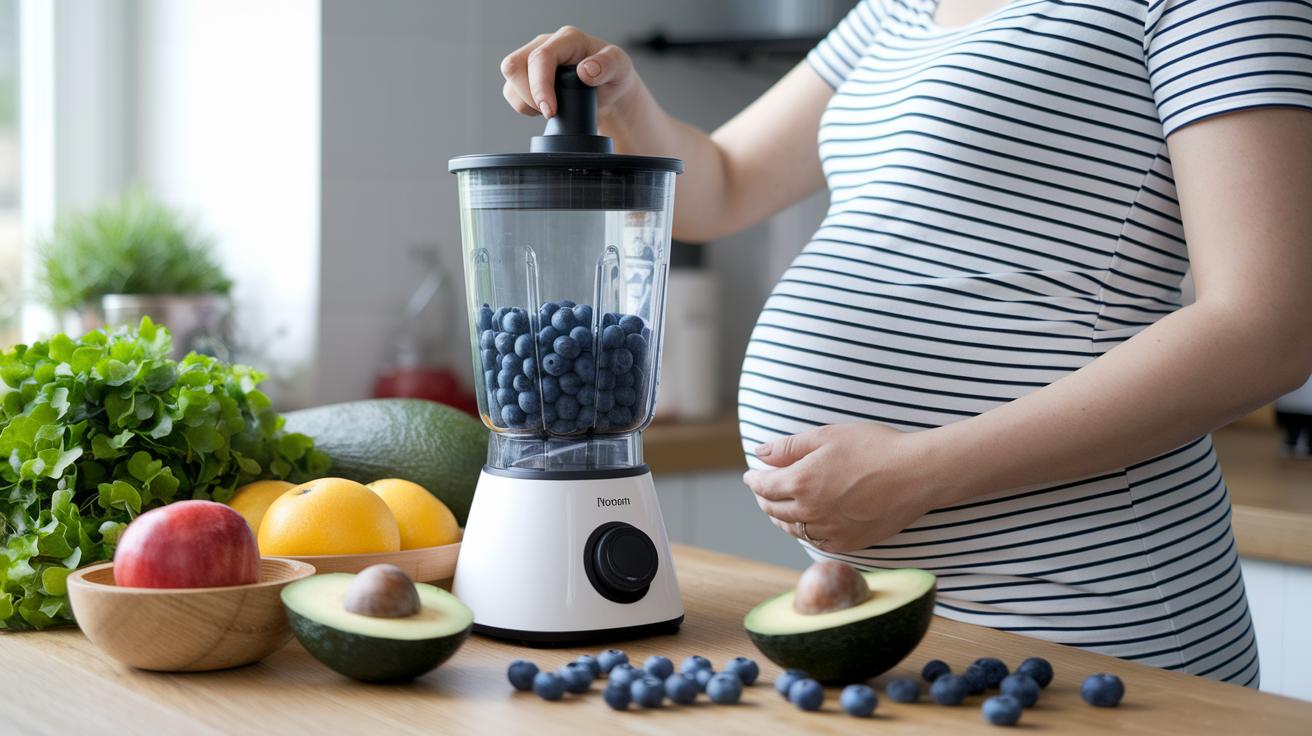
Instead of reaching for a processed snack, why not try making a fresh smoothie? Imagine a creamy mix of blueberries, avocado, and a splash of almond milk giving you a burst of energy and flavor. It’s a simple swap that feels both delicious and nourishing.

Many moms find that having five or six small meals throughout the day helps keep energy levels steady and can even ease the occasional nausea. Picture planning meals around whole grains, lean proteins like salmon, and a colorful mix of vegetables. This way, you get key nutrients like folate, iron, calcium, protein, fiber, and omega-3 fats that are important for both you and your baby.

It’s also completely okay to include a small treat now and then. A bit of dark chocolate or a spoonful of homemade fruit chutney can satisfy your sweet tooth while still fitting into your overall plan. This little indulgence shows that a balanced approach can support both your health and your little one’s development.

Every bite is a moment to care for yourself and your baby, making each meal a gentle celebration of nourishment and well-being.

Cravings Management and Mindful Eating for Maternal Health
img-2.jpg

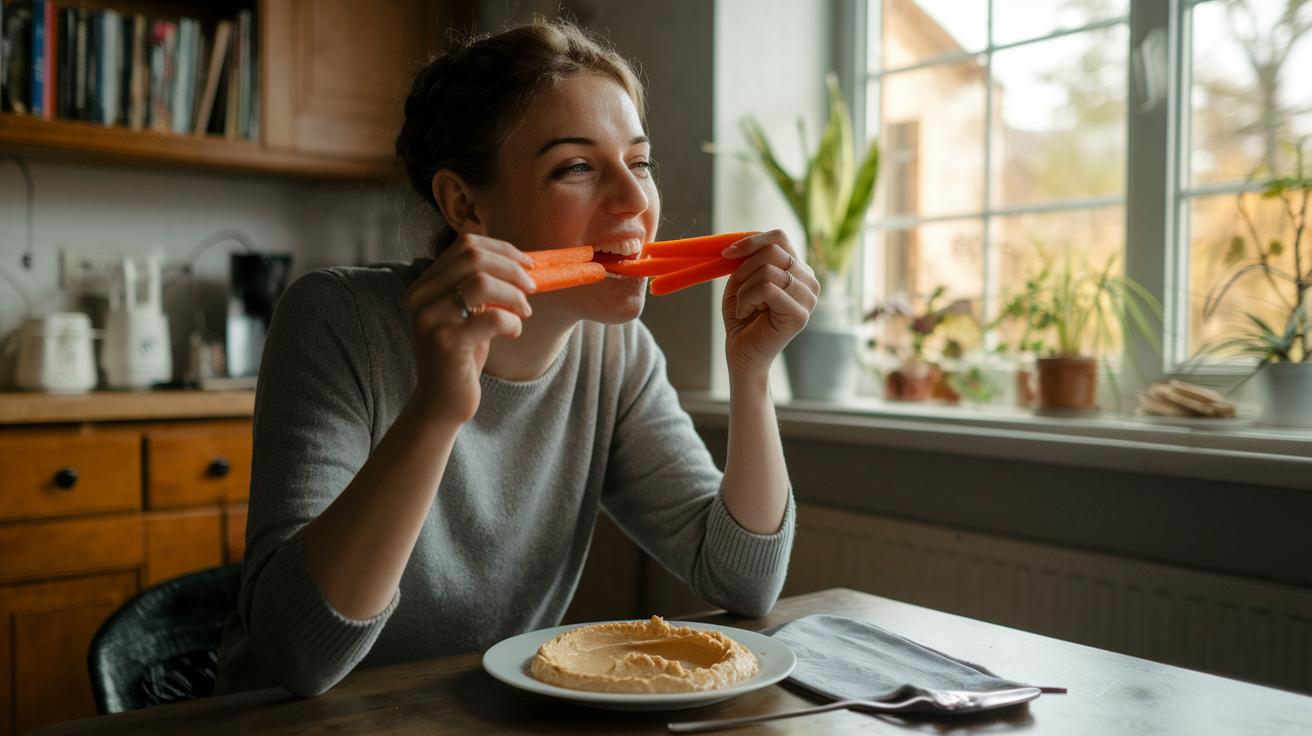
Before grabbing that extra treat, take a moment to pause. Enjoying your food means noticing every bite, whether you're munching on a fresh apple or savoring a square of dark chocolate. Imagine sitting down with a bowl of crisp carrot sticks dipped in a smooth, creamy hummus, a snack that's both delightful and good for you.

Eating five or six smaller meals during the day can help keep your blood sugar balanced and might even ease morning sickness. One mom shared how planning her snacks ahead of time made a difference: she kept mini portions of mixed nuts and a few pear slices ready for when cravings struck.

Why not try a new snack idea to change things up? Blend some mashed avocado with a little cocoa and a touch of natural sweetener to whip up a rich, dark chocolate mousse. This simple recipe turns a craving into a treat packed with nutrients.

Choosing the right food pairs can also boost the benefits you get. For instance, adding a squeeze of lemon to an iron-packed spinach salad helps your body absorb iron better, which supports both you and your baby.

  • Pause and think before you indulge
  • Enjoy each bite fully
  • Swap high-sugar snacks for options that offer vitamins and minerals

Using these mindful snacking tips can bring a fresh approach to balancing a treat with the care your body needs during pregnancy.

Structuring Expectant Mothers’ Healthy Eating Plan
img-3.jpg

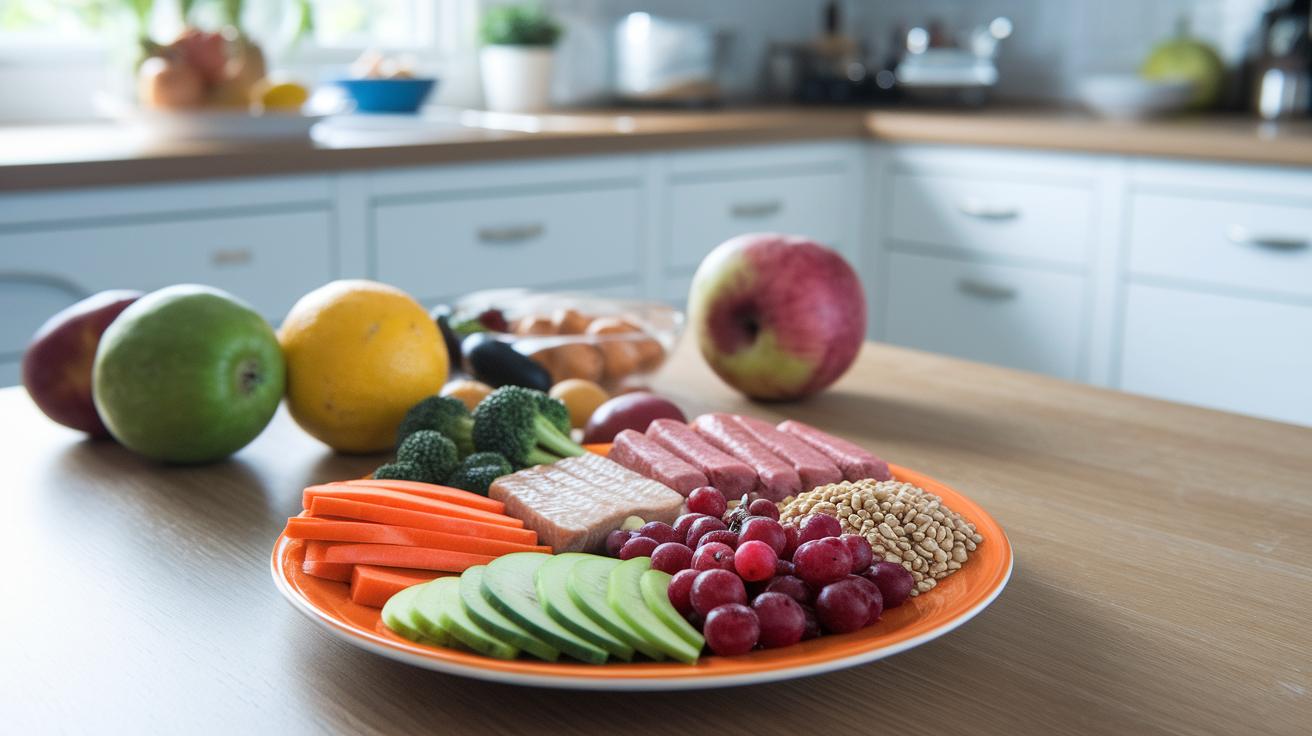
Plan your meals so you have three hearty meals and two healthy snacks each day. Imagine starting your morning with a breakfast of whole grains, protein, and fresh fruit that feels like a gentle hug. For lunch, think of a plate filled with about half veggies and fruit, a quarter lean protein, and a quarter whole grains. If you need a picture guide, check out MyPlate for Pregnancy. At dinner, mix in foods like salmon (great for DHA), legumes (packed with iron), and a side of avocado for a boost of healthy fats.

Think of your plate like a little roadmap: half colorful fruits and greens, one-quarter lean protein, and one-quarter whole grains. This simple idea helps your baby grow strong while keeping your energy steady. And don’t forget a dairy option or a good alternative to get that important calcium, especially as your body adapts to your baby's growing needs.

Keep water handy all day and try to sip about 2.5 to 3 liters. Adjust your extra calories as you move through your trimesters, no extra calories in the first, about 340 more in the second, and roughly 450 in the third. And when you need a quick bite, a small handful of nuts or a piece of fruit does the trick to fuel both your body and mind.

Smart Gestational Treat Choices and Healthy Indulgence Alternatives
img-4.jpg

Sometimes you crave something sweet without sacrificing the nutrients you need. Instead of reaching for a candy bar, try a dark chocolate square made with at least 70% cacao. It gives you that indulgent feel along with a little boost of antioxidants. You can also blend up a quick homemade smoothie with spinach, berries, and banana, it's a refreshing way to grab a serving of vitamins when you need a moment to recharge.

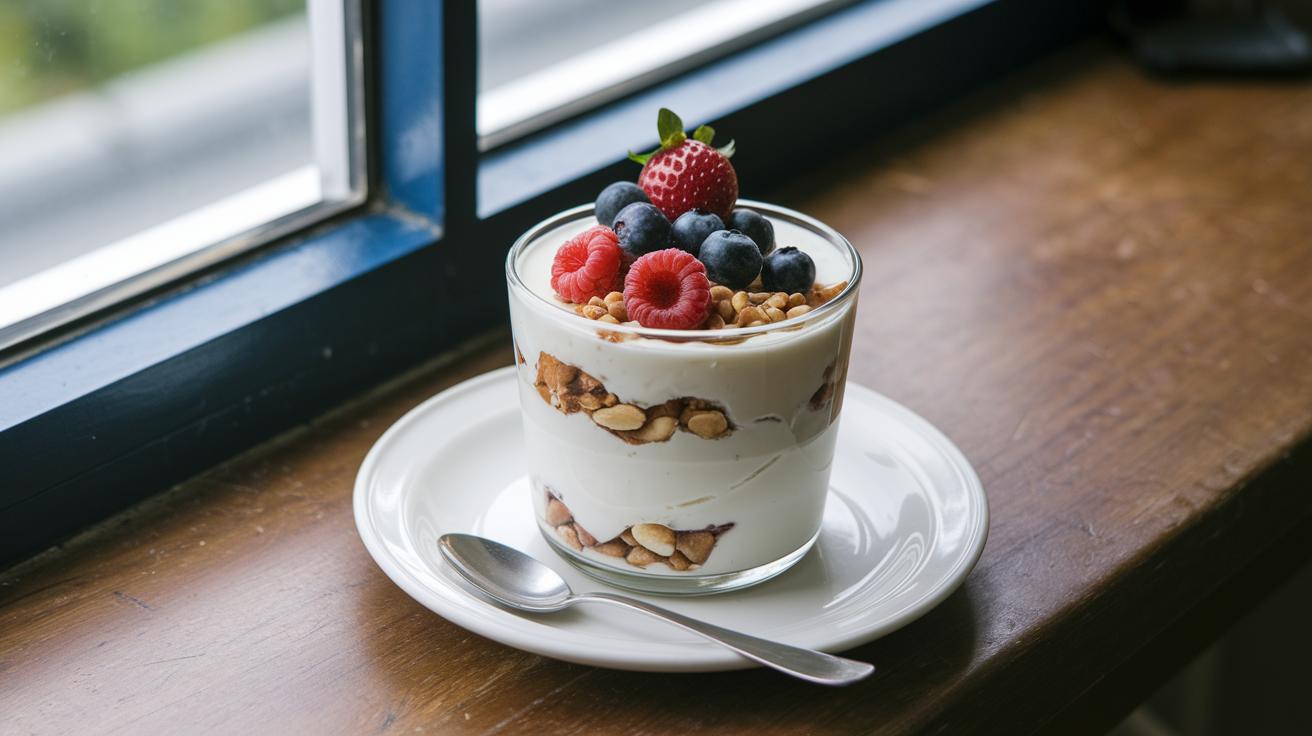
Another option to consider is a Greek yogurt parfait drizzled with a bit of honey and sprinkled with nuts. Every spoonful offers a mix of protein and healthy fats that can warm you up inside. And imagine starting your morning with a slice of whole-grain banana bread that's not only hearty and flavorful but also packed with fiber. For a comforting snack that still keeps you on track, baked sweet potato fries offer vitamin A and a natural sweetness without piling on extra calories.

It helps to keep your portions in check by enjoying just 1 or 2 small servings of sweets each week. This way, every treat becomes a little moment of delight that supports both you and your baby's well-being.

  • Choose dark chocolate squares over candy bars
  • Enjoy a Greek yogurt parfait with honey and nuts
  • Whip up a homemade smoothie or savor whole-grain banana bread
  • Go for baked sweet potato fries

Each of these choices lets you balance your sweet cravings with smart, nourishing benefits.

Nutrient-Dense Comfort Foods and Snack Guidelines for Gestation
img-5.jpg

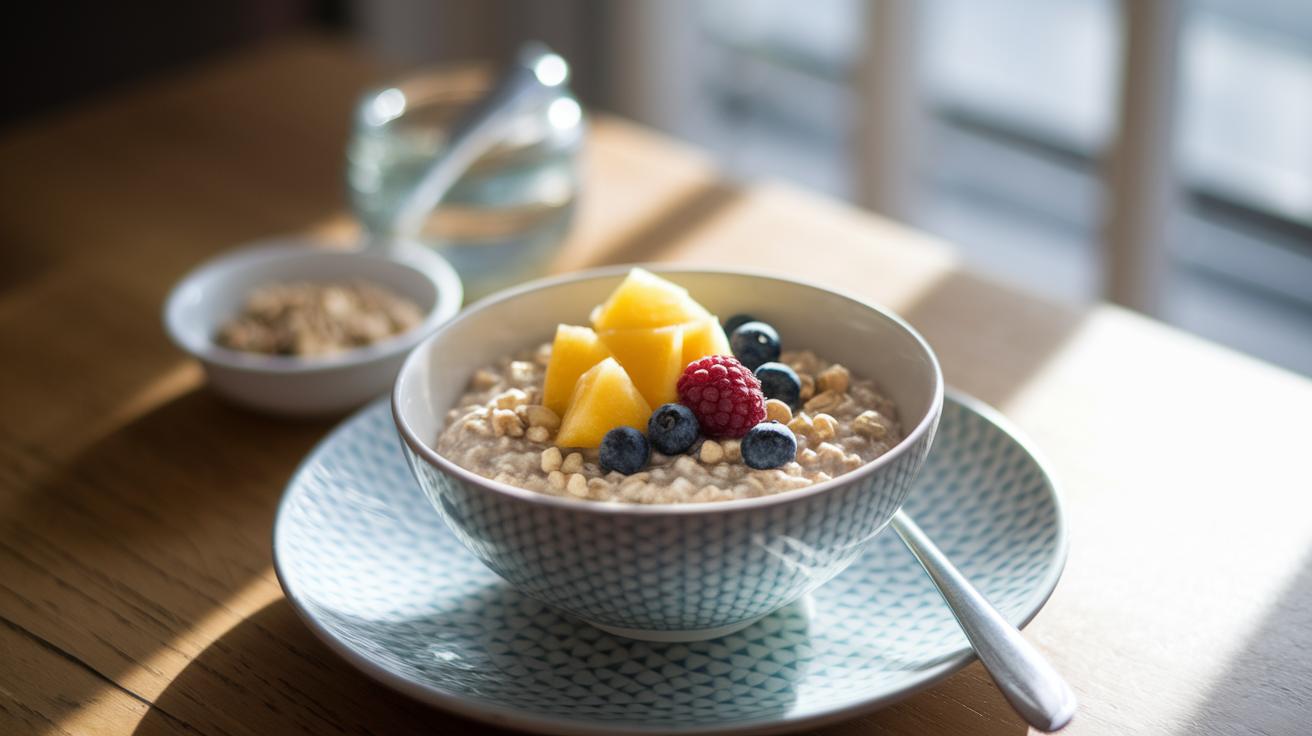
Imagine picking a snack that feels like a warm hug while giving you the energy you need. A cozy bowl of oatmeal with fruit and nuts offers a lovely mix of protein, fiber, and healthy fats, all in under 200 calories. It’s perfect for those moments when a little comfort and nourishment are exactly what you need.

Here are some ideas you might enjoy:

  • Avocado toast with just a pinch of salt, offering a creamy, rich taste.
  • A small bowl of lentil soup that feels light yet fills you up.
  • A scoop of Greek yogurt dip paired with whole-grain crackers for steady energy.
  • A homemade trail mix with dried fruit and seeds that delivers a satisfying crunch.
  • A refreshing smoothie blending protein and fiber with ingredients like spinach and berries, all kept under 200 calories.

These choices not only offer comfort, but they also pack essential nutrients for you and your baby. It’s amazing how a little, well-balanced snack can gently satisfy your cravings while keeping your meals on track.

Calorie Control and Portion Guidelines for Expecting Mothers
img-6.jpg

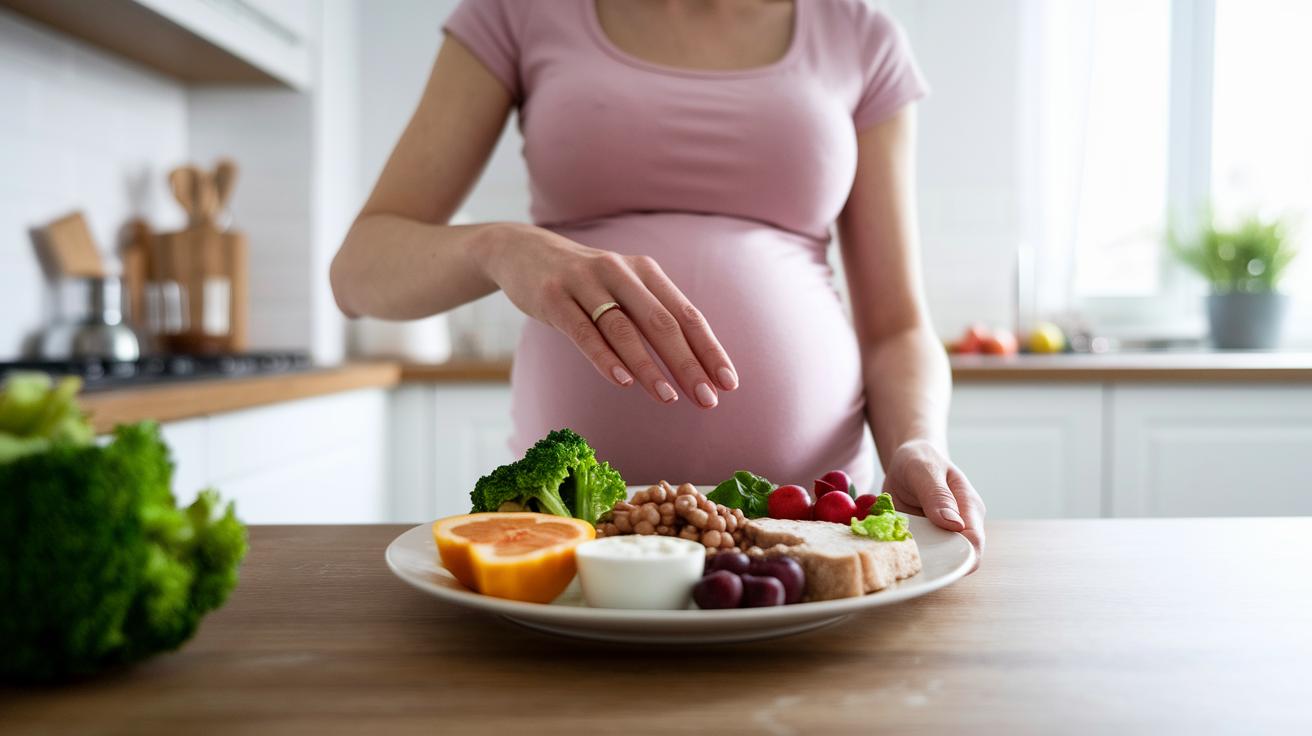
When you're expecting, keeping an eye on your calories can be a smart way to balance the occasional treat with healthy meals. In the first few months, about 1800 to 2000 calories a day is enough, no extra calories needed yet. As you move into the second trimester, think about boosting your daily intake to around 2200 to 2400 calories, which is roughly an extra 340 calories each day. Then in the third trimester, you’ll want to aim for 2400 to 2600 calories, adding about 450 more calories daily.

A friendly trick to help with portion sizes is using your hand as a guide. For example, imagine the size of your palm, that’s a good measure for a portion of protein like chicken or tofu. When it comes to vegetables and fruits, try splitting your plate in half for these nutritious picks, while saving the other half for grains and proteins.

It can also be really helpful to track what you eat with an app. This way, you stay aware of your calorie goals and know that you’re taking care of both you and your baby. And if you have a craving for something extra, limiting high-calorie treats to one or two small servings a week means you can enjoy a little indulgence without losing balance.

Remember, every bite counts. Visualize your portions and adjust them as your pregnancy progresses, knowing each measured serving supports your health and your baby's growth.

Expert Guidance: Maternal Diet, Wellness, and Nutrient Optimization
img-7.jpg

Talk with a prenatal dietitian to tailor your meals to suit your own needs. They can help debunk ideas like “eat for two” and provide advice if you’re dealing with issues like gestational diabetes or anemia. With regular checks on weight, blood tests, and your baby's growth, these experts guide you to make food choices that feel right for you and your little one.

Stay connected with healthcare professionals who care about your diet and well-being. They might recommend adding prenatal vitamins to your routine when needed. For more friendly advice and useful tips, check out the Maternal diet and wellness guidelines. Trusting this expert support can help you mix healthy meals with the occasional treat so you stay nourished and comfortable as you care for yourself and your baby.

Final Words

In the action, we explored how to manage cravings and craft a healthy eating plan while letting a few indulgences brighten your day. We looked at smart treat choices, portion control methods, and nutrient-packed snacks that also support fetal development. All these ideas help with balancing indulgence with nutrition during pregnancy, making every bite count. Enjoy this balanced approach with a smile, knowing you're making nurturing choices for both you and your baby.

FAQ

How can I balance indulgence with nutrition during pregnancy?

Balancing indulgence with nutrition means enjoying small treats while making sure you include nutrient-rich foods like lean protein, fruits, vegetables, and whole grains to support your and your baby’s health.

What should my meal plan look like during early pregnancy?

A meal plan in early pregnancy often suggests several small meals daily, including fruits, lean proteins, whole grains, and healthy fats, which help manage energy and ease occasional morning discomfort.

What foods support having a healthy baby during pregnancy?

Choosing foods such as salmon for omega-3s, leafy greens for iron, dairy or alternatives for calcium, and a mix of fruits and vegetables can support your baby’s growth and development while still allowing for small indulgences.

Is it okay to enjoy treats while pregnant?

Yes, having occasional treats is fine if you keep portions small and balance them with nutrient-dense meals, ensuring both satisfaction and the essential nutrients needed during pregnancy.

What happens if I don’t follow a healthy diet during pregnancy?

Skipping key nutrients may lead to lower energy levels and can affect fetal growth. A balanced diet with protein, vitamins, and minerals helps support both maternal health and your baby’s development.

How can I manage cravings and control portions during pregnancy?

Managing cravings involves mindful eating—pausing to savor flavors and choosing healthy swaps like Greek yogurt with berries—while using portion control helps keep your diet balanced.

Where can I find reliable nutrition guidelines for pregnancy?

Trusted resources, such as official Pregnancy Nutrition Guidelines or advice from prenatal dietitians, offer detailed meal plans and practical tips to support a balanced diet at every stage of pregnancy.
Passenger Car Airbag ICs Market was valued at 1160 million in 2024

0

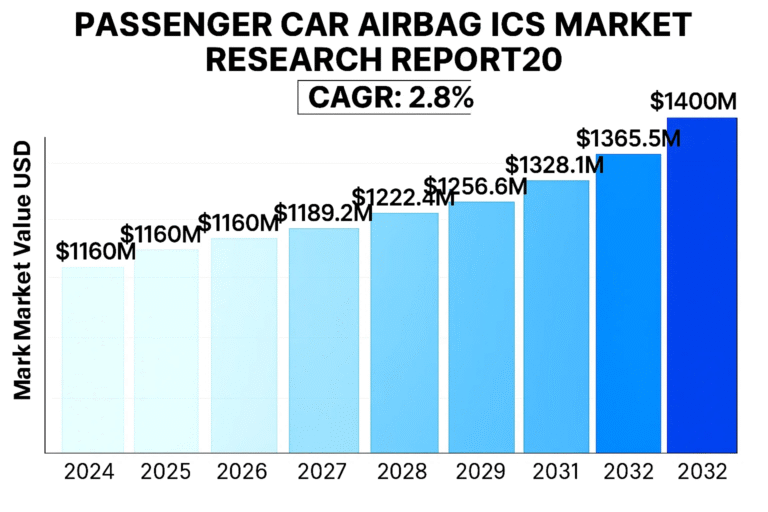
Passenger Car Airbag ICs Market was valued at 1160 million in 2024 and is projected to reach US$ 1400 million by 2032, at a CAGR of 2.8% during the forecast period.

The global Passenger Car Airbag ICs Market was valued at 1160 million in 2024 and is projected to reach US$ 1400 million by 2032, at a CAGR of 2.8% during the forecast period.

Passenger Car Airbag ICs (Integrated Circuits) are specialized semiconductor devices designed for automotive safety systems. These components process collision signals and trigger airbag deployment within milliseconds during accidents, playing a critical role in vehicle occupant protection systems. The technology includes both integrated system-on-chip solutions and discrete IC architectures, with features like crash detection algorithms and fail-safe mechanisms.

The market growth is primarily driven by stringent vehicle safety regulations worldwide and increasing consumer demand for advanced safety features. While Asia dominates production with 56% of global automotive output, Europe and North America remain key innovation hubs for safety technologies. Recent advancements include multi-axis accelerometer integration and AI-enhanced crash prediction systems, with major suppliers like Bosch and Continental investing heavily in next-generation solutions. The gradual recovery of automotive production volumes post-pandemic (reaching 81.6 million units in 2022) further supports market expansion, though supply chain challenges remain a concern for manufacturers.

Download Free Sample Report: https://semiconductorinsight.com/download-sample-report/?product_id=103375

MARKET DRIVERS

Stringent Vehicle Safety Regulations Accelerating Airbag IC Demand

Global automotive safety standards are becoming increasingly rigorous, mandating advanced passive safety systems in passenger vehicles. Over 40 countries have now adopted UN Regulation 137 for frontal impact protection, requiring sophisticated airbag deployment systems. This regulatory push is directly increasing demand for reliable airbag integrated circuits that can meet certification requirements while providing millisecond-level response times critical for occupant protection. The European Union’s updated General Safety Regulations, effective July 2024, further expand mandatory airbag coverage to include rear-seat occupants in all new vehicle models.

Recent Industry Developments

Rise of Predictive & AI-Enabled Airbag Systems

Traditionally, airbags reacted after a crash. But 2024 has marked a clear shift toward predictive deployment, where airbag ICs analyze:

  • Vehicle speed
  • Pre-impact angles
  • Occupant positioning
  • Braking patterns

ICs now leverage sensor fusion, integrating data from LIDAR, radar, cameras, and seat-pressure sensors. The goal? To anticipate collisions and optimize deployment force, speed, and direction.

Companies like STMicroelectronics and Infineon Technologies are leading the charge with intelligent SoCs that merge real-time data analytics with deployment logic.

List of Key Passenger Car Airbag IC Manufacturers

  • Robert Bosch GmbH (Germany)
  • Continental AG (Germany)
  • STMicroelectronics (Switzerland)
  • Analog Devices, Inc. (U.S.)
  • NXP Semiconductors (Netherlands)
  • Infineon Technologies AG (Germany)
  • Denso Corporation (Japan)
  • Texas Instruments Incorporated (U.S.)
  • Renesas Electronics Corporation (Japan)

Segment Analysis:

By Type

Integrated System Chip Segment Leads Due to High Demand for Compact and Efficient Airbag Control Solutions

The market is segmented based on type into:

  • Integrated System Chip
    • Features: Combines multiple functions in a single chip, reducing component count
  • Independent Chip
    • Features: Dedicated ICs for specific airbag system functions

By Application

OEM Segment Dominates as Airbag ICs Are Primarily Installed During Vehicle Manufacturing

The market is segmented based on application into:

  • OEM (Original Equipment Manufacturer)
  • Aftermarket

By Vehicle Type

Sedan Segment Holds Significant Share Due to Higher Production Volumes

The market is segmented based on vehicle type into:

  • Sedan
  • SUV
  • Hatchback
  • Others

By Airbag Type

Frontal Airbag ICs Maintain Market Leadership Due to Regulatory Mandates

The market is segmented based on airbag type into:

  • Frontal Airbag ICs
  • Side Airbag ICs
  • Curtain Airbag ICs
  • Knee Airbag ICs
  • Others

Download Free Sample Report: https://semiconductorinsight.com/download-sample-report/?product_id=103375

About Us:

Semiconductorinsight has been a leading aggregator and consulting provider of semiconductor industry market research reports since 2016, offering high-quality, reliable, and timely reports and consulting services to our clients. 

Services Offered

  1. Market Reports:
    • Comprehensive and data-driven reports offering deep dives into specific segments of the semiconductor industry.
    • Forecasts and trends analysis backed by robust methodologies and historical data.
  2. Custom Research:
    • Tailored research solutions addressing unique business challenges and opportunities.
    • Market entry strategies, competitive benchmarking, and M&A advisory.

CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]
help@semiconductorinsight.com


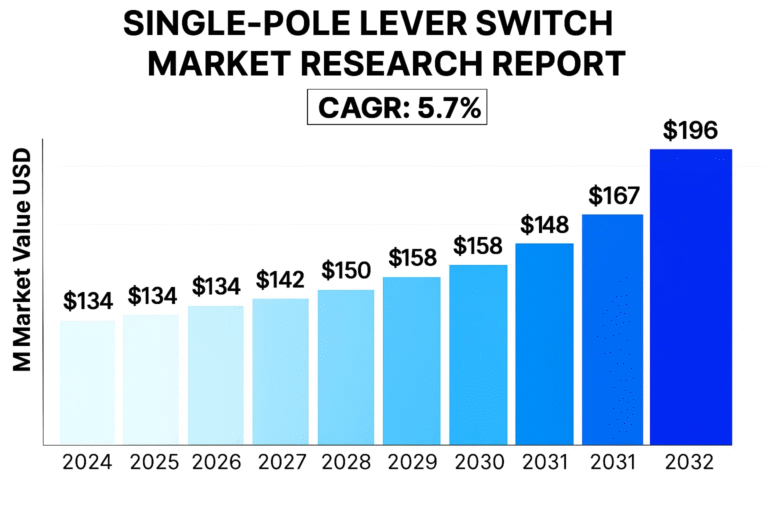
Single-Pole Lever Switch Market was valued at 134 million in 2024 and is projected to reach US$ 196 million by 2032, at a CAGR of 5.7% during the forecast period

0

The global Single-Pole Lever Switch Market was valued at 134 million in 2024 and is projected to reach US$ 196 million by 2032, at a CAGR of 5.7% during the forecast period.

Single-pole lever switches are mechanical switching devices designed to control electrical circuits with a simple ON/OFF mechanism. These components feature a single input and output connection, making them ideal for basic circuit interruption applications across industrial, commercial, and consumer sectors. Their robust lever actuator provides tactile feedback and withstands repetitive operation in demanding environments.

The market growth is driven by increasing industrial automation adoption and expanding electronics manufacturing in Asia-Pacific. While high-voltage switches dominate industrial applications, low-voltage variants are gaining traction in consumer goods. Key manufacturers like Omron Corporation and Schneider Electric are innovating with sealed and vandal-resistant designs to address diverse application needs across automotive, machinery, and building automation sectors.

Download Free Sample Report:  https://semiconductorinsight.com/download-sample-report/?product_id=103396

MARKET DRIVERS

The rapid advancement of Industry 4.0 technologies is driving unprecedented adoption of single-pole lever switches across manufacturing facilities. These reliable switching solutions are becoming integral components in automated production lines, with an estimated 73% of new industrial equipment now incorporating lever-actuated switching mechanisms. The automotive sector alone accounts for 28% of global demand, where these switches enable standardized machine interfaces for enhanced operator safety and control. Recent innovations in switch durability ratings – some now exceeding 1 million mechanical cycles – are further expanding their applications in harsh industrial environments.

Recent Developments Driving Market Growth

  1. Miniaturization and Precision Engineering

One of the most prominent developments is the miniaturization of lever switch designs. Manufacturers are now producing ultra-compact switches (as small as 3mm in height), enabling integration into devices with severe space constraints. These micro switches are perfect for:

  • Wearable electronics
  • Automotive infotainment controls
  • Medical diagnostic devices
  • Aerospace cockpit panels

This trend not only meets the space-saving needs of modern electronics but also improves power efficiency and product weight – both crucial in industries like aviation and automotive.

  1. Integration with IoT and Smart Systems

Traditionally, mechanical switches were isolated components. Today, they’re becoming increasingly “smart-enabled”, with some modern lever switches capable of integrating into IoT ecosystems via:

  • Embedded sensors for positional feedback
  • Data logging features for wear-and-tear analysis
  • Remote control/monitoring via RF or Bluetooth modules

This transformation is enabling preventive maintenance models and enhancing human-machine interfaces (HMI) in industrial environments.

List of Key Single-Pole Lever Switch Manufacturers

  • Omron Corporation (Japan)
  • Schneider Electric (France)
  • Eaton Corporation (Ireland)
  • TE Connectivity (Switzerland)
  • APEM (France)
  • EAO France (France)
  • ALPS Electric (Japan)
  • NKK Switches (Japan)
  • Honeywell International Inc. (U.S.)
  • Schaltbau GmbH (Germany)
  • C&K Components (U.S.)
  • Banner Engineering (U.S.)
  • Dong Nan Electronics (China)
  • E-SWITCH (U.S.)
  • IDEC Corporation (Japan)

Segment Analysis:

By Type

Low Voltage Segment Dominates the Market Due to Widespread Use in Consumer Electronics and Automation Systems

The market is segmented based on type into:

  • High Voltage
  • Low Voltage

By Application

Electronics Application Leads Owing to Increased Integration in Smart Devices and Industrial Control Panels

The market is segmented based on application into:

  • Electronics
  • Consumer Goods
  • Industrial Automation
  • Others

By End User

Manufacturing Sector Captures Majority Share Due to High Demand in Production Line Controls

The market is segmented based on end user into:

  • Manufacturing
  • Consumer Electronics
  • Automotive
  • Energy & Utilities
  • Others

Download Free Sample Report:  https://semiconductorinsight.com/download-sample-report/?product_id=103396

About Us:

Semiconductorinsight has been a leading aggregator and consulting provider of semiconductor industry market research reports since 2016, offering high-quality, reliable, and timely reports and consulting services to our clients. 

Services Offered

  1. Market Reports:
    • Comprehensive and data-driven reports offering deep dives into specific segments of the semiconductor industry.
    • Forecasts and trends analysis backed by robust methodologies and historical data.
  2. Custom Research:
    • Tailored research solutions addressing unique business challenges and opportunities.
    • Market entry strategies, competitive benchmarking, and M&A advisory.

CONTACT US:
City vista, 203A, Fountain Road, Ashoka Nagar, Kharadi, Pune, Maharashtra 411014
[+91 8087992013]
help@semiconductorinsight.com

Affordable Luxury Fashion Market Forecast 2025–2032 | Growth Trends, Key Brands & Consumer Insights

0

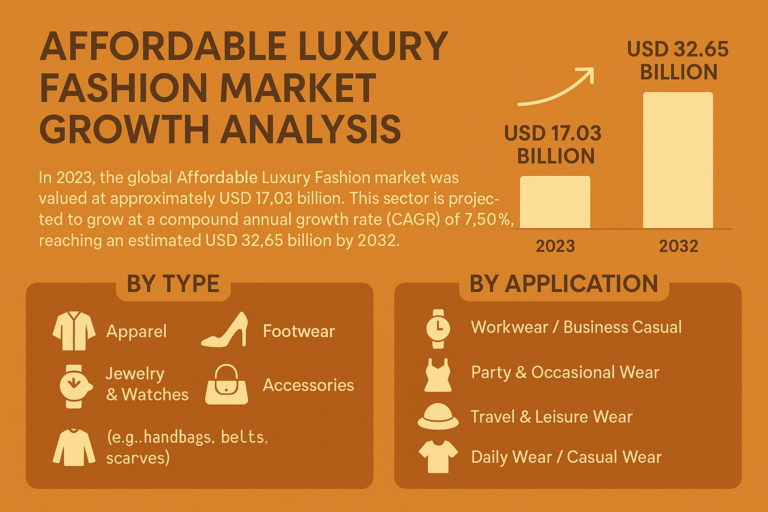
In 2023, the global Affordable Luxury Fashion market was valued at approximately USD 17.03 billion. This sector is projected to grow at a compound annual growth rate (CAGR) of 7.50%, reaching an estimated USD 32.65 billion by 2032. This robust growth trajectory underscores the rising consumer demand for high-end products that offer both prestige and price accessibility.

Affordable Luxury Fashion, often referred to as “entry-level luxury” or “accessible luxury,” encompasses high-end products that are priced lower than traditional luxury goods but still offer premium quality, exclusivity, and brand value. These fashion items serve as a bridge between mass-market and full-scale luxury, attracting middle-income consumers aspiring for a luxury experience. The segment includes items such as branded apparel, accessories, footwear, handbags, jewelry, and cosmetics from reputable designers and fashion houses that are strategically positioned to appeal to style-conscious yet budget-aware customers.

What is Affordable Luxury Fashion?

Affordable Luxury Fashion, often termed “entry-level luxury” or “accessible luxury”, represents high-quality fashion products positioned between mass-market offerings and traditional luxury goods. These items – including apparel, accessories, footwear, handbags, and jewelry – provide the allure of designer brands at more attainable price points (typically $200-$1,500). Brands like Tory Burch, Coach, and Michael Kors dominate this segment, offering the perfect blend of craftsmanship, brand recognition, and relative affordability that appeals to discerning yet budget-conscious consumers.

Download Sample Report: https://www.intelmarketresearch.com/download-sample/905/Affordable-Luxury-Fashion-Market

North America accounted for a significant share, with a market size of USD 5.03 billion in 2023 and a projected CAGR of 6.43% from 2025 through 2032. Factors contributing to this growth include increasing disposable incomes, digital retail expansion, and the cultural shift toward brand-consciousness among younger demographics.

Drivers

The “Mass Prestige” Shift Among Younger Consumers

The growing demand for “mass prestige,” a trend in which consumers, particularly Millennials and Gen Z, seek out high-quality, brand-conscious fashion without ultra-luxury price tags, is a significant factor driving the market for reasonably priced luxury fashion. Today’s consumers prefer subtle elegance, sustainability, and storytelling elements that companies like Polène, COS (by H&M), and & Other Stories effectively utilize, in contrast to earlier generations who sought out overt logos.Consumers are looking for high-end, fashionable goods that have a luxurious appearance without breaking the bank as disposable incomes rise, especially in nations like China, India, and Brazil.Example: Charles & Keith, a Singaporean brand, has gained cult status by offering Prada-esque designs at a fraction of the cost, proving that aspirational pricing ($100-$300) resonates globally.This shift is forcing traditional luxury brands to adapt Gucci’s collaboration with Adidas and Balmain’s diffusion line with Mytheresa are attempts to capture this hybrid consumer.

Opportunities

Growing E-Commerce and Digital Engagement Driving Market Expansion

The market for reasonably priced luxury fashion has a great chance to expand thanks to the quick development of e-commerce platforms and improved digital interaction. A larger, tech-savvy consumer base that values convenience, individualized shopping experiences, and access to exclusive collections can be reached by brands through online channels. For instance, Tapestry Inc., the parent company of Coach and Kate Spade, stated that more than 40% of its sales in 2023 came from digital channels. This shows how important e-commerce is for reaching a wider audience and increasing sales. Affordable luxury brands can now interact directly with younger consumers globally, particularly Millennials and Gen Z, who are major contributors to the growth of this market, thanks to social media marketing and influencer partnerships.

Competitor Analysis

The global Affordable Luxury Fashion market features both heritage brands and modern disruptors. Key players include:

  • Tory Burch – Known for accessible luxury handbags and footwear.
  • Michael Kors – Offers trendy yet premium clothing and accessories.
  • Coach – Renowned for its leather craftsmanship and evolving contemporary appeal.
  • Kate Spade – Focuses on colorful, playful fashion targeting young professionals.
  • Reformation – Appeals to eco-conscious consumers with sustainable, stylish apparel

By Type

  • Apparel
  • Footwear
  • Jewelry & Watches
  • Accessories (e.g., handbags, belts, scarves)

By Application

  • Workwear / Business Casual
  • Party & Occasional Wear
  • Travel & Leisure Wear
  • Daily Wear / Casual Wear
  • Athleisure / Activewear

By End Use

  • Men
  • Women
  • Unisex

By Pricing Tier

  • Entry-Level Luxury (e.g., $100–$300)
  • Mid-Tier Luxury (e.g., $300–$800)

By End-User

  • Individual Consumers
  • Corporate/Institutional Buyers (e.g., for employee gifting, PR purposes)

By Distribution Channel

  • Online Retail
    • E-Commerce Website
    • Company Owned Website
  • Offline Retail
    • Flagship Stores
    • Multi-brand outlets
    • Others

Key Company

  • Tory Burch
  • Michael Kors
  • Coach
  • Ted Baker
  • Ganni
  • Diane von Furstenberg
  • Lucky Brand
  • Polo Ralph Lauren
  • Kate Spade
  • Reformation
  • COS
  • Mara Hoffman
  • Marc Jacobs
  • Calvin Klein
  • Longchamp
  • Parker

Recent Innovations & Brand Initiatives

  • Sustainability-first collections lead the way: Coach launched a 100% recycled‑leather “zero‑impact” handbag line in early 2023, resulting in a 15–22% higher sell‑through among eco-conscious customers 
  • Digital & experiential expansion: 
    • Michael Kors introduced AI-powered virtual try-on tools in 500 stores, boosting satisfaction by ~18% 
    • Kate Spade launched an interactive digital storefront, driving a 25% rise in direct-to-consumer purchases. 
    • Marc Jacobs debuted a metaverse capsule collection in mid‑2023, attracting over 2 million online visitors. 
  • Flagship store innovations: Michael Kors opened a flagship store in Tokyo (March 2024) featuring augmented reality shopping experiences 
  • Sustainable material R&D: Polo Ralph Lauren invested USD 50 million into biodegradable material research in mid‑2024, unveiling its first eco-collection Market Market Dynamics & Consumer Shifts
  • Resale is mainstreaming: The luxury resale market is booming. Brands increasingly partner with resale platforms and launch certification programs. High-tech authentication tools like blockchain and AI are becoming industry norms 
  • Value-conscious buying: With inflation and tariffs squeezing budgets, high‑street and mid‑market brands offering luxury-like quality—i.e. “quiet luxury”—are gaining traction as smart alternatives to traditional luxury. 
  • Small luxuries strategy: Brands such as Chanel, Dior, and Saint Laurent are focusing on “small luxury” items—like sunglasses, charms, and fragrances—as lower-cost touchpoints for aspirational shoppers. 72% of consumers maintained or increased their spend on these items even amid economic pressures. 

Retail & Regional Landscape

  • Store network evolution: Outlets and off-price formats are outperforming full-price and mono-brand stores, with improved conversion rates and curated shopping atmospheres gaining favor 
  • Digital-first dominance: While marketplace channels remain stable (~20% of luxury share), standout monobrand websites and D2C platforms are flourishing, especially in accessible luxury and premium segments 
  • Asia‑Pacific acceleration: APAC is now the fastest-growing region, driven by the rising middle class and increasing spending from Gen Z and millennials in markets like China and India 

The analysis helps the reader to shape the competition within the industries and strategies for the competitive environment to enhance the potential profit. Furthermore, it provides a simple framework for evaluating and assessing the position of the business organization. The report structure also focuses on the competitive landscape of the Global Affordable Luxury Fashion Market. This report introduces in detail the market share, market performance, product situation, operation situation, etc., of the main players, which helps the readers in the industry to identify the main competitors and deeply understand the competition pattern of the market.

Download FREE Sample Report:
Affordable Luxury Fashion Market – View in Detailed Research Report

Explore HVAC Diffusers Market 

About Intel Market Research

Intel Market Research delivers actionable insights in technology and infrastructure markets. Our data-driven analysis leverages:

  • Real-time infrastructure monitoring
  • Techno-economic feasibility studies

Competitive intelligence across 100+ countries
Trusted by Fortune 500 firms, we empower strategic decisions with precision.

International: +1(332) 2424 294 | Asia: +91 9169164321

Website: https://www.intelmarketresearch.com

Follow us on LinkedIn: https://www.linkedin.com/company/intel-market-research

PSA Hydrogen Purification Market Forecast 2025–2032 | Trends, Demand Drivers & Key Players

0

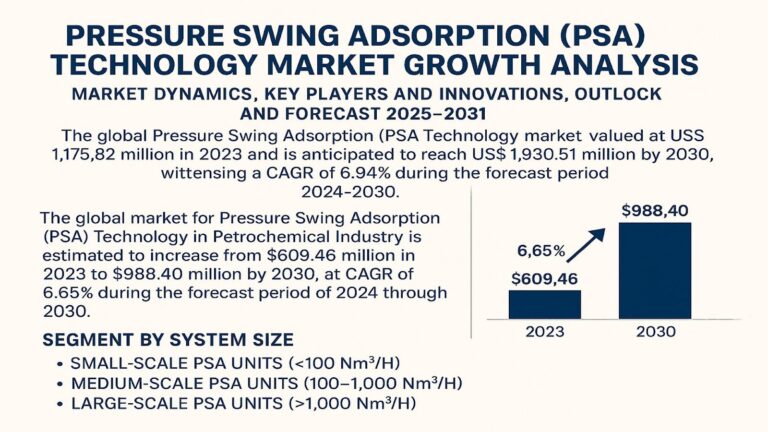
As of the most recent data available, the global PSA Hydrogen Purification market was valued at approximately USD 2.5 billion in 2024 and is expected to reach USD 3.8 billion by 2030, growing at a CAGR of 7.1%. This growth is driven by increasing hydrogen demand across diverse applications such as clean energy production, chemical processing, and mobility solutions (notably hydrogen-powered vehicles).

Historical data shows a consistent rise in hydrogen demand, with significant growth witnessed in Asia-Pacific, particularly China, due to rapid industrialization and government-led clean energy initiatives. Europe and North America are also significant contributors due to robust R&D activities and infrastructure development for hydrogen fueling stations.

Download Sample Report:
https://www.intelmarketresearch.com/download-sample/870/PSA-Hydrogen-Purification-Market

What is PSA Hydrogen Purification?

Pressure Swing Adsorption (PSA) Hydrogen Purification is a widely adopted technology used to separate and purify hydrogen gas from a mixture of gases under pressure. This process leverages the principle of adsorption, where certain gases are trapped on the surface of an adsorbent material at high pressures and then desorbed at low pressures. PSA units are instrumental in producing high-purity hydrogen used in multiple industries, including petroleum refining, ammonia production, fuel cells, and electronics.

The PSA process typically involves multiple stages of adsorbent beds filled with materials like activated carbon, zeolites, or molecular sieves. These beds selectively adsorb impurities such as nitrogen, carbon dioxide, methane, carbon monoxide, and water vapor, allowing purified hydrogen to pass through. PSA technology is favored for its operational flexibility, scalability, low environmental impact, and cost-efficiency over other purification methods like cryogenic separation and membrane technologies.

Market Size

Key statistics:

  • CAGR (2024–2030): 7.1%
  • Market Value (2024): USD 2.5 billion
  • Forecasted Market Value (2030): USD 3.8 billion
  • Major Market Contributors: Asia-Pacific (45%), Europe (30%), North America (20%)

Drivers

  • Growing demand for clean fuel: The shift toward low-emission fuels is significantly increasing hydrogen’s role as an energy carrier.
  • Government incentives and regulatory support: Favorable policies in countries like Japan, Germany, and South Korea are accelerating market growth.
  • Industrial hydrogen demand: The expanding usage of hydrogen in refining, fertilizer production, and electronics fuels the need for efficient purification solutions.

Opportunities

  • Hydrogen fuel cells in transportation: The rise of hydrogen-powered vehicles opens vast potential for PSA hydrogen purification systems.
  • Green hydrogen production: The global pivot toward renewable energy sources presents an opportunity for integrating PSA systems into electrolysis-based hydrogen production.

Market Segmentation (by Capacity)

  • Small-Scale PSA Units (< 100 Nm³/h)
  • Medium-Scale PSA Units(100–1,000 Nm³/h)
  • Large-Scale PSA Units (> 500 Nm³/h)

Market Segmentation (by Purity)

  • 95-99%
  • 99.9%+

Market Segmentation (by Application)

  • Mobility (Fuel Cell Vehicles)
  • Stationary Power
  • Chemical Processing and Production
  • Petroleum Refining:
  • Others

Market Segmentation (by End Use Industry)

  • Oil & Gas (Refining)
  • Chemicals & Petrochemicals
  • Energy & Power
  • Others

Key Company

  • UOP (Honeywell)
  • Linde
  • SWRDICI
  • Air Liquide
  • Air Product
  • PKU PIONEER
  • Ally Hi-Tech
  • CALORIC
  • Quadrogen

Global PSA Hydrogen Purification Market: Market Segmentation Analysis

This report provides a deep insight into the global PSA Hydrogen Purification market, covering all its essential aspects. This ranges from a macro overview of the market to micro details of the market size, competitive landscape, development trend, niche market, key market drivers and challenges, SWOT analysis, value chain analysis, etc.

The analysis helps the reader to shape the competition within the industries and strategies for the competitive environment to enhance the potential profit. Furthermore, it provides a simple framework for evaluating and assessing the position of the business organization. The report structure also focuses on the competitive landscape of the Global PSA Hydrogen Purification Market. This report introduces in detail the market share, market performance, product situation, operation situation, etc., of the main players, which helps the readers in the industry to identify the main competitors and deeply understand the competition pattern of the market.

Recent developmet

Market Momentum & Investment Surge

  • Global investments in hydrogen infrastructure exceeded USD 120 billion in 2023, with ~15% (~USD 18 billion) directed toward purification technologies including PSA systems. PSA startup VC deals increased 25% compared to 2022, highlighting investor confidence in this segment

  • In mid‑2024, leading PSA tech firms formed a USD 500 million R&D consortium to improve energy efficiency, reduce capital costs, and scale modular systems globally Market Growth Reports.

🧪 Technological Innovations & New Product Launches

  • UOP (Honeywell) released high-efficiency PSA units with ~95% hydrogen recovery, while Linde introduced compact PSA modules for hydrogen refueling stations capable of cleaning up to 100 Nm³/h, ideal for constrained spaces 
  • Advanced low-temperature PSA cycles can now reduce energy consumption by 15–20%, and digital twins are entering production—enabling real-time optimization and reducing downtime by ~12%

  • New nanostructured adsorbents, piloted in late 2023, delivered 10–15% higher adsorption capacities, boosting efficiency and uptime.

🌍 Regional Deployments & Strategic Projects

  • Notable expansion in Central Asia: In 2023, Air Products acquired PSA units and SMR capacity at Uzbekistan’s Fergana Oil Refinery (USD 140M deal), strengthening purification capabilities tied to hydrogen feedstock infrastructure 
  • Linde collaborated on major CO₂ capture PSA systems in Europe (Lengfurt cement facility, Germany) and deployed PSA-based HISORP® carbon capture solutions for ADNOC’s Hail & Ghasha project (mid‑2024), showcasing PSA’s broader role in industrial decarbonization

📥 Download Sample PDF:
https://www.intelmarketresearch.com/download-sample/870/PSA-Hydrogen-Purification-Market

About Intel Market Research

Intel Market Research is a leading provider of strategic intelligence, offering actionable insights in energy, industrial technologies, and sustainability solutions. Our research capabilities include:

  • Real-time competitive benchmarking
  • Global technology adoption tracking
  • Country-specific regulatory and pricing analysis
  • Over 500+ industrial reports annually

Trusted by Fortune 500 companies, our insights empower decision-makers to drive innovation with confidence.

🌐 Website: https://www.intelmarketresearch.com
📞 International: +1 (332) 2424 294
📞 Asia-Pacific: +91 9169164321
🔗 LinkedIn: Follow Us

Solar Cell Busbar Market Forecast 2025–2032 | Trends, Innovations & Leading Manufacturers

0

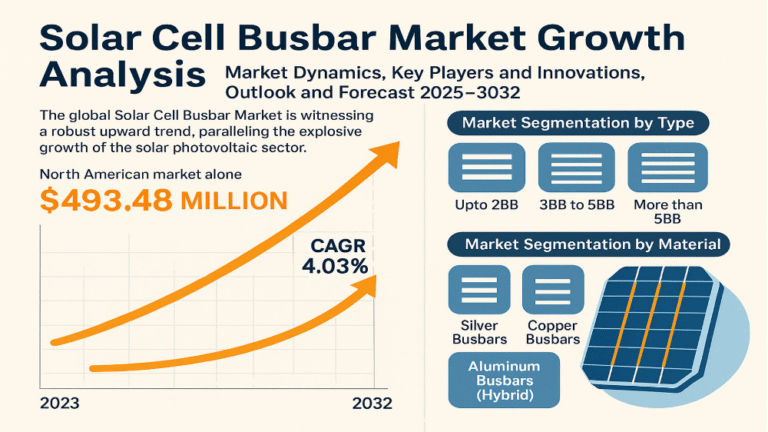
The global Solar Cell Busbar Market is witnessing a robust upward trend, paralleling the explosive growth of the solar photovoltaic sector. In 2023, the North American market alone was valued at approximately USD 493.48 million, with a projected Compound Annual Growth Rate (CAGR) of 4.03% from 2025 through 2032. Globally, this market forms a vital subset of the broader Solar and Electronic Grade Polysilicon Market, which was valued at USD 32.84 billion in 2024 and is forecasted to reach USD 44.91 billion by 2032, growing at a CAGR of 4.2% during the forecast period.

Solar Cell Busbar Market – View in Detailed Research Report

This significant growth is fueled by multiple factors, including increased government incentives for solar installations, rising environmental consciousness, and technological advancements in solar module designs. Innovations such as multi-busbar (MBB) and shingled cells are reshaping the demand for high-performance busbars, increasing the market scope.India’s solar power sector has witnessed an extraordinary 3450 % increase in capacity over the past decade, rising from 2.82 GW in 2014 to 100 GW in 2025. As of January 31, 2025, India’s total solar capacity installed stands at 100.33 GW, with 84.10 GW under implementation and an additional 47.49 GW under tendering.

The Solar Cell Busbar Market pertains to the global industry involved in the production and distribution of busbars used in solar cells. Busbars are thin strips of conductive material (typically silver or copper) that collect and transport electricity generated within solar photovoltaic (PV) cells. They are essential for channeling the electrical current generated by solar cells to external circuits, thus playing a critical role in the overall efficiency and durability of solar panels.

What are Solar Cell Busbars?

Solar cell busbars are conductive metal strips (typically silver, copper, or aluminum) that collect and transfer electrical current within photovoltaic cells. Serving as the circulatory system of solar panels, they significantly impact energy efficiency by:

  • Minimizing resistive losses through optimal current collection
  • Enhancing structural stability of solar cell interconnections
  • Reducing shadowing effects that can decrease light absorption

The industry has evolved from standard 2-3 busbar designs to advanced configurations like Multi-Busbar (MBB) and shingled cell technologies, improving power output by 5-10% according to field tests by leading manufacturers.

 Technological Innovations & Product Launches

  • Multi‑Busbar (MBB) and Super MBB (SMBB) technologies have become mainstream. Modules with 12–16 busbars are now common, yielding 10–15% higher efficiency compared to older 3–5 busbar setups 
  • Copper‑coated busbars are gaining traction: they reduce silver usage by 40–50% while maintaining high conductivity, addressing silver cost constraints 
  • Ultra‑thin busbars (and zero‑busbar or 0BB designs) are reducing shading losses by 10–12% and boosting module yields; their adoption is linked to 22% year-over-year rise in busbar counts per cell and 27% growth in wire-based busbars in the U.S. alone
  • Affordable alternatives like transparent and flexible busbars are enabling clean architectural solar solutions (BIPV), increasing BIPV adoption by 20–30% 
  • AI‑integrated “smart busbars” now optimize solar tracking and current collection, improving system output by 15–20%

  • Hybrid materials R&D, especially perovskite‑silicon tandem busbars, have shown efficiency gains of 25–30% in lab trials—reinforcing synergy with next-gen PV modules

Market Dynamics & Regional Highlights

  • Investment surge: Leading solar manufacturers are channeling 10–15% of their R&D budgets into busbar innovations, driven by global subsidy programs like the U.S. Inflation Reduction Act and Europe’s REPowerEU (boosting solar investments by 20–50%).

  • Solar installation boom: Global installations jumped 87% in 2023 (from ~239 GW in 2022 to ~447 GW), pushing total capacity beyond 2 TW in 2024. This demand fuels more complex busbar requirements for advanced PV architectures (multi-busbar, shingled, HJT) 
  • Silver paste constraints: Busbar development is grappling with volatile silver prices. The PV sector consumed ~14% of global silver demand in 2023 (~161 million oz), prompting urgent shifts toward copper or silver-saving designs

Market Segmentation (by Type)

  • Upto 2BB
  • 5BB to 5BB
  • More than 5BB

Market Segmentation (by Material)

  •  Silver Busbars
  •  Copper  Busbars
  • Aluminum Busbars
  • Silver-Coated Copper (Hybrid)

Market Segmentation (by Technology)

  • Monocrystalline
  • Polycrystalline

Market Segmentation (by Application)

  • Residential
  • Commercial
  • Industrial
  • Utilities
  • Others

Key Company

  • Jinko Solar
  • Trina Solar
  • JA Solar Holdings
  • GCL System Integration
  • Longi
  • Yingli Green Energy
  • Foshan Tanfon Energy Technology Co. Ltd.
  • Sun Power
  • Soligent
  • Sunnova
  • Sunrun
  • Solar City
  • Canadian Solar
  • RGS Energy
  • Kyocera
  • Comorin Solar

Drivers

Surge in Solar Power Installations

A significant driver propelling the global solar cell busbar market is the rapid increase in solar power installations worldwide. With new installations totaling 447 gigawatts (GW), an 87% increase from the 239 GW added in 2022, the global solar power sector saw unprecedented growth in 2023. With 57% of the new capacity coming from China, this surge increased the global solar capacity to 1.6 terawatts (TW). Supportive government regulations, falling solar module prices, and an increased focus on renewable energy sources are driving this expansion.Global solar installations increased by 87% in 2023 compared to 2024, according to SolarPower Europe’s annual Global Market Outlook for Solar Power 2024-2028. In 2024, the world was estimated to reach 2 TW of total solar power after reaching 1 TW in 2022. By 2028, the world could be installing 1 TW of solar a year.

Opportunities

Rising Adoption of High-Efficiency PV Technologies Driving Demand for Multi-Busbar (MBB) Systems 

The rapid adoption of high-efficiency photovoltaic technologies, especially multi-busbar (MBB) and heterojunction (HJT) solar cells, presents a significant opportunity in the global solar cell busbar market. More intricate and effective busbar systems are needed for these sophisticated cell architectures in order to reduce energy loss and enhance cell performance. The International Technology Roadmap for Photovoltaics (ITRPV) 2023 predicts that as the industry moves away from conventional 3BB and 5BB designs, multi-busbar technology’s market share will increase from approximately 70% in 2022 to 100% by 2033. Leading solar module manufacturers like JinkoSolar, JA Solar, and LONGi favor MBB because it increases power output by lowering resistance losses and shadowing effects.


Explore FRP Pressure Vessel Market

📥 Download Sample Report:
Solar Cell Busbar Market – View in Detailed Research Report

About Intel Market Research

Intel Market Research is a leading provider of strategic intelligence, offering actionable insights in energy technologies, renewable infrastructure, and industrial materials. Our research capabilities include:

  • Real-time competitive benchmarking
  • Technology adoption trend analysis
  • Supply chain and manufacturing cost models
  • Over 500+ industrial reports annually

Trusted by Fortune 500 companies, our insights empower decision-makers to navigate market transitions with confidence.

🌐 Website: https://www.intelmarketresearch.com
📞 International: +1 (332) 2424 294
📞 Asia-Pacific: +91 9169164321
🔗 LinkedIn: Follow Us


Global Surgical Stapler Market Poised for Growth Driven by Technological Innovation and Increasing Surgical Procedures

0

The global Surgical Stapler Market is witnessing substantial growth momentum, fueled by the rising number of surgical procedures worldwide and the surging demand for minimally invasive surgeries (MIS). As healthcare systems evolve and medical technology advances, surgical staplers have emerged as a vital tool for surgeons across specialties. They are increasingly replacing traditional suturing methods due to their speed, precision, and reliability, making them indispensable in modern operating rooms.

Surgical staplers are used to close skin wounds, connect or remove sections of internal organs, and perform anastomosis in both open and laparoscopic surgeries. Compared to conventional sutures, staplers offer the advantages of reduced operative time, consistent wound closure, minimal bleeding, and faster patient recovery. These benefits are becoming particularly significant as healthcare providers strive to improve patient outcomes and operational efficiency.

According to Prophecy Market Insights, the Surgical Stapler Market is expected to experience significant expansion in the coming years. This growth trajectory is linked to factors such as the increasing prevalence of chronic diseases, rising adoption of MIS techniques, and continuous advancements in powered surgical devices. The market is evolving with innovations that cater to both routine and highly complex surgical procedures, signaling substantial opportunities for manufacturers and healthcare providers alike.

Get Sample Info:
https://www.prophecymarketinsights.com/market_insight/Insight/request-sample/3807

Key Market Segmentation

To better understand the market dynamics and identify lucrative opportunities, the Surgical Stapler Market can be segmented based on Product Type, Mechanism, Usability, and Application.

By Product Type:

  • Linear Surgical Stapler – Used primarily in gastrointestinal surgeries and thoracic procedures to create straight staple lines.
  • Circular Surgical Stapler – Common in colorectal surgeries and esophageal anastomosis, where circular staple lines are required.
  • Cutter Stapler – Combines stapling and cutting, allowing for faster tissue transection and anastomosis.
  • Skin Stapler – Primarily used for closing skin wounds quickly and efficiently, often in trauma cases.
  • Stapler Reload – Replacement cartridges for reusable stapling devices, ensuring consistent performance during multiple procedures.

By Mechanism:

  • Manual Surgical Stapler – Cost-effective and widely used, though requiring greater surgeon effort.
  • Powered Surgical Stapler – Battery or electrically operated devices that reduce surgeon fatigue and improve precision, increasingly popular in high-volume hospitals.

By Usability:

  • Disposable Surgical Stapler – Single-use devices ensuring sterility and reducing infection risks.
  • Reusable Surgical Stapler – Designed for multiple uses with replaceable cartridges, offering cost benefits for healthcare facilities.

By Application:

  • Abdominal Surgery – Used in gastrointestinal resections, colectomies, and bariatric surgeries.
  • Obstetrics and Gynecological Surgeries – Particularly in C-sections and hysterectomies.
  • Cardiac and Thoracic Surgeries – For lung resections, heart valve procedures, and other cardiothoracic interventions.
  • Orthopedic Surgery – Occasionally used in wound closures after major bone or joint surgeries.
  • Other Surgical Applications – Including pediatric, urological, and trauma surgeries.

Market Drivers and Trends

The growth of the Surgical Stapler Market is driven by several key factors:

  1. Rise in Chronic Diseases:
    Conditions like cardiovascular disorders, gastrointestinal cancers, and obesity-related complications often require surgical interventions, increasing the demand for reliable closure devices.
  2. Shift Toward Minimally Invasive Surgeries (MIS):
    MIS techniques are gaining popularity because they result in smaller incisions, reduced hospital stays, and faster recovery. Surgical staplers are essential in such procedures for precise and clean closure.
  3. Technological Advancements:
    The market is witnessing innovations such as powered staplers with real-time feedback systems, smart sensors for tissue compression, and ergonomic designs that enhance surgeon control.
  4. Improved Patient Outcomes:
    By reducing surgery time and minimizing tissue trauma, staplers contribute to lower postoperative complications, which is a strong driver for their adoption.
  5. Global Healthcare Expansion:
    The establishment of new hospitals, particularly in emerging economies, and the growth of medical tourism are expanding the customer base for surgical stapler manufacturers.

Competitive Landscape

The market is characterized by intense competition, with established players and emerging companies investing heavily in R&D, product diversification, and global expansion. Strategic collaborations, mergers, and acquisitions are common as companies aim to enhance their market share and technological edge.

Key players include:

  • CONMED Corporation
  • B. Braun Melsungen AG
  • Ethicon Inc. (Johnson & Johnson)
  • Frankenman International Limited
  • Intuitive Surgical Inc.
  • Medtronic PLC
  • Meril Life Sciences Pvt. Ltd.
  • Purple Surgical, Inc.
  • Smith & Nephew
  • 3M Company

These companies are focusing on the development of next-generation staplers that integrate powered mechanisms, ergonomic designs, and smart surgical features. The competitive push toward automation and precision-based tools is reshaping the global market landscape.

Regional Outlook

  • North America:
    Remains the leading market, supported by advanced healthcare infrastructure, high adoption of innovative medical devices, and favorable reimbursement policies. The U.S. leads in both usage and development of powered surgical staplers.
  • Europe:
    Strong regulatory frameworks, high surgical volumes, and ongoing technological integration are driving market growth. Countries like Germany, France, and the UK are key markets.
  • Asia-Pacific:
    Emerging as the fastest-growing region, driven by an increasing number of hospitals, medical tourism, and government initiatives to upgrade healthcare systems. Countries like China, India, and South Korea are becoming important hubs for surgical device manufacturing and consumption.
  • Latin America and Middle East & Africa:
    Growth in these regions is supported by improving healthcare facilities and increased public and private investment in surgical infrastructure.

Analyst Perspective

“The surgical stapler market is transforming with innovations in powered and intelligent stapling solutions. We anticipate robust growth across both developed and emerging economies as demand for high-efficiency surgical devices continues to rise,”
— Riya B. More, Research Associate at Prophecy Market Insights.

This detailed market study is based on extensive primary research (including interviews with surgeons, hospital procurement managers, and medical device manufacturers) and secondary research (company annual reports, government publications, and industry databases). The report provides actionable insights into current trends, market challenges, competitive dynamics, and strategic opportunities that stakeholders can leverage for growth.

With surgical volumes expected to continue rising globally, particularly in developing nations, and healthcare systems investing in advanced medical technologies, the future of the Surgical Stapler Market looks promising. Manufacturers that focus on cost-effective, user-friendly, and technologically advanced products will be best positioned to capture emerging opportunities.

Biosensors Market: Revolutionizing Real-Time Diagnostics Across Healthcare, Food, and Security

0

The global Biosensors Market is undergoing rapid transformation, fueled by the rising demand for real-time, accurate, and accessible diagnostic solutions. Biosensors—analytical devices that integrate a biological sensing element with a physical transducer—are now pivotal across a wide spectrum of industries. From medical diagnostics and point-of-care (PoC) testing to environmental monitoring, food safety assurance, and defense applications, biosensors are enabling faster, more precise, and more cost-effective detection of critical biological and chemical parameters.

These devices are at the forefront of healthcare innovation, enabling continuous disease monitoring, decentralized diagnostics, and early detection of contaminants in food and environmental systems. With advances in sensor miniaturization, smartphone integration, and AI-driven analytics, biosensors are poised to reshape how industries approach diagnostics and quality control.

Request Sample Report:- https://www.prophecymarketinsights.com/market_insight/Insight/request-sample/3721

Market Segmentation

By Technology Type:

  1. Thermal Biosensors – These leverage the detection of heat changes in biochemical reactions to identify specific biological interactions. They are widely used in analytical chemistry and molecular biology research. 
  2. Electrochemical Biosensors – Representing the most widely adopted biosensor category, they are valued for their rapid results, cost-efficiency, and adaptability to portable formats. Electrochemical biosensors have revolutionized glucose monitoring for diabetic patients and are expanding into other health applications. 
  3. Piezoelectric Biosensors – These detect minute changes in mass on the sensor surface, making them ideal for applications such as allergen detection and pathogen monitoring in food and environmental testing. 
  4. Optical Biosensors – Known for exceptional sensitivity and specificity, optical biosensors have significant applications in drug discovery, real-time disease detection, and environmental monitoring, offering immediate visual or digital readouts. 

By Application:

  • Medical Diagnostics 
    • Pregnancy Testing 
    • Cholesterol Monitoring 
    • Blood Glucose Monitoring 
    • Drug Discovery 
    • Infectious Disease Detection 
    • Blood Gas Analysis 
  • Environmental Monitoring – Used for detecting pollutants, toxins, and other environmental hazards. 
  • Agriculture – Applied in biosecurity for livestock and crop health monitoring. 
  • Food Toxicity Testing – Ensures food safety by detecting contamination or spoilage in real-time. 
  • Bioreactors (Bioprocess Monitoring) – Optimizes production processes in biotechnology and pharmaceutical manufacturing. 

While medical diagnostics—particularly glucose monitoring—currently dominate market demand, the growing emphasis on environmental protection, agricultural biosecurity, and food quality control is expanding biosensor adoption beyond the healthcare sector.

By End-User:

  1. Food Industry – Utilizes biosensors for contamination prevention and freshness monitoring. 
  2. Research Laboratories – Employ biosensors for experimental analysis, drug development, and academic research. 
  3. Home Healthcare Diagnostics – Includes consumer-level biosensors for self-monitoring of health conditions. 
  4. Point-of-Care (PoC) Testing – Portable biosensors designed for rapid diagnosis in clinics, field hospitals, and remote locations. 
  5. Security & Bio-defense – Deployed for early detection of biothreat agents in national defense and public safety contexts. 

The expansion of home healthcare and PoC testing has been accelerated by the COVID-19 pandemic and the rising incidence of chronic illnesses, making quick, reliable diagnostics more critical than ever. Meanwhile, security agencies increasingly integrate biosensors into defense protocols to identify potential biological threats.

Market Drivers and Trends

  1. Rise in Chronic Diseases
    Increasing rates of diabetes, cardiovascular diseases, and infectious illnesses are fueling demand for personal and wearable biosensors capable of continuous health tracking. 
  2. Expansion of PoC and Home Testing
    Both clinicians and consumers are turning to portable, real-time diagnostic solutions that reduce the need for in-person medical visits while enabling quicker treatment decisions. 
  3. Technological Advancements
    Breakthroughs in sensor miniaturization, integration with smartphones, and AI-enhanced data analytics are improving biosensor accuracy, portability, and affordability. 
  4. Food and Environmental Safety Regulations
    Heightened awareness of contamination risks in food and agriculture is prompting broader biosensor deployment to ensure compliance with safety standards. 
  5. Bio-defense Applications
    Concerns over pandemics, bioterrorism, and emerging pathogens are encouraging global investments in biosensors for early detection and rapid containment strategies. 

Key Market Players

The competitive landscape of the biosensors industry is shaped by both established diagnostic leaders and innovative newcomers. Key companies include:

  • F. Hoffmann-La Roche Ltd. 
  • Universal Biosensors Inc. 
  • LifeScan Inc. 
  • Abbott Point of Care Inc. 
  • Sysmex Corporation 
  • Pharmaco-Kinesis Corporation (PKC) 
  • Bio-Rad Laboratories Inc. 
  • Biosensors International Pte. Ltd. 
  • ACON Laboratories Inc. 
  • Nova Biomedical Corp. 

These players are focusing on developing next-generation biosensor platforms that integrate wireless communication, real-time data processing, and compatibility with mobile health ecosystems. Strategic moves include partnerships with tech companies, increased R&D investments, and product diversification into non-medical markets.

Regional Insights

  • North America – Leads the global market due to high healthcare spending, strong research funding, and widespread adoption of biosensors for chronic disease management. 
  • Europe – Prioritizes early disease detection, aging population care, and environmental biosensing, supported by strong regulatory frameworks. 
  • Asia-Pacific – The fastest-growing market, driven by healthcare infrastructure expansion, increasing medical tourism, and large-scale investment in research and innovation. 
  • Latin America & MEA – Emerging growth regions with rising public health initiatives, improving healthcare access, and increasing investments in diagnostic technologies. 

Comprehensive data, forecasts, and competitive benchmarking are available via the following resources:

Download PDF Report https://www.prophecymarketinsights.com/market_insight/Insight/request-pdf/3721

These resources provide strategic insights categorized by technology, region, end-user segment, and key industry developments, offering a complete view of the biosensors market landscape.

About the Author

Riya B. More, Research Associate at Prophecy Market Insights, is the author of this report. Her work integrates a mix of primary research, in-depth expert consultations, and thorough secondary data analysis to present a holistic and actionable understanding of the Biosensors Market. Her analysis emphasizes not only the current market status but also future opportunities, competitive dynamics, and potential technological disruptions shaping the sector.

Medical Sterile Swabs Market: Clinical Trends, Segmentation, and Industry Forecast

0

The Medical Sterile Swabs Market is witnessing significant global growth, fueled by heightened emphasis on infection prevention, accuracy in diagnostic sampling, and efficiency in clinical testing. These swabs—engineered to meet stringent sterility and quality standards—are essential in hospitals, laboratories, diagnostic centers, and research institutes. Their role spans specimen collection, disinfection, forensic sampling, and even specialized industrial or environmental applications.

Post-COVID-19, the healthcare sector’s reliance on sterile swabs has expanded beyond emergency response to include routine respiratory testing, genetic screening, and point-of-care diagnostics. As healthcare systems worldwide integrate more frequent patient monitoring and strict infection control protocols, demand for advanced swab types continues to accelerate.

To review detailed market statistics, segment forecasts, and competitive benchmarking, request the full sample here:
https://www.prophecymarketinsights.com/market_insight/Insight/request-sample/4452

Market Segmentation

The market is segmented by Type, Application, and End-User, each reflecting distinct operational needs and technological trends.

1. By Type

  • Cotton Tipped Swabs
    The most widely used category, offering high absorbency and versatility. Commonly employed for specimen collection in clinical settings, general wound cleaning, and routine medical procedures.

  • Foam Tipped Swabs
    Designed for high-precision applications such as DNA testing, delicate surface cleaning, and medical device maintenance. Foam tips provide superior softness and structural integrity for sensitive sampling.

  • Non-woven Swabs
    Made from synthetic fibers that offer excellent wicking properties. These swabs are preferred in wound care, gentle cleaning, and sensitive dermatological applications.

  • Others
    Includes polyester, rayon, and flocked swabs tailored for specialized tasks such as viral transport media (VTM) sampling or advanced microbiological analysis.

2. By Application

  • Specimen Collection
    The largest and fastest-growing segment, significantly expanded by COVID-19 testing protocols. Today, specimen collection remains vital for detecting respiratory illnesses, sexually transmitted infections (STIs), and genetic disorders.

  • Disinfection
    Used in pre- and post-operative preparation, injection sites, and minor surgical procedures, helping reduce infection risks in clinical environments.

  • Others
    Covers forensic science, veterinary medicine, environmental monitoring, and industrial hygiene testing.

3. By End-User

  • Hospitals & Clinics
    Major consumers of sterile swabs for diagnostics, disinfection, and emergency procedures.

  • Laboratories & Diagnostic Centers
    Significant demand for high-precision swabs for use in advanced molecular testing, microbiology, and pathology.

  • Research Institutes
    Use swabs for specialized sampling, genetic research, and product development trials.

This segmentation highlights the product’s wide applicability—from frontline healthcare to specialized research fields.

Key Market Drivers

  1. Increased Diagnostic Testing
    COVID-19 dramatically increased global awareness and use of sterile swabs. Even as pandemic testing scales down, routine screening for respiratory, genetic, and infectious diseases continues to support strong market demand.

  2. Rising Hospital Admissions & Surgical Procedures
    Swabs remain essential for both pre- and post-operative disinfection, contributing to infection prevention in high-risk clinical settings.

  3. Growth in Point-of-Care (POC) Testing
    At-home diagnostic kits using self-collection swabs are expanding rapidly in developed markets, offering convenience and faster diagnosis.

  4. Technological Advancements
    The adoption of flocked swabs—engineered for improved sample recovery and higher diagnostic accuracy—represents a notable innovation in specimen collection.

  5. Stringent Infection Control Regulations
    Global health authorities are mandating single-use sterile medical supplies, strengthening swab adoption across inpatient, outpatient, and community health settings.

Competitive Landscape

The global market is moderately fragmented, with a mix of established multinational companies and specialized manufacturers focusing on niche applications. Leading players include:

  • Biosigma

  • Puritan Medical Products

  • Dynarex Corporation

  • Medical Wire & Equipment Co. Ltd. (MWE)

  • Copan Italia

  • F.L. Medical

  • BD (Becton, Dickinson and Company)

  • Medtronic Inc.

  • Super Brush

  • 3M

These companies invest heavily in maintaining sterile integrity, developing innovative packaging solutions, ensuring compliance with regulatory standards such as FDA and CE certifications, and expanding capacity to meet molecular diagnostic demand. Many have scaled up production since the pandemic to ensure stable global supply.

Regional Insights

  • North America
    Dominates the market due to advanced healthcare infrastructure, extensive diagnostic testing networks, and continuous investment in R&D.

  • Europe
    Strong regulatory frameworks emphasizing patient safety drive adoption of single-use sterile swabs in hospitals and laboratories.

  • Asia-Pacific
    The fastest-growing regional market, fueled by large population bases, expansion of healthcare access in India, China, and Southeast Asia, and rising awareness of infectious disease prevention.

  • Latin America & Middle East/Africa
    Experiencing steady growth as healthcare infrastructure improves and public health initiatives focus on controlling communicable diseases.

For complete datasets, market dynamics, pricing trends, and in-depth competitor benchmarking, access the full PDF report here:
https://www.prophecymarketinsights.com/market_insight/Insight/request-pdf/4452

These resources provide comprehensive coverage, including regulatory landscapes, SWOT analyses, and 5- to 10-year forecasts.

Future Market Outlook

The Medical Sterile Swabs Market will continue to expand, driven by:

  • Integration of AI and IoT in diagnostics, allowing for faster and more accurate test processing.

  • Sustainable manufacturing innovations, including biodegradable swab materials to reduce environmental impact.

  • Expansion of decentralized healthcare models, boosting the use of at-home testing kits.

  • Increased focus on global health preparedness, ensuring rapid swab supply for potential future outbreaks.

As molecular diagnostics and precision healthcare advance, demand for swabs that meet higher sensitivity and specificity standards will become the industry norm.

About the Author

This report was prepared by Riya B. More, Research Associate at Prophecy Market Insights. Her work combines primary industry interviews, expert feedback, and extensive secondary research to deliver actionable insights into the evolving Medical Sterile Swabs Market.

Animal Medicine Market: Global Insights, Innovation Trends, and Competitive Landscape

0

The Animal Medicine Market is evolving at a rapid pace, fueled by heightened awareness of animal health, a significant increase in pet ownership, and growing emphasis on food safety in livestock farming. This market includes a broad spectrum of pharmaceuticals, biologics, vaccines, and therapeutic solutions intended for both companion animals and livestock. From preventive healthcare to advanced treatment protocols, the industry is experiencing innovation across veterinary diagnostics, biotechnology, and targeted therapy development.

Post-pandemic trends have reinforced the importance of preventive care—not only for pets but also for farm animals whose health directly impacts food security. In livestock, the focus is on managing diseases to prevent large-scale outbreaks, while in companion animals, owners are seeking more specialized, personalized, and premium healthcare solutions that mirror advances in human medicine.

To explore detailed statistics, market forecasts, and deeper insights, the sample report can be accessed here:
https://www.prophecymarketinsights.com/market_insight/Insight/request-sample/3406

Market Segmentation

The market can be divided into segments based on Product Type, Animal Type, Route of Administration, and End-User.

1. By Product Type

Drugs

  • Anti-Infectives – Used to combat bacterial, viral, and fungal infections.
  • Anti-Inflammatory – Relieve pain and inflammation in conditions like arthritis in pets and joint issues in working animals.
  • Parasiticides – Protect against internal and external parasites such as ticks, worms, and mites.
  • Others – Includes specialty medicines for niche or emerging conditions.

Vaccines

  • Live Attenuated Vaccines – Utilize weakened pathogens to stimulate immunity.
  • Inactivated Vaccines – Contain killed pathogens for safe and effective disease prevention.
  • Recombinant Vaccines – Created through genetic engineering for precise targeting.
  • DNA Vaccines – An advanced category offering long-lasting immunity with minimal side effects.
  • Others – Combination vaccines and other novel formats for disease prevention.

These categories collectively address routine preventive care as well as targeted treatments for infectious diseases and parasitic infestations.

  1. By Animal Type

Livestock Animals

  • Poultry – Vital for global food supply; focus on preventing avian diseases.
  • Swine – Strong demand for prevention programs against diseases like African swine fever.
  • Fish – Growing aquaculture industry drives need for specialized treatments and vaccines.
  • Cattle – Emphasis on dairy productivity, mastitis prevention, and disease control.
  • Others – Includes goats, sheep, and camels depending on regional farming practices.

Companion Animals

  • Dogs – Largest share in pet medicine, including vaccines, dental care, and chronic illness management.
  • Cats – Growth in targeted solutions for feline-specific health issues.
  • Horses – Focus on joint care, parasite prevention, and performance enhancement.
  • Others – Exotic pets and small mammals requiring specialized veterinary services.

Livestock health remains essential for food production and economic sustainability, while companion animal care continues to grow as pet ownership expands.

  1. By Route of Administration
  • Oral – Includes tablets, capsules, feed additives for easy delivery.
  • Injectable – Used for both vaccines and targeted treatments.
  • Topical – Gels, ointments, and sprays, especially for skin-related issues.
  • Others – Innovative formats like transdermal patches and nasal sprays.
  1. By End-User
  • Veterinary Hospitals & Clinics – Provide both preventive and curative services.
  • Animal Care Centers – Focus on rehabilitation, wellness, and preventive care.
  • Others – Mobile units, farm-based services, and research-focused facilities.

These channels form a diverse veterinary ecosystem serving clinical, preventive, and emergency needs.

Key Market Drivers

  1. Rising Pet Ownership
    Pet adoption has surged worldwide, especially after the pandemic, leading to increased demand for wellness services, diagnostics, and preventive vaccination.
  2. Concerns Over Zoonotic Diseases
    Threats from diseases such as avian flu, swine fever, and rabies have driven more surveillance and vaccination in both pets and livestock.
  3. Livestock Productivity Goals
    With rising global food demand, governments and industries are investing in animal health to enhance dairy, meat, and aquaculture yields.
  4. Advances in Regulation and R&D
    Accelerated approvals, investment in recombinant vaccine technologies, and new veterinary biotechnologies are pushing innovation forward.

Major Market Players

The competitive landscape is moderately consolidated, with leading players focusing on innovation, biosciences, and diagnostics. Major companies include:

  • Grey Wolf Animal Corp
  • Merck & Co., Inc.
  • Boehringer Ingelheim International GmbH
  • SolMan Healthcare Pvt.
  • Neogen Corporation
  • Vetoquinol
  • Zoetis Services LLC
  • HESTER BIOSCIENCES LIMITED
  • Bayer AG
  • Elanco
  • Novavive Inc.
  • Virbac
  • AB Science
  • Phibro Animal Health Corporation
  • Dechra

These companies are developing broad-spectrum antibiotics, advanced parasiticides, and genetically engineered vaccines to address both treatment and prevention in animal health.

Regional Insights

  • North America – Leads the market with strong infrastructure, high veterinary spending, and awareness of zoonotic risks.
  • Europe – Sees steady growth supported by strict regulations and sustainable farming initiatives.
  • Asia-Pacific – Fastest-growing region due to rising livestock farming, expanding veterinary services, and increasing pet-related spending.
  • Latin America & Middle East/Africa – Emerging markets driven by food security initiatives and expanding animal husbandry industries.

For complete forecasts, detailed market share analysis, and insights on therapeutic developments, the full report can be downloaded here:
https://www.prophecymarketinsights.com/market_insight/Insight/request-pdf/3406

Future Market Outlook

Looking ahead, the Animal Medicine Market is expected to see significant advancements in precision veterinary medicine, including personalized biologics and AI-based diagnostic tools. Genomic-based preventive strategies, improved cold-chain vaccine delivery for rural and remote areas, and the growth of tele-veterinary services will redefine how care is delivered. Sustainability pressures will also encourage a shift toward eco-friendly treatments and reduced reliance on antibiotics in livestock farming.

About the Author

This analysis was prepared by Riya B. More, Research Associate at Prophecy Market Insights. Using a comprehensive methodology that includes primary interviews with industry stakeholders, expert insights, and in-depth secondary research, Riya provides a thorough overview of the trends, competitive dynamics, and opportunities shaping the global Animal Medicine Market.