Friday, October 9, 2026
Home Blog Page 124

The Future Unfolded: Foldable Smartphones Market Outlook 2025

Introduction:
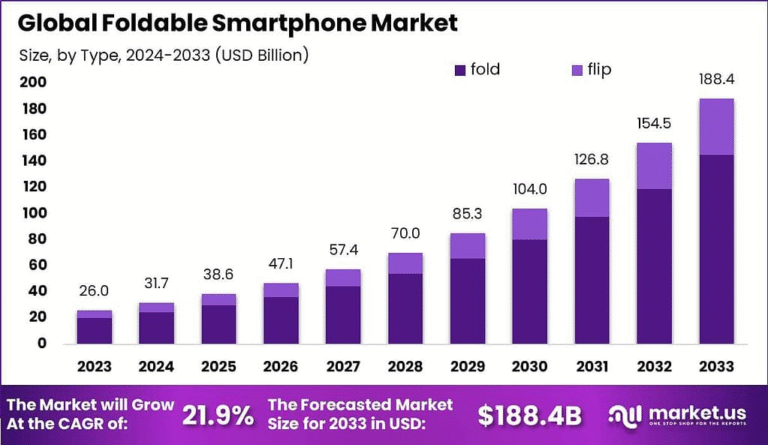
The Foldable Smartphones Market is projected to surpass USD 55 billion by 2030, growing at a CAGR of over 22% from 2024. The market’s growth is driven by rising consumer demand for innovative form factors, multitasking capabilities, and immersive displays. Advances in flexible OLED technology, hinge mechanics, and foldable glass have made devices more durable and functional. Premium smartphone users are increasingly seeking differentiation, pushing manufacturers to expand foldable offerings. With increasing investments from OEMs and a maturing supply chain, foldable smartphones are transitioning from niche luxury items to mainstream premium devices, reshaping the future of mobile technology.

Key Takeaways:

  • Market expected to exceed USD 55 billion by 2030

  • CAGR of 22%+ driven by tech innovation and consumer demand

  • Asia-Pacific dominates with early adopter user base

  • Foldable screens enhance productivity and entertainment

  • Hybrid tablet-smartphone appeal boosts user interest

  • Increasing OEM investments in R&D and display tech

  • Premium pricing limits mass-market penetration

  • Durability improvements critical to adoption

  • Online and retail marketing campaigns drive awareness

  • Integration with 5G and AI expands use-case scenarios

Emerging Trends:
Foldable smartphones are integrating AI-driven multitasking interfaces to enhance productivity. New form factors like tri-fold and rollable designs are being prototyped. Ultra-thin foldable glass and polymer composites are improving device durability. Hinge technology is evolving for dust and water resistance. Seamless app continuity across folded/unfolded states is becoming a standard. Gaming and AR/VR use cases are gaining traction on foldable platforms. Foldables are being positioned as productivity tools in enterprise settings. Sustainability efforts are influencing recyclable material choices. Advanced cooling systems are being implemented for performance efficiency. Partnerships between display makers and OEMs are fostering ecosystem development for foldable innovation.

Use Cases:

  • Multitasking with split-screen functionality in business and productivity apps

  • Immersive gaming and streaming on expanded display modes

  • Compact portability with full tablet-like screen space

  • Enhanced video conferencing and document editing

  • AR/VR-enhanced navigation and virtual collaboration

  • Seamless reading, browsing, and eBook experiences

  • Creative workflows for design, sketching, and photo editing

  • Retail and e-commerce product visualization in larger formats

  • Enhanced user interface in fold/unfold transitions

  • Professional use in healthcare, education, and financial services

Major Challenges:
High manufacturing costs of foldable displays and hinges lead to premium pricing, restricting affordability. Concerns over durability, screen creasing, and mechanical failure reduce consumer trust. Limited app optimization for foldable formats hampers user experience. Complex design increases repair costs and supply chain strain. Battery life optimization is difficult in thin, foldable designs. Weight distribution and ergonomics are still under refinement. Regulatory and e-waste concerns around foldable components persist. Competitive pressure forces rapid innovation cycles, raising R&D expenses. Limited product variety slows mainstream adoption. Consumer education and awareness about long-term benefits remain limited in certain markets.

Opportunities:
Rising demand for differentiated and high-performance smartphones creates strong market pull. Expansion in enterprise use cases for foldables opens new B2B segments. Emerging markets with rising income levels offer fresh adoption potential. Integration with AI, 5G, and edge computing enhances device utility. OEM collaborations with app developers can improve foldable UI/UX. Evolving materials science paves the way for lighter, more durable designs. Premium customer segment seeks early access to cutting-edge tech. Flexible displays can be extended into other devices like tablets and laptops. Growing interest in tech fashion and personalization fuels niche foldable editions. Government support for local manufacturing aids cost efficiency.

Key Players Analysis:
The market is shaped by global smartphone manufacturers, component suppliers, and display technology innovators. These players focus on R&D in flexible OLED panels, foldable hinge durability, and UI optimization. Strategic alliances are being formed between device brands and display fabricators to co-develop next-gen foldables. Supply chain partnerships ensure efficient production of ultra-thin materials and foldable glass. Companies are diversifying form factors—clamshells, book-style, rollables—to cater to different segments. Marketing emphasizes innovation, performance, and multitasking. Software optimization for foldable screens is a key differentiation strategy. Regional players are entering through mid-range foldables. Brand loyalty and ecosystem integration play vital roles in market positioning.

Conclusion:
The Foldable Smartphones Market is redefining mobile user experiences with innovation in display technology, form factors, and device functionality. While premium pricing and durability remain barriers, rapid advancements in materials and design are expanding market accessibility. Driven by growing demand for productivity, portability, and immersive interaction, foldables are evolving into a compelling alternative to traditional smartphones. With strategic collaborations and technological breakthroughs, the market is poised for robust growth, offering users the best of both smartphones and tablets. Foldable devices represent not just a trend, but a transformative shift in how the world engages with mobile technology.
 

Empowering Independence: Assistive Robotics Market Outlook 2025

Introduction:
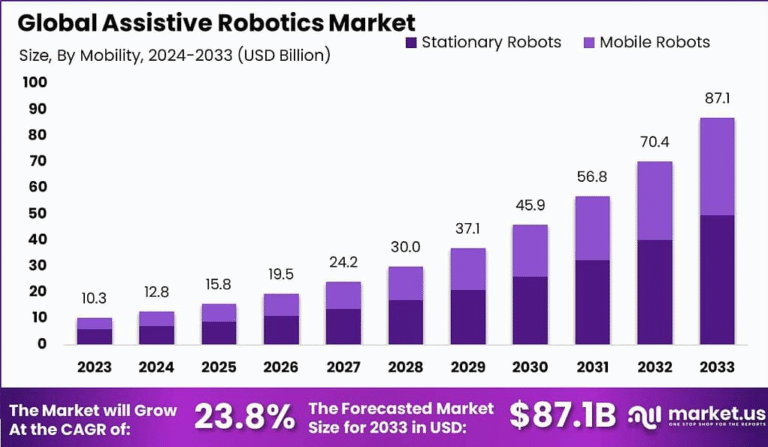
The Assistive Robotics Market is projected to exceed USD 18 billion by 2030, growing at a CAGR of over 15% from 2024. This expansion is driven by increasing demand for robotic support in elderly care, rehabilitation, and mobility assistance amid aging populations and skilled caregiver shortages. Rising adoption in healthcare, domestic, and industrial settings, combined with advances in AI, IoT, and sensor technologies, is reshaping human-assistive interaction. Governments and healthcare providers are investing in assistive robotics to enhance quality of life, reduce labor strain, and promote independent living—substantially impacting medical, residential, and service domains.

Key Takeaways:

  • Market to surpass USD 18 billion by 2030

  • 15%+ CAGR driven by healthcare and aging population

  • High adoption in hospitals, eldercare, and rehabilitation

  • AI and sensor fusion enhance human-robot interaction

  • Wearable exoskeletons gain traction in mobility support

  • Government funding boosts R&D and implementation

  • Personalized robotic assistants gaining popularity

  • Asia-Pacific emerging as a high-growth region

  • COVID-19 accelerated demand for contactless care robots

  • Cost and accessibility remain key influencing factors

Emerging Trends:
The market is witnessing rising use of AI-powered robots for personalized care and social interaction. Wearable robotic exoskeletons are advancing in post-stroke rehabilitation and elderly mobility support. Humanoid service robots are being deployed in hospitals and public facilities for navigation and assistance. Emotion-sensing and voice-interactive robots are trending in mental health applications. Cloud-connected robots allow real-time monitoring by healthcare providers. Autonomous navigation and obstacle avoidance improve safety in dynamic environments. Telepresence and remote-controlled assistive devices are enabling care continuity. Open-source platforms and modular designs are enhancing customization. Integration with smart home systems is also becoming a standard expectation.

Use Cases:

  • Robotic arms assisting individuals with physical disabilities

  • Exoskeletons aiding rehabilitation in stroke and spinal injury patients

  • Social robots providing cognitive therapy for elderly individuals

  • Robots offering mobility support in hospitals and nursing homes

  • Automated medication delivery and patient monitoring

  • Remote-controlled robots assisting isolated or bedridden patients

  • Companion robots supporting mental health and social interaction

  • Assistive drones for delivering supplies in constrained environments

  • Robots guiding visually impaired individuals in public spaces

  • Voice-activated devices enabling control of smart home systems

Major Challenges:
High initial costs limit widespread adoption, particularly in low-income regions. Lack of standardized regulations and clinical validation hampers integration in healthcare systems. Ethical concerns and trust issues surrounding robot-human interaction persist. Limited battery life and mechanical complexity affect long-term usability. Training and upskilling for care staff to operate assistive robots remain insufficient.

 Maintenance, repair infrastructure, and device interoperability pose technical barriers. Data privacy and cybersecurity risks are critical in patient-facing robots. Cultural and emotional resistance to robotic care in human-centric environments can hinder acceptance. Slow reimbursement policies and insurance coverage gaps further impede market growth in clinical applications.

Opportunities:
An aging global population offers vast demand potential for elderly care robotics. Government programs promoting digital healthcare and disability inclusion are creating funding opportunities. Technological advances in AI, machine learning, and soft robotics enable the creation of intuitive, adaptive robots. Integration with smart home ecosystems opens new domestic applications. Growing demand for home-based care solutions post-pandemic fuels remote health monitoring tools. Emerging markets provide untapped opportunities for scalable, cost-effective solutions. Partnerships between tech firms and healthcare institutions can accelerate product development and acceptance. Assistive robotics in education and workplace inclusivity also represent expanding opportunity segments in both developed and emerging economies.

Key Players Analysis:
The market features a diverse mix of robotics manufacturers, healthcare device innovators, and AI-driven startups. Key players focus on developing robotic arms, exoskeletons, and mobile assistive platforms with advanced sensors and AI capabilities. Some specialize in hospital-grade systems, while others target consumer-friendly solutions for home environments. Product portfolios often include rehabilitation tools, eldercare robots, and multi-purpose service units. Competitive strategies include investments in R&D, partnerships with healthcare providers, and modular product development for customization. Emphasis is placed on user-friendly design, regulatory approvals, and patient safety. Global expansion, after-sales service, and device affordability are critical to sustaining market leadership.

Conclusion:
The Assistive Robotics Market represents a transformative shift in healthcare and human support systems. As technological capabilities evolve and societal needs grow, assistive robots are becoming integral to caregiving, rehabilitation, and independent living. While challenges around cost, regulation, and trust remain, opportunities in AI integration, aging populations, and home-based care are accelerating adoption. With continued innovation and policy support, assistive robotics will redefine how we care for vulnerable populations, bridging gaps in workforce shortages and enhancing quality of life for millions worldwide. The future of caregiving is increasingly collaborative—between humans and machines.

Decentralizing Governance: DAO-as-a-Service (DAOaaS) Market Outlook 2025

Introduction:
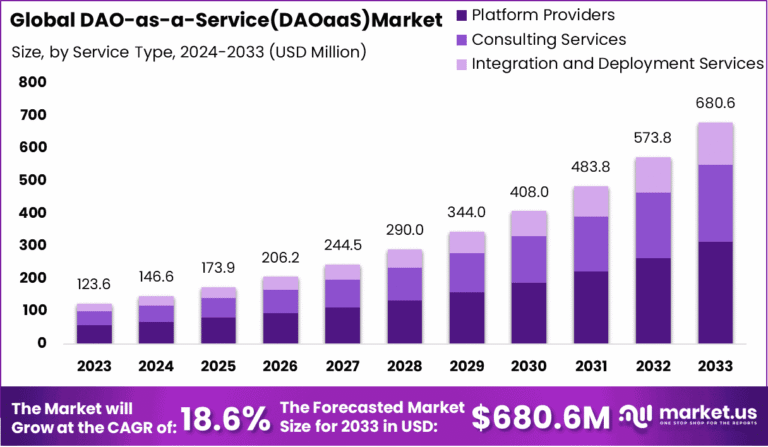
The DAO-as-a-Service (DAOaaS) market is projected to surpass USD 2.7 billion by 2030, growing at a CAGR of over 16% from 2024. This growth is fueled by the rising adoption of decentralized governance across DeFi, Web3, and enterprise sectors. DAOs streamline decision-making, improve transparency, and reduce administrative overhead, increasing demand for plug-and-play DAO solutions. Startups, DAOs, and legacy businesses alike are leveraging DAOaaS platforms for treasury management, token voting, and smart contract governance. With global interest in democratized digital ownership, DAOaaS providers are positioned at the intersection of blockchain infrastructure, legal-tech, and decentralized organizational strategy.

Key Takeaways:

  • Market to exceed USD 2.7 billion by 2030

  • CAGR projected at 16%+ from 2024 onward

  • Web3 and DeFi sectors lead adoption surge

  • DAO frameworks enable transparent governance

  • Demand from DAOs, enterprises, and DA-apps rising

  • Simplified deployment accelerates startup participation

  • Legal compliance tools gaining priority in offerings

  • Modular smart contract stacks improve customization

  • Community-driven innovation fuels platform growth

  • DAO treasury and voting modules dominate services

Emerging Trends:
Legal wrapper integration is becoming a standard feature in DAOaaS offerings to ensure compliance and limited liability. There’s growing demand for cross-chain DAO tools to unify governance across multiple blockchain ecosystems. Zero-knowledge proofs and on-chain identity are emerging to support secure, anonymous participation. Composable governance modules are being developed for greater flexibility in voting, roles, and quorum settings. AI integration is surfacing in proposal filtering and treasury optimization. DAO insurance and conflict-resolution protocols are gaining traction. The DAOaaS market is also seeing increased interest from traditional companies experimenting with decentralized governance pilots in innovation and R&D units.

Use Cases:

  • Launching fully automated DAOs for DeFi protocols

  • Enabling token-weighted voting and proposal execution

  • Managing multi-signature treasuries for digital communities

  • Supporting grants distribution in public goods funding DAOs

  • Facilitating governance of NFT projects and gaming guilds

  • Streamlining operational decisions in decentralized startups

  • Running compliance-friendly DAOs with integrated legal wrappers

  • Community governance for social media and content platforms

  • DAO-based investment clubs and venture syndicates

  • DAOaaS for creator economy tools and fan engagement

Major Challenges:
Legal uncertainty across jurisdictions makes regulatory compliance a significant hurdle. Many users lack the technical expertise to set up and manage secure DAO structures. Smart contract bugs and vulnerabilities can compromise DAO integrity and funds. Governance attacks, including vote buying and Sybil attacks, threaten decentralization. Interoperability across chains is still underdeveloped. User onboarding and interface complexity reduce accessibility. There’s often a lack of dispute resolution mechanisms and clear accountability structures. Scalability issues hinder high-frequency voting. Treasury mismanagement and insufficient transparency in resource allocation can damage DAO reputation. Privacy concerns and identity verification remain unresolved in permissionless participation models.

Opportunities:
Rising interest from enterprises exploring decentralized governance unlocks B2B opportunities for DAOaaS platforms. Integration with enterprise blockchain networks (e.g., Hyperledger, Corda) offers untapped markets. Regulatory-friendly DAOaaS platforms could become the standard for compliant governance models. Expanding creator and community-owned platforms open demand for tailored DAO tools. Web3-native verticals like gaming, DeFi, and social tokens are driving new DAO deployments. Cross-chain functionality and multichain DAOs present product innovation potential. Advanced treasury tools and incentive mechanisms create value-added differentiation. DAO analytics, performance dashboards, and governance insights offer monetizable features. Education and consulting services around DAO setup also show growth prospects.

Key Players Analysis:
The DAOaaS market is populated by blockchain infrastructure providers, governance protocol developers, and modular toolkits for DAOs. Vendors vary from end-to-end platform providers to niche governance or treasury module specialists. Core offerings include token management, voting systems, smart contract templates, and treasury interfaces. Differentiators include legal integration, user experience, scalability, and support for cross-chain assets. Partnerships with legal advisors, Web3 accelerators, and Layer-1 blockchains are strengthening market positions. Open-source communities contribute significantly to innovation, while enterprise adoption is driving demand for compliant, permissioned DAO tools. The competitive focus lies on modularity, security, transparency, and developer extensibility.

Conclusion:
DAO-as-a-Service is redefining digital organizational models by enabling secure, transparent, and autonomous governance. The market is expanding rapidly with innovations in smart contracts, cross-chain integration, and legal compliance. While challenges persist in regulation, usability, and security, the growth potential in Web3 and traditional enterprises is immense. As decentralization becomes a strategic priority, DAOaaS platforms are poised to become foundational tools for community-driven governance, digital cooperatives, and tokenized economies. This evolving sector offers a transformative shift in how organizations are built and managed in a decentralized future.


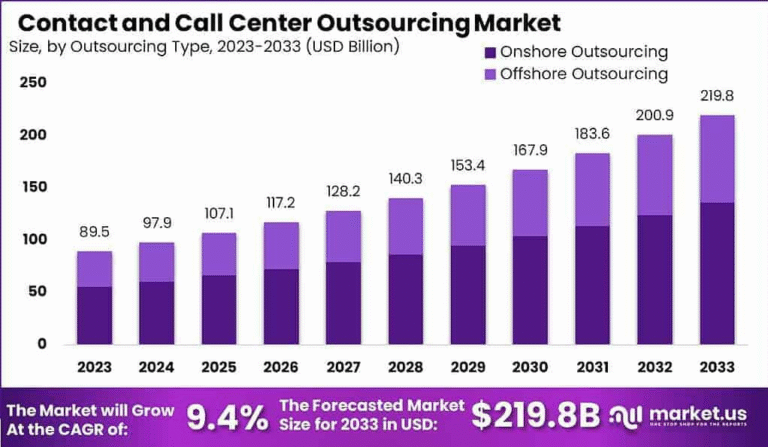
Redefining Customer Experience: Contact and Call Centre Outsourcing Market Outlook 2025

Introduction:
The Contact and Call Centre Outsourcing Market is projected to reach USD 130 billion by 2030, growing at a CAGR of 8.5% from 2024. The market’s growth is driven by the need for operational efficiency, cost savings, multilingual support, and 24/7 customer service. High demand from industries such as BFSI, retail, telecom, and healthcare is boosting outsourcing adoption. The shift toward cloud-based and omnichannel communication platforms is transforming service delivery. As businesses prioritize customer experience and scalability, outsourcing partners offer flexibility, advanced technologies, and global workforce capabilities, significantly impacting customer engagement strategies and business continuity planning.

Key Takeaways:

  • Market expected to hit USD 130 billion by 2030

  • CAGR of 8.5% reflects strong demand across verticals

  • Cost reduction and scalability drive adoption

  • Increased focus on 24/7 multilingual support

  • Rising demand from e-commerce and BFSI sectors

  • Cloud-based and AI-powered platforms gaining traction

  • Nearshore and offshore centers continue to expand

  • North America and Asia-Pacific dominate market share

  • BPO partnerships aid in CX optimization

  • Data security and compliance remain top priorities

Emerging Trends:
AI-powered chatbots and virtual agents are redefining contact center operations. Omnichannel platforms integrating voice, chat, email, and social media support are becoming standard. Cloud-native contact centers are gaining ground due to their scalability and remote-agent support. Predictive analytics and speech recognition are enhancing personalization. Robotic Process Automation (RPA) is being used to reduce response time and human error. The gig CX model, leveraging freelance agents, is gaining popularity. There’s a growing focus on emotional AI and sentiment analysis to boost customer satisfaction. Sustainability and green operations are emerging as differentiation points for outsourcing providers in a competitive market landscape.

Use Cases:

  • 24/7 technical and customer support for global clients

  • Multilingual helpdesks for international users

  • Lead generation and sales support services

  • Appointment setting and scheduling in healthcare

  • Financial service queries and fraud prevention support

  • Telecom billing and plan migration assistance

  • E-commerce order tracking and returns processing

  • Remote troubleshooting for software and IoT devices

  • Insurance claim processing and policy inquiries

  • Government helpline and citizen services outsourcing

Major Challenges:
Maintaining service quality and customer satisfaction while managing cost pressures is a persistent challenge. Data privacy and compliance with global regulations like GDPR and HIPAA are complex for outsourcing providers. Language and cultural barriers can impact customer experience. High agent attrition rates affect consistency and performance. Cybersecurity threats pose risks to sensitive customer data. 

Time zone differences and communication gaps between clients and offshore centers can delay resolutions. Integration with client IT systems is often cumbersome. Resistance to automation from traditional setups slows digital transformation. Political instability and changing trade policies also pose risks to offshore outsourcing hubs.

Opportunities:
Growing demand for digital customer engagement opens new avenues for tech-enabled outsourcing services. SMEs are increasingly outsourcing to reduce fixed costs. Emerging markets offer cost-effective labor and language diversity. Cloud infrastructure adoption supports remote and hybrid call center models. AI and analytics tools create scope for smarter customer interactions. Industry-specific outsourcing (e.g., legal, fintech, healthcare) provides specialization opportunities. Nearshore outsourcing is gaining momentum for faster collaboration. Demand for scalable, seasonal, or campaign-based support allows for flexible contract models. Upskilling programs for agents improve value delivery. Green and socially responsible outsourcing practices are becoming key decision-making criteria for clients.

Key Players Analysis:
The market consists of a blend of traditional BPO giants, digital-native outsourcing firms, and niche service providers focused on specific industries or languages. Key players offer voice and non-voice solutions, back-office support, and technology integration capabilities. Competitive differentiation lies in automation capabilities, multi-language service provision, regulatory compliance, and customer experience management.

 Partnerships with cloud communication platforms, CRM software providers, and AI developers are enhancing value propositions. Many firms operate through a global delivery model spanning onshore, nearshore, and offshore hubs. Continuous agent training, service-level innovation, and customizable engagement models help sustain competitive edge and long-term client relationships.

Conclusion:
The Contact and Call Centre Outsourcing Market is poised for sustained growth as organizations prioritize cost efficiency and enhanced customer experiences. With technology integration, multilingual capabilities, and remote operations becoming standard, outsourcing partners play a vital role in shaping global customer service models. Though the market faces challenges in compliance, attrition, and cybersecurity, significant opportunities lie in AI adoption, vertical-specific solutions, and flexible delivery models. As businesses expand across borders and digitize service touchpoints, strategic outsourcing becomes an essential lever for competitiveness and scalability, making this market a cornerstone of modern business operations.

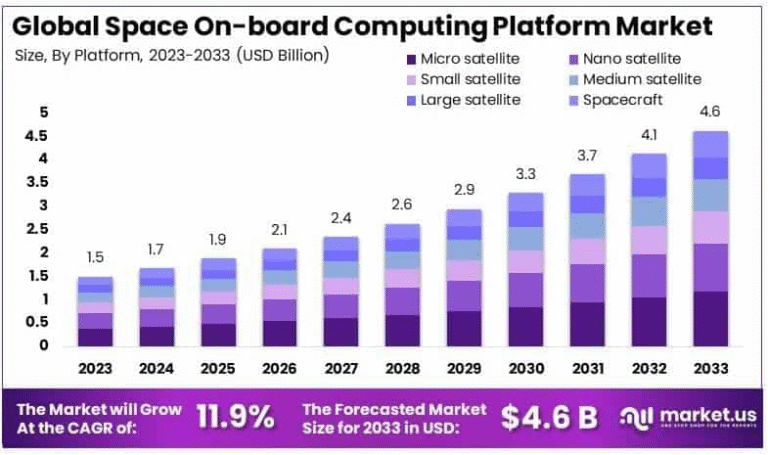
Powering the Cosmos: Space On-board Computing Platform Market Outlook 2025

Introduction:
The Space On-board Computing Platform Market is projected to surpass USD 3.2 billion by 2030, growing at a CAGR of approximately 11.8% from 2024. The market is driven by expanding satellite constellations, deep-space missions, and advancements in autonomous navigation and real-time data processing. Increasing demand for edge computing capabilities in space for Earth observation, telecommunications, and defense sectors is accelerating adoption. Miniaturization, radiation-hardened processors, and AI integration are enabling smarter, faster decision-making on board. With government and private players ramping up space exploration initiatives, the need for robust computing platforms aboard spacecraft is at an all-time high.

Key Takeaways:

  • Market to reach USD 3.2 billion by 2030 
  • 11.8% CAGR driven by LEO satellite growth 
  • High demand from defense, telecom, and R&D sectors 
  • Edge computing enables real-time in-orbit processing 
  • Miniaturized and ruggedized platforms gaining traction 
  • AI-driven autonomy is shaping next-gen systems 
  • Radiation-hardened components ensure reliability 
  • Increased demand from CubeSats and smallsats 
  • Government investments boost technological innovation 
  • Commercial space startups expanding platform use cases

Emerging Trends:
AI-enabled space computing is becoming standard for autonomous mission execution, especially in deep space and robotic exploration. There’s a rise in modular, reprogrammable FPGA-based platforms for real-time adaptability. On-board machine learning models are being deployed for anomaly detection and predictive analytics. Edge processing reduces latency in data-heavy missions, enhancing capabilities in ISR (Intelligence, Surveillance, Reconnaissance). Quantum computing research for space environments is underway, with experimental prototypes tested on satellites. Miniaturized, low-power computing systems are being designed for nano- and CubeSat missions. Open architecture designs and standards like SpaceVPX are promoting interoperability across missions and vendors.

Use Cases:

  • Real-time image processing on Earth observation satellites 
  • Autonomous navigation and trajectory correction 
  • On-board anomaly detection for spacecraft health monitoring 
  • Space-based AI applications for signal processing 
  • Low-latency communications in defense satellites 
  • Data compression before downlink to reduce bandwidth needs 
  • Distributed computing in satellite constellations 
  • AI-based climate pattern recognition using orbital data 
  • Edge analytics in planetary exploration rovers 
  • Space weather and radiation monitoring with smart sensors

Major Challenges:
Developing radiation-tolerant hardware that performs reliably in extreme space conditions remains a core challenge. Power limitations in small satellites restrict processing capabilities. Heat dissipation in microgravity environments poses design complexity. Ensuring software redundancy and fault tolerance is critical, given the lack of maintenance access. Cost constraints for advanced computing units hinder adoption in budget-constrained missions. Limited testing infrastructure for in-orbit performance adds technical risks. Integration of AI in a safety-critical environment is still evolving. Interoperability between mission-specific and standardized systems is complex. Cybersecurity for in-orbit platforms remains underdeveloped. Long mission durations demand high durability and long-term software support.

Opportunities:
Increased space commercialization and satellite proliferation open significant opportunities for computing platform vendors. SmallSat and CubeSat missions are driving demand for compact, low-power processors. Governmental space agencies are investing in onboard AI, creating R&D opportunities. Interplanetary and lunar missions need high-performance edge computing for autonomous operations. Defense applications for ISR and secure communication are on the rise. Integration of advanced sensors in satellites generates real-time data analytics needs. Development of scalable, modular systems can serve multiple mission profiles. Collaborations between aerospace firms and tech startups offer scope for innovation. Education and research programs boost demand for affordable experimental platforms.

Key Players Analysis:
The market is composed of a blend of aerospace system integrators, semiconductor manufacturers, and specialized computing platform providers. Companies offer solutions ranging from general-purpose processors to mission-specific ruggedized boards with radiation hardening. Some players focus on small satellite applications with miniaturized platforms, while others cater to deep-space exploration with high-performance computing systems. Competition centers around SWaP (Size, Weight, and Power) optimization, fault tolerance, and AI capabilities. Firms often invest in R&D to innovate edge AI, real-time processing, and energy efficiency. Strategic collaborations with space agencies and private satellite operators are common to validate and commercialize new computing platforms.

Conclusion:
The Space On-board Computing Platform Market is becoming integral to modern space missions, enabling autonomy, real-time analytics, and robust communication. As the space economy diversifies, from scientific exploration to commercial ventures, computing capabilities must scale accordingly. Despite challenges in power, reliability, and security, innovations in AI, radiation hardening, and miniaturization continue to push the frontier. With governments and private players accelerating investments, the market offers ample opportunity for technological breakthroughs and strategic growth. As missions become smarter and more autonomous, onboard computing will remain a critical enabler of the next generation of space exploration and satellite services.


Methyl Acetate Market Demand Rises on Green Chemistry Push in Paints, Pharma and Food Industries

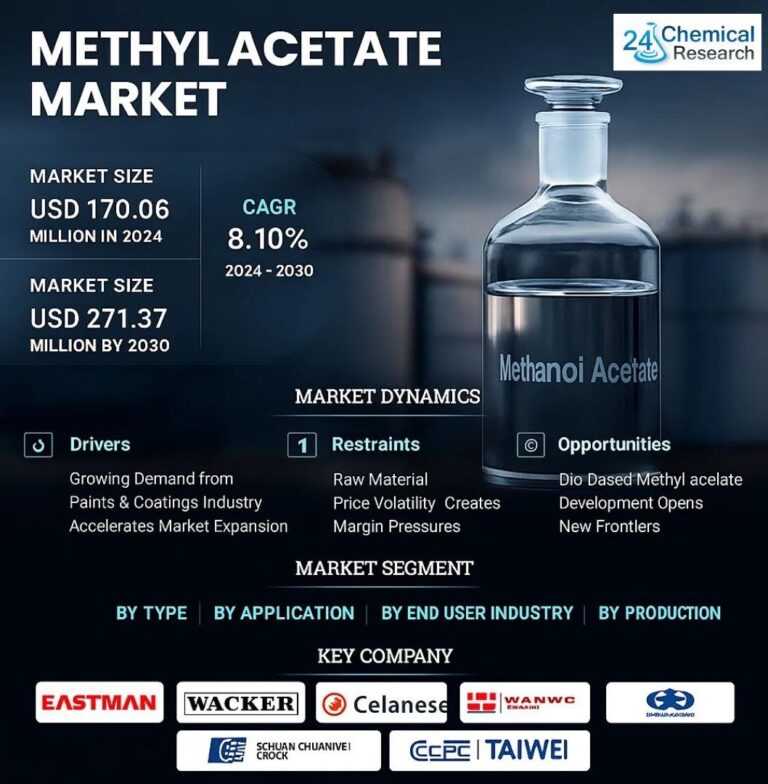
Global methyl acetate industry is experiencing renewed momentum as industries from paints & coatings to pharmaceuticals increasingly seek safer and eco-friendlier solvents. As of 2024, the methyl acetate market reached a valuation of USD 170.06 million, and forecasts indicate it will grow to approximately USD 271.37 million by 2030, with a CAGR of 8.1%.

Known for its fast evaporation rate, low toxicity, and excellent solvency power, methyl acetate is gaining favor in industrial applications where regulatory compliance and environmental performance are key. The solvent is increasingly being used in pharmaceutical tablet coatings, food-grade flavor carriers, and low-VOC paints, making it a cornerstone of sustainable chemical manufacturing.

Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/260783/global-methyl-acetate-market-2024-655

Bio-Based Solvents Gaining Ground

As chemical producers work to align with stricter environmental mandates, attention is turning toward bio-based methyl acetate. Several manufacturers have recently announced pilot-scale investments in green production technologies that replace fossil-derived feedstocks. A June 2025 update from Chemical & Engineering News reports that multiple East Asian and European firms are advancing R&D into bio-acetylation routes using agricultural waste as a base for sustainable ester production.

This transition is in line with broader global efforts to reduce reliance on volatile organic compounds (VOCs). In North America, regulatory agencies continue to enforce VOC thresholds in coatings and adhesives, prompting formulators to adopt methyl acetate due to its favorable environmental profile.

Segment Analysis:

By Type

Pure Methyl Acetate Dominates the Market Due to High Purity Requirements in Specialty Applications

The market is segmented based on type into:

  • Pure Methyl Acetate
    • Subtypes: Pharmaceutical grade, Industrial grade, and others
  • Coarse Methyl Acetate
  • Modified Methyl Acetate
    • Subtypes: Low-VOC formulations, Azeotropic mixtures, and others
  • Others

By Application

Solvents Segment Leads Due to Wide Industrial Use in Coatings and Adhesives

The market is segmented based on application into:

  • Solvents
    • Subtypes: Coatings, Adhesives, Inks, and others
  • Pharmaceutical intermediates
  • Food additives
  • Cosmetics
  • Others

By End User Industry

Paints & Coatings Industry Dominates Due to Growing Construction Activities

The market is segmented based on end user industry into:

  • Paints & Coatings
  • Pharmaceuticals
  • Food & Beverage
  • Personal Care
  • Others

By Production Process

Esterification Process Segment Leads Due to High Production Efficiency

The market is segmented based on production process into:

  • Esterification
  • Carbonylation
  • Others

Regional Outlook: Asia-Pacific Leads, Emerging Markets Rise

Asia-Pacific remains the dominant hub, accounting for over 45% of global methyl acetate production, led by China’s large-scale chemical infrastructure and expanding paints, coatings, and pharmaceutical sectors. India and Southeast Asia are also witnessing increased methyl acetate consumption due to rising demand in food processing and cosmetic formulations.

Meanwhile, North America remains a vital contributor due to stringent chemical regulations and innovation in green solvent development. Europe, particularly Germany and France, continues to support methyl acetate adoption with regional sustainability frameworks and incentives for non-toxic alternatives. Infrastructure gaps and trade limitations continue to restrict broader adoption in Latin America and parts of the Middle East & Africa, though demand potential remains high.

Industrial Momentum and Sectoral Adoption

Paints & coatings sector currently drives roughly 42% of methyl acetate consumption, followed closely by pharmaceuticals, where the solvent is used in transdermal systems and drug coatings. The food and cosmetics sectors are emerging as significant growth avenues, leveraging methyl acetate’s FDA-approved status and superior evaporation characteristics.

Additionally, the electronics and polymer industries are beginning to explore high-purity methyl acetate grades for cleaning and precision manufacturing processes. This trend reflects increasing demand for safer, performance-focused solvents that align with occupational health standards.

Challenges: Volatility and Compliance Complexity

Producers continue to grapple with cost fluctuations tied to methanol and acetic acid, the two primary raw materials in methyl acetate synthesis. Prices have shown instability in recent quarters, pressuring margins and influencing global pricing strategies.

In addition, navigating regional compliance standards has grown more complex, as regulations differ widely across North America, Europe, and Asia. Trade restrictions and protectionist tariffs in certain countries are also introducing friction into global supply chains.

Key Players Leading in the Market:

  • Eastman Chemical Company
  • Wacker Chemie AG
  • Celanese Corporation
  • Anhui Wanwei Group
  • Sichuan Chuanwei Group
  • Chang Chun Group
  • Hunan Xiangwei Group
  • Sinochem Qingdao
  • Shanxi Sanwei Group
  • RuiFeng Polymer Materials

Get Full Report Here: https://www.24chemicalresearch.com/reports/260783/global-methyl-acetate-market-2024-655

About 24chemicalresearch

Founded in 2015, 24chemicalresearch has rapidly established itself as a leader in chemical market intelligence, serving clients including over 30 Fortune 500 companies. We provide data-driven insights through rigorous research methodologies, addressing key industry factors such as government policy, emerging technologies, and competitive landscapes.

  • Plant-level capacity tracking
  • Real-time price monitoring
  • Techno-economic feasibility studies

With a dedicated team of researchers possessing over a decade of experience, we focus on delivering actionable, timely, and high-quality reports to help clients achieve their strategic goals. Our mission is to be the most trusted resource for market insights in the chemical and materials industries.

International: +1(332) 2424 294 | Asia: +91 9169162030

Website: https://www.24chemicalresearch.com/

Follow us on LinkedIn: http://www.linkedin.com/company/24chemicalresearch

Generative AI in Packaging Market Sees Fastest Growth in Asia-Pacific as E-Commerce and Automation Take Center Stage

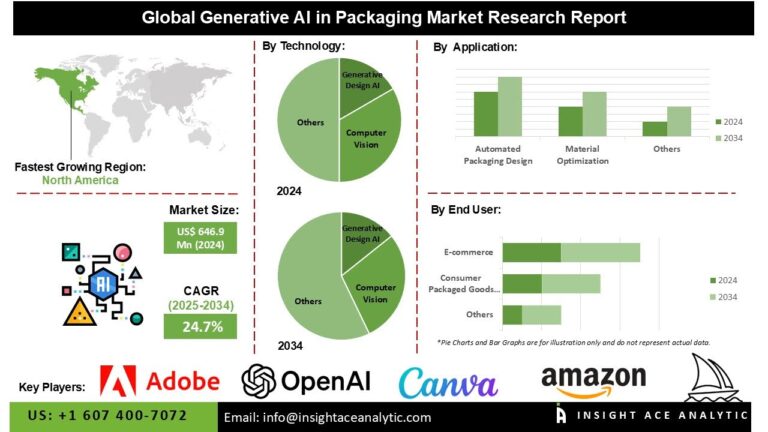
According to the latest research by InsightAce Analytic, the Generative AI in Packaging Market is valued at USD 646.9 Mn in 2024 , and it is expected to reach USD 5,813.2 Mn by the year 2034, with a CAGR of 24.7% during the forecast period of 2025-2034.

Generative AI in the packaging industry leverages advanced algorithms to design and optimize packaging solutions based on various parameters, including consumer preferences, structural stability requirements, and material efficiency. These AI-driven systems can rapidly develop innovative packaging concepts, simulate performance characteristics, and autonomously refine designs to meet functional and aesthetic criteria.

Key applications include personalized packaging for targeted marketing campaigns, automated structural design, optimization of material usage for enhanced durability and cost-effectiveness, and virtual testing to ensure compliance with regulatory standards and durability benchmarks. The market for generative AI in packaging is experiencing significant growth, fueled by improved access to design and sustainability datasets, advancements in computational infrastructure, rising demand for faster and more tailored design workflows, regulatory pressures to minimize environmental impact, and increased investment by packaging companies in digital transformation initiatives.

 Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/3126

 List of Prominent Players in the Generative AI in Packaging Market:

  •   Adobe Inc.
  •   Cognex Corporation
  •   Clarifai
  •   Amazon Inc.
  •   Microsoft Corporation
  •   GE Digital
  •   ABB Group
  •   Neurala
  •   OpenAI
  •   Midjourney Inc.
  •   Canva
  •   PackageX Inc.

Market Dynamics

Drivers:

In today’s consumer-centric economy, personalization has transitioned from a premium feature to an expected standard. Generative artificial intelligence (AI) is increasingly being employed to develop adaptive packaging designs that align with seasonal themes, cultural trends, and individual consumer preferences. This approach not only reinforces brand identity but also significantly enhances the overall customer experience. By leveraging AI, companies can generate distinct packaging forms, customized label designs, and targeted messaging tailored to specific consumer segments, thereby creating a more individualized product offering. This strategy is particularly valuable in sectors such as luxury goods, food and beverage, and cosmetics. Consequently, the rising demand for personalized and customized packaging solutions is expected to be a key driver for market growth during the forecast period.

 Challenges:

The implementation of generative AI involves substantial initial investments in cloud infrastructure, software licensing, and skilled personnel. While large enterprises often have the resources to absorb these costs, small and medium-sized enterprises (SMEs) frequently face difficulties justifying the return on investment. Additionally, challenges related to the integration of generative AI with existing design and production systems—such as retraining staff and system upgrades—can further escalate operational costs. These financial and technical barriers may limit market accessibility for SMEs, hindering widespread adoption.

 Regional Trends:

North America is anticipated to lead the generative AI in packaging market in terms of revenue share, driven by its advanced technological ecosystem, early adoption of AI solutions, and presence of established packaging companies. The United States, in particular, is at the forefront of innovation in AI-driven packaging applications, including automated design, predictive quality assurance, and consumer-focused personalization. Strong investment in AI research and development, along with active collaboration between technology firms and packaging manufacturers, continues to reinforce the region’s dominant position.

Meanwhile, the Asia Pacific region is projected to experience the fastest growth throughout the forecast period. This expansion is supported by the rapid growth of e-commerce, accelerating industrialization, and significant advancements in factory automation. Countries such as China, Japan, South Korea, and India are increasingly leveraging generative AI in packaging to optimize material usage, reduce costs, and support mass customization. Additionally, favorable government policies, a rising middle-class population, and growing demand for consumer products are contributing to the region’s robust market expansion.

Recent Development:

  • May 2025: Canva unveiled Magic Studio, an AI-powered suite that streamlines creative processes by giving teams access to the greatest AI-manual features at the same time, enabling them to produce final projects more quickly and easily.

 Segmentation of Generative AI in Packaging Market-

By Deployment Mode-

  • Cloud-Based
  • On-Premises

By Technology-

  • Generative Design AI
  • Natural Language Processing (NLP)
  • Computer Vision
  • AI-powered Simulation and Testing

By Application-

  • Material Optimization
  • Automated Packaging Design
  • Predictive Maintenance and Quality Control
  • Personalization and Segmentation of One
  • Supply Chain and Logistics Optimization

By End-User-

  • E-commerce
  • Consumer Packaged Goods (CPG)
  • Pharmaceuticals
  • Food and Beverage
  • Cosmetics and Personal Care

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

 About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Gene Therapy Platform Market to Grow at Robust CAGR Amid Increased FDA Approvals and Clinical Pipeline Expansion

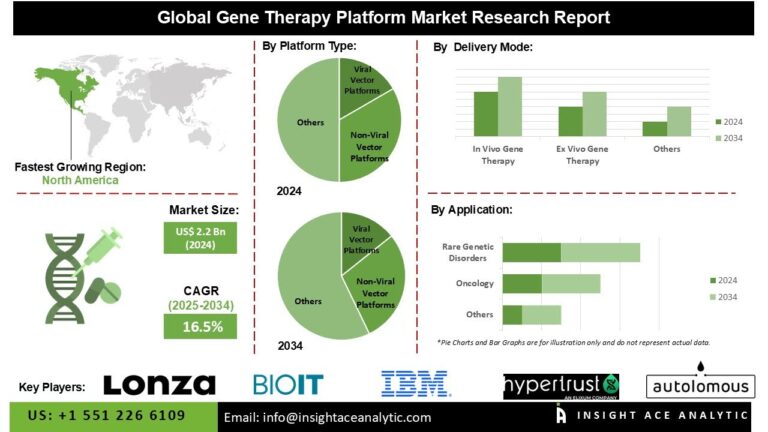
According to the latest research by InsightAce Analytic, the Global Gene Therapy Platform Market is valued at USD 2.2 Bn in 2024 , and it is expected to reach USD 9.8 Bn by 2034 , with a CAGR of 16.5%  during the forecast period of 2025-2034.

Gene therapy has emerged as one of the most transformative advancements in modern medicine, offering durable therapeutic solutions by modifying, replacing, or silencing faulty genes responsible for disease progression—particularly in rare or previously untreatable genetic disorders. The gene therapy platform market encompasses the foundational technologies and delivery systems that enable these therapies, including gene editing tools and both viral and non-viral vectors. Several key factors are driving market expansion: rapid technological innovation, a growing prevalence of chronic and hereditary diseases, increased funding and investment in biopharmaceutical research, and the establishment of regulatory frameworks that support accelerated approvals.

Furthermore, the rising number of U.S. FDA approvals for gene therapies targeting rare and inherited conditions has validated the clinical promise of these platforms, thereby stimulating further research and commercial interest. Scalable gene therapy platforms capable of supporting the efficient development and manufacturing of personalized treatments are attracting significant investment from biotechnology and pharmaceutical companies seeking to capitalize on the evolving landscape of precision medicine.

 Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/3082

 List of Prominent Players in the Gene Therapy Platform Market:

  •   Lonza
  •   BioIT
  •   L7 Informatics, Inc.
  •   TrakCel
  •   IDBS
  •   Sarepta Therapeutics, Inc.
  •   CRISPR Therapeutics
  •   Precision BioSciences
  •   AstraZeneca
  •   Andelyn Biosciences
  •   Novartis
  •   SAP SE
  •   Autolomous Ltd
  •   DEEP GENOMICS
  •   ElevateBio
  •   Renova Therapeutics
  •   Hypertrust Patient Data Care (Part of Accenture)
  •   IBM
  •   Others

 Market Dynamics

Drivers:

The growth of the gene therapy platform market is primarily driven by the rising global incidence of cancer and other target diseases that demand advanced and effective treatment solutions. The increasing prevalence of cancer is anticipated to be a major catalyst for market expansion over the forecast period. According to the American Cancer Society, approximately 1.9 million new cancer cases and 609,360 cancer-related deaths were projected in the United States in 2022, equating to around 1,670 deaths per day. Globally, lung, colorectal, prostate, and female breast cancers account for roughly 43% of all newly diagnosed cancer cases. This escalating disease burden underscores the urgent need for innovative therapeutic strategies, thereby propelling demand for gene therapy platforms. Gene therapy has demonstrated strong potential as a targeted cancer treatment by delivering therapeutic genes directly into malignant cells or adjacent tissues to inhibit tumor growth or induce cell death.

 Challenges:

Despite the promise of gene therapy, the platform faces notable manufacturing and scalability challenges. The production of viral vectors—particularly adeno-associated virus (AAV) and lentivirus—requires advanced bioprocessing infrastructure, stringent quality controls, and highly trained personnel, resulting in substantial operational and capital expenditures. These requirements can limit accessibility, especially for small- and mid-sized biotechnology firms. Moreover, autologous therapies, which involve patient-specific customization, further elevate production complexity, costs, and timelines. Additional hurdles include inconsistent production yields, purification bottlenecks, and complex regulatory compliance processes. Collectively, these factors hinder large-scale commercialization and raise concerns about affordability, particularly in low- and middle-income regions.

 Regional Trends:

North America is anticipated to maintain a dominant position in the gene therapy platform market in terms of revenue. This is attributed to robust public and private investment, a high concentration of key industry players, and continued advancements in gene therapy research and development. The prevalence of target diseases across the region further supports sustained market demand. Meanwhile, Europe is projected to experience the fastest growth during the forecast period, driven by a strong focus on precision medicine and genetically targeted therapies. European nations—particularly the United Kingdom, Germany, and France—are actively investing in biotechnology infrastructure. Government initiatives and research programs across the region are emphasizing gene therapy delivery systems for applications in oncology, cardiovascular diseases, and rare genetic disorders, thereby fostering market expansion.

 Recent Development:

  •       February 2025: Andelyn Biosciences expands its AAV Curator platform to further innovate gene therapy. Under the terms of the agreement, Andelyn is authorized to conduct research and development services using Stanton Lab CNS capsids for its clients who are creating gene treatments.
  •       December 2024: MRC created its first two Centres of Research Excellence with the goal of developing cutting-edge treatments for diseases that are now incurable. The MRC CoREs bring together leading academic and industry expertise to speed up clinical application and translational research of advanced therapeutics. This promotes innovation, infrastructure development, and regulatory advancements that directly benefit and grow the gene therapy platform industry.
  •       May 2023: The US-based software business Form Bio, which specializes in life sciences, introduced FORMsightAI, a new suite of AI-based solutions for forecasting and maximizing the production results of cell and gene therapy structures. The full-service solution combines state-of-the-art, flexible AI models with Form Bio’s foundational platform and a proficient group of computational life sciences professionals with expertise in data science, bioinformatics, and biology. Common problems that cell and gene therapy companies encounter include build truncations and manufacturing contaminations, which are significant contributors to unacceptable low manufacturing yields, protracted time to market, and issues with therapeutic safety. FORMsightAI solves these issues.

Segmentation of Gene Therapy Platform Market-

Gene Therapy Platform Market- By Platform

  • Viral Vector Platforms
    • Adenovirus
    • Adeno-associated Virus (AAV)
    • Retrovirus
    • Lentivirus
    • Herpes Simplex Virus (HSV)
  • Non-Viral Vector Platforms
    • Electroporation & Microinjection Platforms
    • Polymer-based Delivery Systems
    • Lipid Nanoparticles (LNPs)
    • Naked DNA/RNA Delivery
  • Gene Editing Platforms
    • TALENs
    • CRISPR-Cas Systems
    • ZFNs

Gene Therapy Platform Market- By Delivery Mode

  • In Vivo Gene Therapy
  • Ex Vivo Gene Therapy
    • Allogeneic Cell-Based Gene Therapy
    • Autologous Cell-Based Gene Therapy
  • In-situ Gene therapy

Gene Therapy Platform Market- By Application

  • Cardiovascular Diseases
  • Oncology
  • Rare Genetic Disorders
  • Neurological Disorders
  • Ophthalmic Diseases
  • Hematological Disorders
  • Musculoskeletal Disorders
  • Infectious Diseases

Gene Therapy Platform Market- By End-User

  • Hospitals & Gene Therapy Centers
  • Academic & Research Institutions
  • Pharmaceutical & Biotechnology Companies
  • Contract Development & Manufacturing Organizations (CDMOs)

Gene Therapy Platform Market- By Region

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Tri-structural Isotropic (TRISO) Fuel Market Expands in North America Backed by DoE Collaborations and Licensing Campaigns

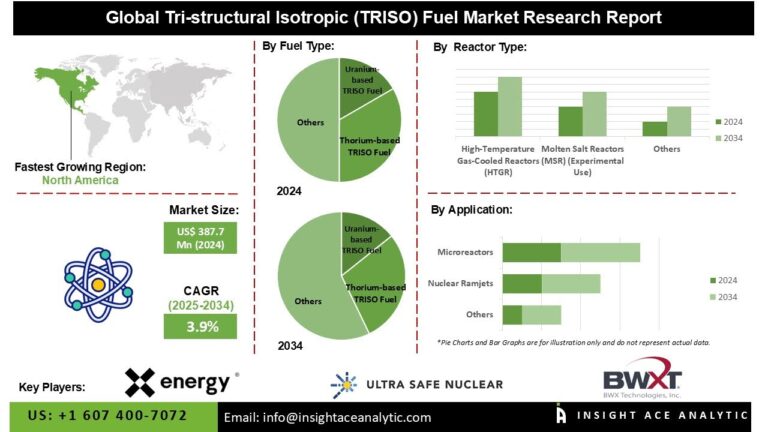
According to the latest research by InsightAce Analytic, the Tri-structural Isotropic (TRISO) Fuel Market is valued at USD 387.7 Mn in 2024 , and it is expected to reach USD 558.4 Mn by the year 2034, with a CAGR of 3.9% during the forecast period of 2025-2034.

Tri-structural isotropic (TRISO) fuel represents an advanced form of nuclear fuel engineered for deployment in next-generation nuclear reactors, including high-temperature gas-cooled reactors (HTGRs). This fuel consists of uranium, thorium, or plutonium-based fuel kernels encapsulated in three layers of ceramic and carbon materials, specifically designed to enhance structural integrity under extreme conditions, improve fission product retention, and increase accident tolerance. TRISO fuel offers a safer and more efficient alternative to conventional nuclear fuels and is increasingly utilized across a range of applications, including clean energy generation, military microreactors, and space exploration.

The market growth for TRISO fuel is being driven by increased investments in energy security, decarbonization initiatives, and the development of advanced reactor technologies. Its robust performance characteristics make it a pivotal component in the transition toward low-carbon nuclear energy solutions.

Furthermore, TRISO fuel is enabling the advancement of microreactor technologies, which are being developed to deliver reliable, off-grid power to critical infrastructure and remote communities. The continued expansion of the TRISO fuel market is supported by cross-disciplinary innovations in reactor physics, materials science, and digital engineering. As these fields converge, TRISO fuel is well-positioned to meet the evolving requirements of emerging reactor designs, solidifying its role in the future of resilient, sustainable nuclear energy systems. 

Check this Report Brochure : https://www.insightaceanalytic.com/request-sample/3103

List of Prominent Players in the Tri-structural Isotropic (TRISO) Fuel Market:

  •   Ultra Safe Nuclear Corporation
  •   BWX Technologies, Inc. (BWXT)
  •   X-energy
  •   General Atomics
  •   Centrus Energy
  •   Others

Market Dynamics

Drivers:

The Tri-structural Isotropic (TRISO) fuel market is gaining significant momentum, driven by the increasing deployment of modular reactor technologies that emphasize scalability and advanced safety features. Numerous small modular reactor (SMR) developers have integrated TRISO fuel into high-temperature gas-cooled reactor (HTGR) designs, achieving peak burnup rates exceeding 20% enrichment. Enhanced kernel engineering techniques are delivering consistent particle uniformity, which contributes to extended reactor operation cycles and improved load-following performance. In 2024, more than 15 commercial SMR prototype initiatives worldwide validated TRISO fuel compatibility, signaling strong market demand. Consequently, the industry is witnessing a rise in design-specific adaptations, including prismatic block and pebble-bed core configurations, further accelerating TRISO fuel adoption. 

Challenges:

Supply chain limitations pose a significant barrier to the broader commercialization of TRISO fuel. The availability of high-assay low-enriched uranium (HALEU) remains constrained, as enrichment capabilities are currently limited to a small number of licensed facilities globally. Additionally, the production of essential components, such as high-purity graphite and silicon carbide coatings, requires rigorous quality control, leading to extended lead times, often exceeding 12 months. In 2024, over 70% of qualification delays were attributed to component shortages, highlighting critical vulnerabilities within existing supply frameworks. As a result, stakeholders are increasingly exploring alternative material sourcing strategies and the development of regional manufacturing hubs to ensure supply chain resilience. 

Regional Trends:

North America is expected to dominate the TRISO fuel market in terms of revenue, supported by strong policy emphasis on clean energy, ongoing advancements in high-temperature gas-cooled reactor (HTGR) technologies, and improvements in TRISO fuel production scalability and cost-efficiency. Strategic collaborations between the U.S. Department of Energy and national laboratories—particularly the Idaho National Laboratory—are accelerating technology validation through certification initiatives and digital twin integration.

Meanwhile, the Asia Pacific region is projected to experience the highest growth rate during the forecast period, fueled by substantial investments in nuclear power infrastructure by countries such as China, Japan, and South Korea. China’s HTGR program has reached a key milestone with operational demonstration units in Sichuan province, while Japan’s Atomic Energy Agency is advancing its TRISO fuel production capabilities through pilot manufacturing lines. The region’s focus on low-carbon energy sources continues to drive demand for TRISO fuel as a cornerstone of advanced nuclear technology development. 

Segmentation of Tri-structural Isotropic (TRISO) Fuel Market-

By Reactor Type-

  • Microreactors & Small Modular Reactors (SMRs)
  • High-Temperature Gas-Cooled Reactors (HTGR)
    • Pebble Bed Reactors (PBR)
    • Prismatic Block Reactors
  • Molten Salt Reactors (MSR) (Experimental Use)
  • Others

By Fuel Type-

  • Thorium-based TRISO Fuel
  • Uranium-based TRISO Fuel
    • Uranium Dioxide (UO₂)
    • Uranium Oxycarbide (UCO)

By Application-

  • Nuclear Thermal Propulsion (NTP)
  • Nuclear Ramjets
  • Microreactors
  • Research & Development in Advanced Reactors
  • Others

By End Use-

  • Nuclear Power Plant
  • Research Institutions & Universities
  • Government & Defense Agencies
  • Space Agencies
  • Others

By Region-

North America-

  •       The US
  •       Canada

Europe-

  •       Germany
  •       The UK
  •       France
  •       Italy
  •       Spain
  •       Rest of Europe

Asia-Pacific-

  •       China
  •       Japan
  •       India
  •       South Korea
  •       South East Asia
  •       Rest of Asia Pacific

Latin America-

  •       Brazil
  •       Argentina
  •       Mexico
  •       Rest of Latin America

 Middle East & Africa-

  •       GCC Countries
  •       South Africa
  •       Rest of the Middle East and Africa

About Us:

InsightAce Analytic is a market research and consulting firm that enables clients to make strategic decisions. Our qualitative and quantitative market intelligence solutions inform the need for market and competitive intelligence to expand businesses. We help clients gain competitive advantage by identifying untapped markets, exploring new and competing technologies, segmenting potential markets and repositioning products. Our expertise is in providing syndicated and custom market intelligence reports with an in-depth analysis with key market insights in a timely and cost-effective manner.


Optimizing Digital Presence: SEO Software Market Outlook 2025

Introduction:
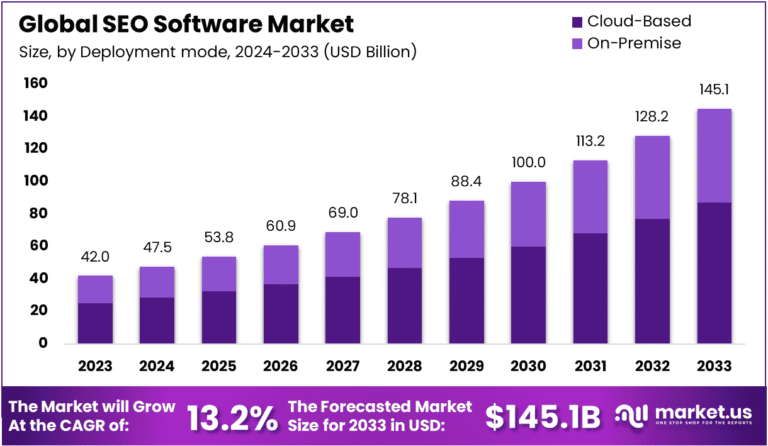
The SEO Software Market is projected to exceed USD 8.5 billion by 2030, expanding at a CAGR of over 14% from 2024. This surge is driven by the growing digital economy, increasing reliance on organic search traffic, and rising competition in online visibility. Businesses across industries, especially e-commerce, media, and services, are investing in SEO tools for keyword analysis, content optimization, backlink monitoring, and analytics. Demand has been significantly influenced by shifts in consumer behavior toward digital platforms. The evolving search engine algorithms and the integration of AI and automation are further fueling market demand for advanced SEO solutions.

Key Takeaways:

  • Market expected to reach USD 8.5 billion by 2030

  • CAGR of 14% from 2024, driven by digital marketing expansion

  • High demand from e-commerce and content-driven platforms

  • AI integration in SEO tools accelerating adoption

  • Cloud-based platforms dominate the deployment model

  • Emphasis on mobile and voice search optimization

  • Increasing relevance of local and image SEO

  • Enhanced ROI tracking capabilities gaining traction

  • Rising importance of multilingual SEO for global markets

  • Growing SME participation due to SaaS-based accessibility

Emerging Trends:
AI and machine learning are transforming SEO by automating keyword research, content creation, and performance forecasting. Voice and visual search optimization are becoming core functionalities, driven by smart devices and consumer behavior. Predictive analytics for traffic and ranking trends are gaining traction. Integration of SEO tools with CMS platforms and marketing automation systems is rising. There’s a growing demand for mobile-first indexing tools and SERP feature tracking. Tools offering real-time SEO audits and competitor benchmarking are trending. Ethical SEO practices, such as E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness), are increasingly embedded in tool features to align with evolving search engine standards.

Use Cases:

  • Conducting keyword research to drive targeted traffic

  • Optimizing website structure for search engine indexing

  • Monitoring backlink profiles and domain authority

  • Generating SEO audits for website performance improvement

  • Analyzing competitors’ keywords and content strategies

  • Tracking SERP rankings across multiple geographies

  • Enhancing content for voice and image-based search

  • Integrating SEO metrics with analytics dashboards

  • Automating SEO tasks for large-scale websites

  • Improving local SEO visibility for multi-location businesses

Major Challenges:
Frequent algorithm updates by search engines create adaptation challenges for software providers. High competition among SEO tools leads to pricing pressure and feature saturation. Data privacy regulations like GDPR limit tracking and personalization capabilities. Users often lack the technical expertise to fully utilize software capabilities. Integration with legacy CMS and web platforms remains a hurdle. Measuring accurate SEO ROI is complex due to indirect impact. Voice and visual search tracking present data limitations. Ensuring multilingual and regional search accuracy adds technical challenges. Managing SEO across multiple digital platforms requires cross-functional coordination. Market fragmentation causes confusion in tool selection.

Opportunities:
Rising digital transformation in SMEs opens demand for easy-to-use SEO tools. Expansion of multilingual and cross-border e-commerce fuels global SEO needs. Increasing mobile usage creates room for mobile-optimized SEO platforms. AI-driven personalization and automation offer differentiation. Educational platforms and freelancers present a growing market for affordable SEO tools. Integration with analytics, CRM, and e-commerce systems adds value. Real-time and predictive SEO insights offer strategic benefits to marketers. Voice and local search optimization provide niche tool development opportunities. Demand for ethical and sustainable SEO aligns with brand safety trends. White-label and API-enabled SEO solutions enable B2B SaaS partnerships.

Key Players Analysis:
The SEO Software Market is characterized by a mix of established digital marketing platforms and emerging tech innovators. These players offer keyword analysis, content optimization, backlink tracking, and rank monitoring tools. Some provide niche-specific solutions for agencies, SMEs, and enterprise-scale businesses. Competitive differentiation is driven by AI features, UI/UX design, integration capabilities, and pricing models. 

Freemium and SaaS models dominate, with a growing shift toward cloud-native platforms. Vendors focus on regional localization, multilingual support, and mobile responsiveness. Strategic partnerships with content management systems and e-commerce platforms are common. Continuous feature updates and user training modules enhance customer retention.

Conclusion:
The SEO Software Market is rapidly evolving, powered by digital adoption, AI advancements, and the need for online visibility in a competitive landscape. As businesses increasingly shift to organic digital marketing strategies, SEO tools are becoming essential for sustaining growth. Despite challenges like algorithm volatility and data privacy, opportunities abound in mobile, voice, and cross-border SEO. With technological innovation and a customer-centric approach, the market is poised for sustained expansion. Businesses that effectively leverage these tools will gain measurable advantages in traffic, engagement, and digital ROI, making SEO software an indispensable component of modern marketing ecosystems.